Breaking: US private sector payrolls rise 63,000 in February vs 50,000 forecast
Private sector employment in the US rose 63,000 in February and annual pay was up 4.5%, the Automatic Data Processing (ADP) Research Institute reported on Wednesday. This print followed the 11,000 increase (revised from 22,000) recorded in January and beat the market expectation of 50,000.
Commenting on the survey's findings, "we've seen an increase in hiring and pay gains remain solid, especially for job-stayers,” said Nela Richardson, chief economist at ADP. "But with hiring concentrated in only a few sectors, our data shows no widespread pay benefit from changing jobs. In fact, the pay premium for switching employers hit a record low in February,” Richardson added.
Market reaction
The US Dollar (USD) Index largely ignored this data and was last seen losing 0.3% on the day at 98.78.
US Dollar Price Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the weakest against the New Zealand Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.22% | -0.06% | -0.31% | -0.04% | -0.18% | -0.45% | -0.13% | |
| EUR | 0.22% | 0.15% | -0.07% | 0.18% | 0.04% | -0.23% | 0.09% | |
| GBP | 0.06% | -0.15% | -0.23% | 0.02% | -0.11% | -0.39% | -0.06% | |
| JPY | 0.31% | 0.07% | 0.23% | 0.27% | 0.13% | -0.15% | 0.17% | |
| CAD | 0.04% | -0.18% | -0.02% | -0.27% | -0.14% | -0.41% | -0.09% | |
| AUD | 0.18% | -0.04% | 0.11% | -0.13% | 0.14% | -0.27% | 0.05% | |
| NZD | 0.45% | 0.23% | 0.39% | 0.15% | 0.41% | 0.27% | 0.31% | |
| CHF | 0.13% | -0.09% | 0.06% | -0.17% | 0.09% | -0.05% | -0.31% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
This section below was published as a preview of the US ADP Employment Change data at 05:00 GMT.
- The US ADP Employment Change report is expected to show the private sector added 50K new positions in February.
- The Middle East war is likely to maintain the flows into safe-haven assets.
- The US Dollar Index added roughly 1.7% and nears the critical 100 threshold.
The Automatic Data Processing (ADP) Research Institute will release its monthly report on private-sector job creation for February on Wednesday. The so-called ADP Employment Change report is expected to show that the United States (US) private sector added 50K new positions in the month, following the 22K gained in January.
As usual, the ADP report will precede the US Bureau of Labor Statistics Nonfarm Payrolls (NFP) report scheduled for Friday. The latter offers a comprehensive view of the employment situation in the country, as it includes private and government jobs alongside the monthly Unemployment Rate, a critical figure for the Federal Reserve (Fed), which bases its decisions on both employment and inflation levels.
ADP Jobs Report to be overshadowed by geopolitical turmoil
There is no clear near-term correlation between the ADP Employment Change report and the Nonfarm Payrolls report, meaning a strong ADP does not guarantee a similarly upbeat NFP. Nevertheless, the figures tend to impact the US Dollar (USD), with better-than-anticipated figures generally boosting demand for the Greenback.
Ahead of the release, the USD is strengthening against all major rivals, but not because of the US economic performance, but because fears took over financial markets after the US and Iran launched a massive air strike on Iran last Saturday. Tehran retaliated, hitting US bases in different Gulf countries such as Dubai, Qatar, and Saudi Arabia. As of today, the conflict continues to spread across the entire Persian Gulf.
The latest on the matter indicates that shipments through the Strait of Hormuz have halted, further fueling price disruptions: Oil and gas prices are skyrocketing around the globe, while demand for safety is pushing the US Dollar Index (DXY) up, roughly 1.7% higher since the week started.
In such a scenario, the US employment situation will likely be set aside as investors will be focused on war developments when looking for market direction. Nevertheless, every piece of data will be considered in the mid-term leading up to the next Fed monetary policy meeting scheduled for March 17-18. At the moment, the odds of an interest rate cut are quite low, particularly given stubborn inflationary pressures. The latest Personal Consumption Expenditures (PCE) Price Index, the Fed’s favorite inflation gauge, came in at 2.9% YoY in December, while the core annual PCE hit 3%.
The February ADP report is expected to confirm that the labor market left behind the slow momentum from mid-2025 and is now much more stable. A stronger-than-anticipated report is likely to reinforce the positive view of the labor market, yet have no real impact on upcoming Fed monetary policy decisions. A weak report, on the other hand, can temporarily interrupt the USD rally, but as long as the war continues, demand for safety is likely to prevail
When will the ADP Report be released, and how could it affect the USD?
The US ADP Employment Change report will be out on Wednesday at 13:15 GMT, and it is expected to show that the private sector added 50K new jobs in February. As previously mentioned, the DXY is sharply up ahead of the announcement amid the Middle East crisis, boosting demand for safety.
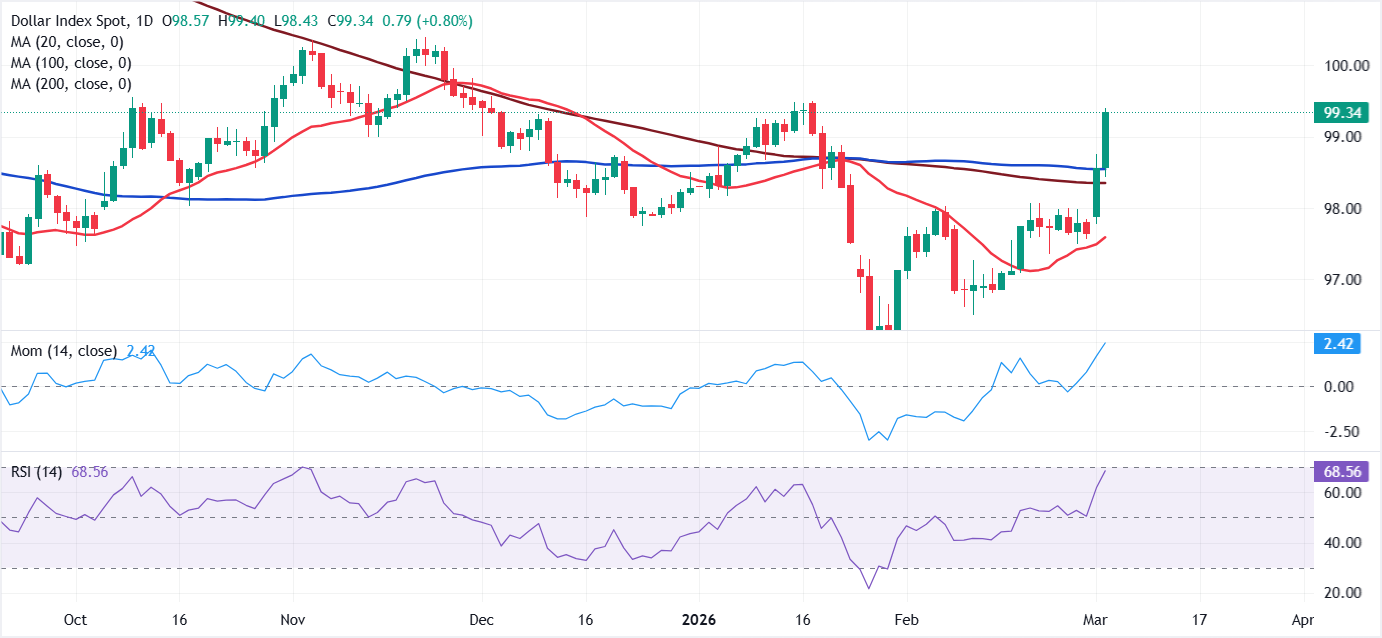
Valeria Bednarik, Chief Analyst at FXStreet, notes: “Demand for the USD pushed the DXY to its highest since mid-January, when the index topped at 99.50. The bullish trend is clear on the daily chart, as the DXY has run beyond its 100-day and 200-day Simple Moving Averages (SMAs), both directionless and converging at the 98.40-98.60 price zone. The same chart shows technical indicators head firmly north, well into positive territory, without signs of upward exhaustion.”
Bednarik adds: “Beyond the aforementioned yearly high at 99.50, the index is likely to extend its run towards the 100.00 mark. Additional gains seem unlikely with just the ADP report, but steady gains above 100.00 should lead to a long-lasting USD bullish trend. Support comes at the 90.00 level, with approaches to the latest likely to attract buyers. An unlikely break below it should expose the mentioned 98.50 area, where the next line of buyers will appear.”
Employment FAQs
Labor market conditions are a key element to assess the health of an economy and thus a key driver for currency valuation. High employment, or low unemployment, has positive implications for consumer spending and thus economic growth, boosting the value of the local currency. Moreover, a very tight labor market – a situation in which there is a shortage of workers to fill open positions – can also have implications on inflation levels and thus monetary policy as low labor supply and high demand leads to higher wages.
The pace at which salaries are growing in an economy is key for policymakers. High wage growth means that households have more money to spend, usually leading to price increases in consumer goods. In contrast to more volatile sources of inflation such as energy prices, wage growth is seen as a key component of underlying and persisting inflation as salary increases are unlikely to be undone. Central banks around the world pay close attention to wage growth data when deciding on monetary policy.
The weight that each central bank assigns to labor market conditions depends on its objectives. Some central banks explicitly have mandates related to the labor market beyond controlling inflation levels. The US Federal Reserve (Fed), for example, has the dual mandate of promoting maximum employment and stable prices. Meanwhile, the European Central Bank’s (ECB) sole mandate is to keep inflation under control. Still, and despite whatever mandates they have, labor market conditions are an important factor for policymakers given its significance as a gauge of the health of the economy and their direct relationship to inflation.
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.