Indian Rupee hits fresh two-month low amid surging US Treasury yields
- The Indian Rupee falls to a fresh two-month low against the US Dollar amid surging US Treasury yields.
- Fed’s Kashkari expects one more interest rate hike this year and another in 2027.
- Strong US ADP Employment Change data has set a strong stage for the US NFP.
The Indian Rupee (INR) extends its weakness against the US Dollar (USD) on Thursday after a weak opening. The Indian currency faces selling pressure as United States (US) Treasury yields extend their rally, supporting the USD/INR pair to move higher to near 96.32, the highest level seen in two months.
During the day, the 10-year US Treasury yield is close to 5.31%, the highest level seen in near two decades.
Higher yields on US bond yields diminish the appeal of riskier assets, such as the Indian Rupee.
US Treasury yields extend rally as Fed continues to warn of persistent inflation risks
Yields on US bonds have rallied further as Federal Reserve (Fed) officials continue to warn of persistent inflation risks due to energy supply shocks.
Federal Reserve Bank of Minneapolis Neel Kashkari delivered a notably hawkish-leaning message, with the FXS Speechtracker score at 7.1 versus a 6.2 historical average, underscoring concerns that inflation near 3% remains too high and that resilient growth may signal policy is less tight than assumed. The emphasis on a potentially higher and elevated neutral rate, combined with guidance for one more hike this year and another in 2027, reinforces a narrative of prolonged restrictive policy that is broadly supportive of the US Dollar even as Kashkari still hopes to tame inflation with only modest action.
The FXS Fed Sentiment Index slipped by 0.42 points to 143.28, indicating a slight moderation in perceived hawkishness despite the strong tone of the speech. With the index firmly above the 100 neutral line, the Fed remains in clearly hawkish territory, and the small pullback suggests markets are adjusting expectations at the margin rather than fundamentally reassessing the policy stance highlighted by the FXS Speechtracker.
Fed policymakers remain concerned about energy supply shocks due to receded fears of US-Iran diplomacy since US President Donald Trump denied reports from Axios claiming Iran sanctions relief.
US NFP data in focus
The next major trigger for the US Dollar is the Nonfarm Payrolls (NFP) data for September, which will be published on Friday. Investors will closely track the US NFP data as it is expected to influence market expectations for the Fed’s monetary policy outlook.
Currently, the CME FedWatch tool shows a 62.4% chance that the Fed will leave interest rates unchanged at the policy meeting this month. The possibility of the Fed maintaining the status quo in October has improved from the 29% seen a week before.
Meanwhile, strong ADP Employment Change figures have set a positive tone for the official employment data. The data showed on Wednesday that the private sector created 90K fresh jobs, higher than the 70K estimate and the August reading of 36K.
Later in the day, investors will focus on the US ISM Manufacturing Purchasing Managers’ Index (PMI) data for September. The Manufacturing PMI is expected to arrive at 55.0, higher than 54.6 in August.
India rate path seen higher as Standard Chartered flags sticky inflation risks
Next week, the major trigger for the Indian Rupee will be the Reserve Bank of India's (RBI) monetary policy announcement on Wednesday.
Analysts at Standard Chartered expect India’s Monetary Policy Committee to begin tightening in October, projecting that the MPC will "hike the repo rate by 25bps to 5.50% in a unanimous vote at its 7 October announcement, followed by another 25bps increase in December." The bank notes that "September CPI inflation is likely to print at 5.7% y/y and rise to above 6% by the December MPC meeting," arguing that, with inflation mandated to remain within a "2-6% band" and a "medium-term target of 4%," "waiting until inflation exceeds 6% to deliver the first hike could create the perception that the MPC is falling behind the curve." Beyond its baseline view of "50bps of hikes by December," Standard Chartered also cautions that it "see[s] a risk of a further 25-50bps increase in the repo rate if inflationary pressures prove stickier than expected."
USD/INR Technical Analysis
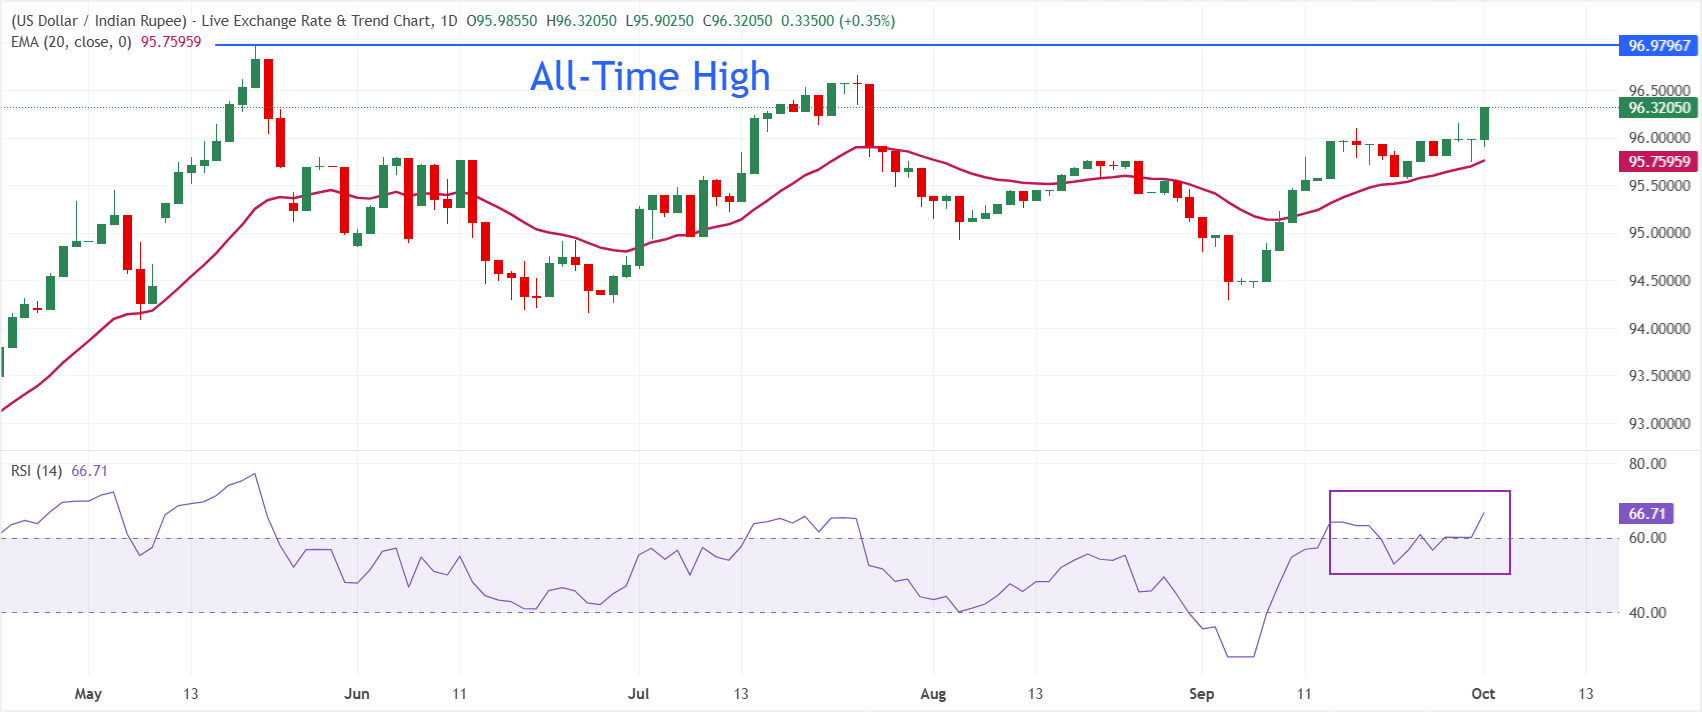
USD/INR trades at 96.32 at the time of writting, retaining a bullish near-term bias as it holds above the 20-day Exponential Moving Average (EMA) at 95.76. The pair remains supported by this short-term trend indicator, while the Relative Strength Index (RSI) at 66 on the daily chart stays in positive territory without yet signaling overbought conditions, hinting that upside pressure could persist while the price respects this underlying support.
On the downside, the immediate technical floor is located at the 20-day EMA at 95.76, where dip-buying interest could emerge if the pair retreats from current levels. Looking up, the all-time high near 97.00 is the key hurdle.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.