Week Ahead on Wall Street (SPY) (QQQ): Netflix finds sellers but no subscribers, yields hit equity indicies
- Equity markets remain directionless as earnings season ramps up.
- Bond yields rise again, hitting equity sentiment.
- Next week is when earnings season really kicks off.
Another directionless week for equities as some initial enthusiasm was knocked on the head from firstly Netflix (NFLX) and then rising bond yields. Netflix found plenty of willing sellers but not too many willing subscribers. The stock did a Facebook and plummeted in a huge market cap fall. This marks the second quarter in a row that Netflix has managed such a collapse so investors are now growing increasingly nervous that the same fate awaits Facebook Meta (FB) next week. Tesla (TSLA) did manage to turn things around briefly on Thursday as it unveiled a strong set of results. Deliveries remained strong despite shutdowns in Giga Shanghai but many investors, including your author, were still surprised just how strong earnings were. Demand was never an issue for Tesla but supply so far is not holding it back. Demand in fact is so strong it is leading to inventories falling to just a few days for Tesla.
But taking a step back and looking at the broader picture it was once again the bond vigilantes that did the damage on Thursday. Tesla lost 3% from the open as equities turned lower on some more hawkish commentary from central bankers. Not too surprising you would think but bond markets still pushed the US 10-year close to 3% again and Nasdaq investors took fright and headed for the hills. Everyone appears to be sharing the below chart showing the long-term breakout for the 10-year yield so we may as well add it in but apologies if you are tired of seeing this one already.
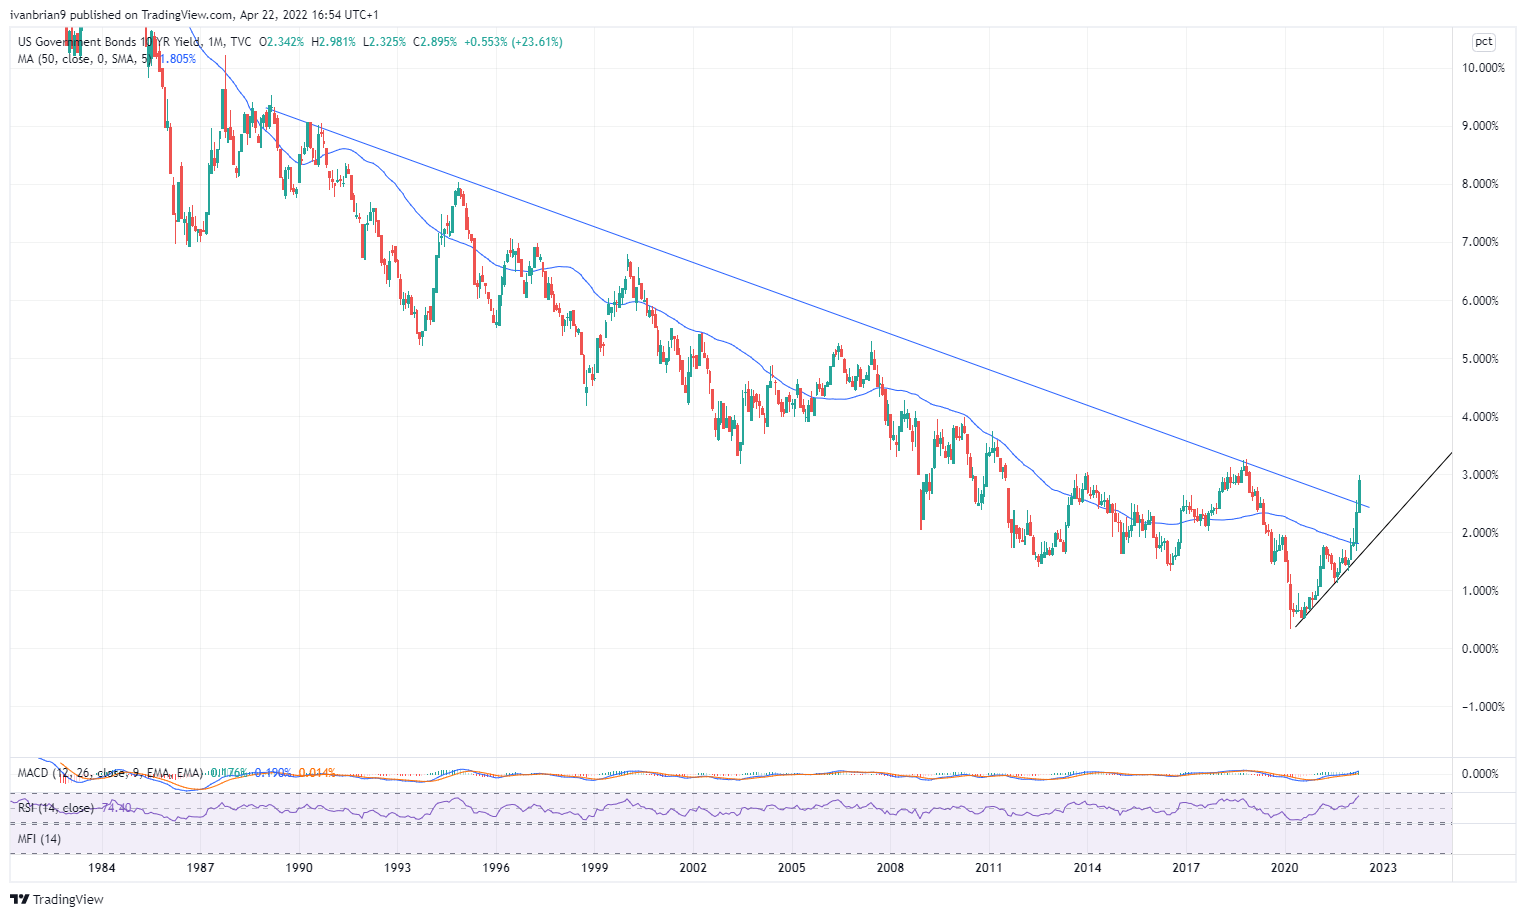
US 10 Year yield, monthly
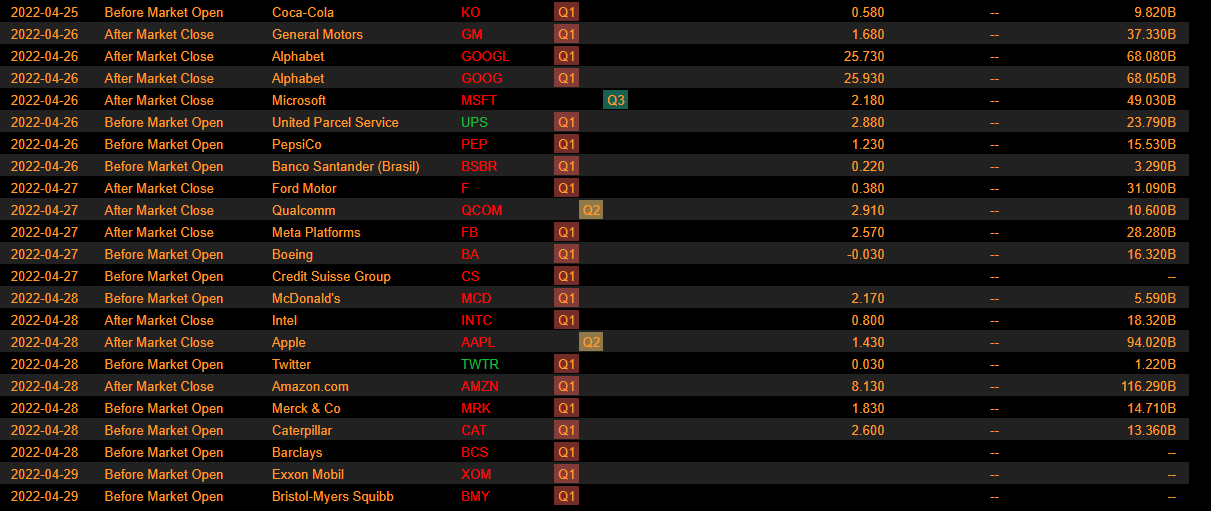
So back to earnings then, the main driver of stock markets in the short to medium term. Macro factors are the key longer-term determinant as they directly affect earnings but in the short term, earnings will have the key influence. Next week is set to be the big one with big tech up. We have Google, Microsoft, and Facebook. Only Apple and Amazon miss out. Once through those, we will have a clearer outlook on the path for the S&P and other indices for the quarter ahead. So far so good in terms of earnings with 77 companies in the S&P 500 reporting and 77% have beaten earnings estimates.
Sentiment Indicators
Again nothing too dramatic here showing the choppy and range-bound market we are in.
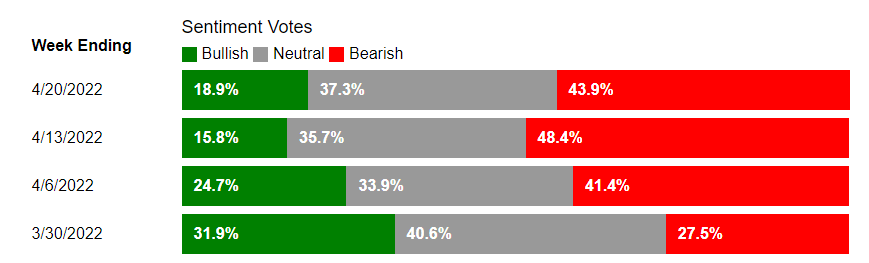
Source: AAII.com
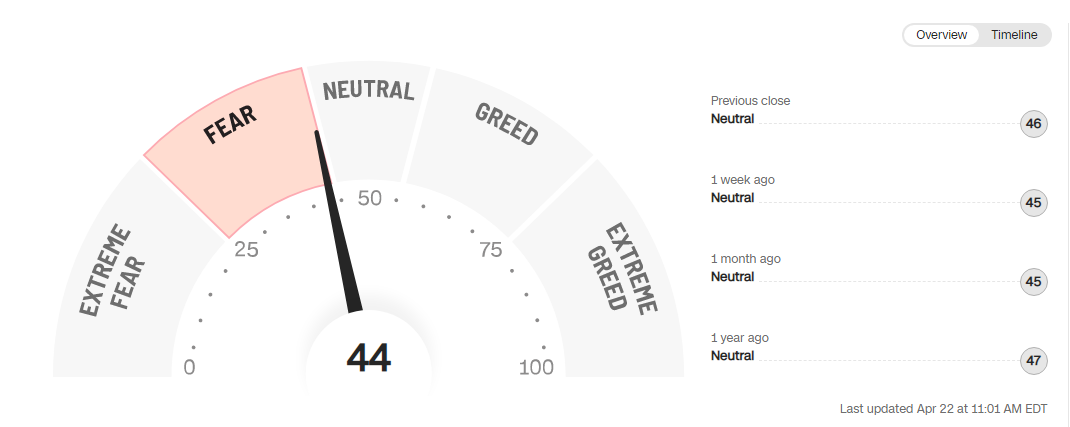
Source: CNN.com
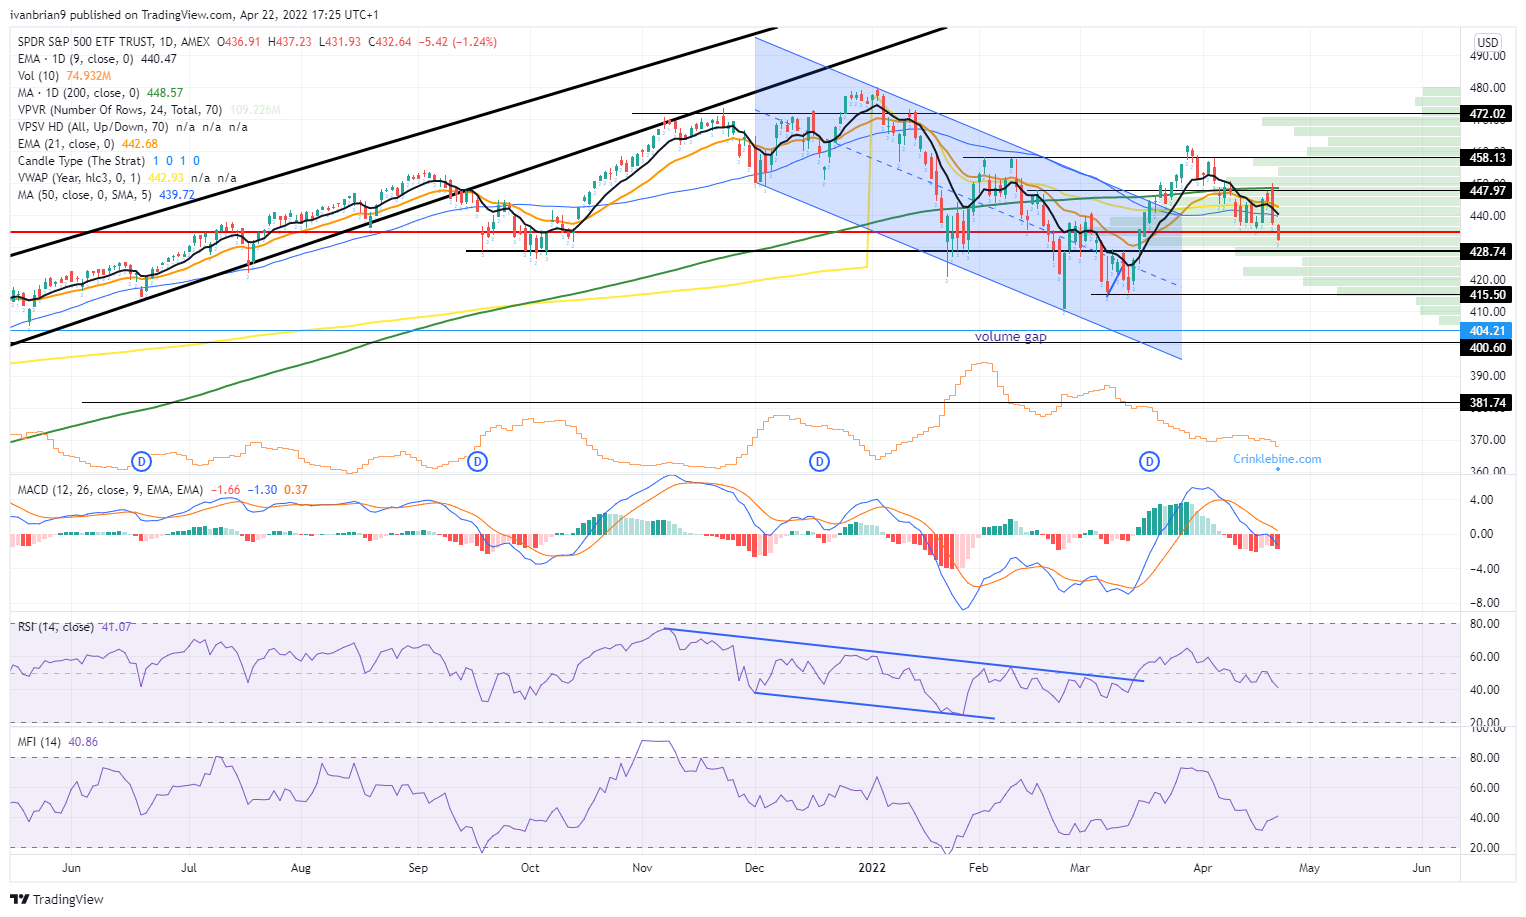
SPY technical analysis
Ok I know this is repetition but here too we are range-bound. $415 was the bullish double bottom that set up the contract rally, that, and some stretched positioning (everyone was short basically!). Now positioning is more neutral and the rally has played out. Since then stocks have found it hard to make significant gains as those bond market vigilantes just keep pushing rates higher. $428 is the next support to test and a break of that will bring us to $415 again. Third time may not be a charm. RSI and MFI also remain neutral and rangebound.
Earnings week ahead
Source: Benzinga Pro
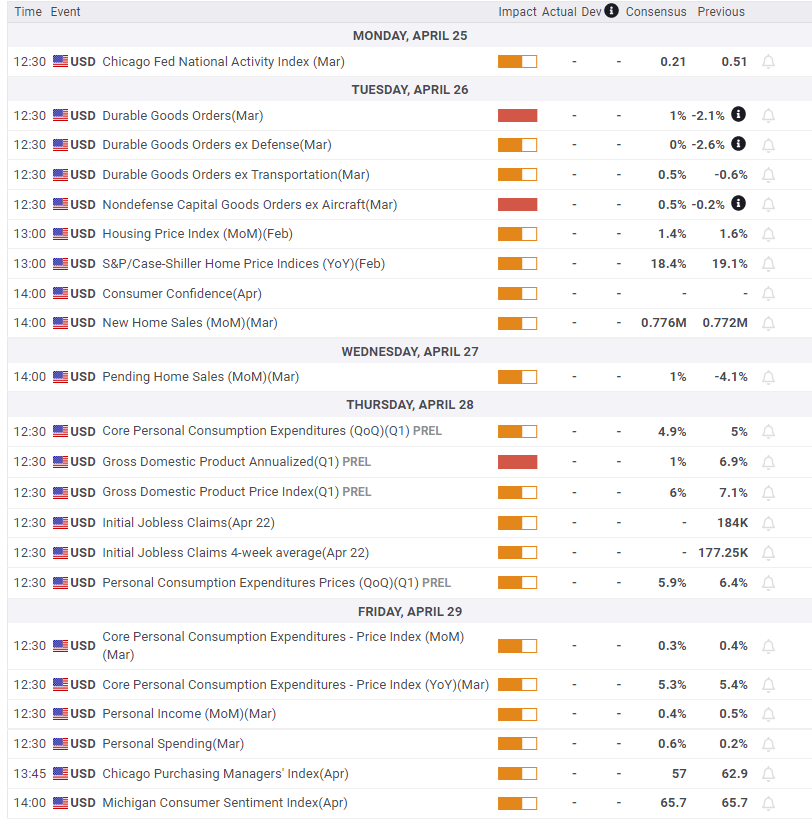
Economic releases
US GDP on Thursday and Chicago PMI on Friday are the highlights for the week.
The author is short Tesla
Author

Ivan Brian
FXStreet
Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.