Week Ahead on Wall Street (SPX QQQ): Can earnings season turn the ship or are we heading for 100bips?
- S&P 500 (SPY) (SPX) stages a massive rally on Thursday despite CPI shock.
- Nasdaq (NDX) (QQQ) also rallies over 5% on Thursday.
- Friday sees more heavy selling though as Thursday's rally looks more like options and short covering.
Yet another hectic week to put in the history books and it looks like more interesting times ahead. We now get really into the meat of earnings season and investors remain on edge after another roller-coaster few days. The week really revolved around the Bank of England and Thursdays hot hot hot CPI report. So hot it was a forty year high. Equities initially puked lower to the tune of about 3% but already things looked stretched as we opened for the regular session. Sure enough, everyone shorted the hole and there was no follow-through. This led to a massive rally which was added to with some super short-term options trading. The use of 1 or 2-day options contracts has been notable this year which has seen volatility rise as a result. This does not necessarily move to VIX which is a measure of 30-day volatility but causes some problems in an already thin liquidity profile.
Lottos are everything now...
— Markets & Mayhem (@Mayhem4Markets) October 15, 2022
More than 40% of $SPX option volume in Q3 has had less than 24 hours to expiration.
Imagine that! pic.twitter.com/Y4pFtRum39
That is part of the explanation for the massive turnaround Thursday and the rest was terrible sentiment and the market just went into the number plain short. We had mentioned in our edition last week that we say the potential for a rally based on positioning and not much has changed. But Friday we got back to normal as the larger players stepped up bearish bets based on a locked-in 75bps hike in November.
Weekly S&P500 ChartStorm - 16 October 2022, by @Callum_Thomas @topdowncharts https://t.co/vLbJeBKyep
— John Lounsbury (@jlounsbury59) October 16, 2022
Favorite chart this week (out of 11): High short interest explains why there are explosive up days due to short-covering. pic.twitter.com/vsDhNrGIHr
Equity positioning is very bearish again, with Nasdaq shorts at extreme levels.. This could be the reason for the current rebound, but equities seem fundamentally offered still
— AndreasStenoLarsen (@AndreasSteno) October 15, 2022
4/n pic.twitter.com/9yfGvNDHOr
A lot of hedge funds went *very* short on Friday. pic.twitter.com/Z06sIppsib
— Markets & Mayhem (@Mayhem4Markets) October 16, 2022
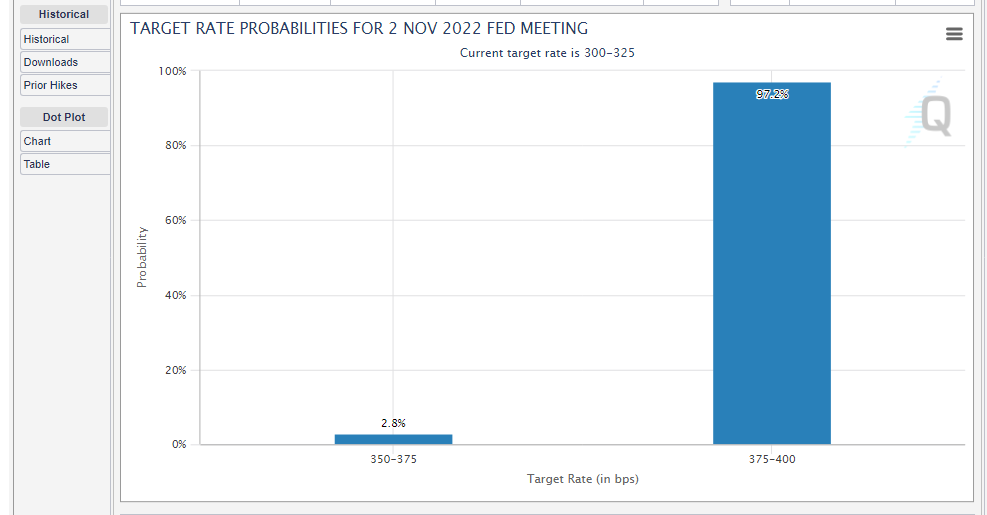
Source: CMEgroup.com
Interesting to note is the total lack of a 100bps rate hike being considered by markets. We feel that may change as the week progresses. Already we have seen some hawkish comments for December from Fed member Bullard but I feel this will lead to more talk of 100bps coming into the conversation next week. That will keep things interesting for equities. Well for everything!
100bps is on for next week https://t.co/Lcc2TLAeJV
— Ivan Brian (@IvanBrian9) October 16, 2022
So in my view, we are getting further from a Fed pivot, not closer. In any event, a pivot is not a good thing. As I have been saying the Fed will pivot when things are bad, very bad. Check out below for how that looks for equities. As expected not good.
What happens to Stock Prices when the Fed Pivots?
— Nick Gerli (@nickgerli1) October 11, 2022
Historically - they crash by even more.
Over the last 6 Major Recessions, Stocks Crashed an average of 28% AFTER the Fed did 1st Rate Cut.
Taking another 14 Months to get to the "Bottom". pic.twitter.com/raiUpZ9OD6
All that brings us to earnings season. So far so good in my view. We have got most of the bad news out of the way. Analysts have been busy marking down estimates allowing companies to match or beat. Also, FedEx and Nike got a lot of bad news out of the way and expectations are low. The banks last week did reasonably well even if the stock prices did not and Pepsi and Dominos showed consumers will still spend. Now we move into a big week. I tend to agree with the below estimate. Things will get bad but it may take a while. Bad news is in a lot of stock prices ahead of earnings.
Been commenting that companies are in the inflationary expansion sweetspot right now. Top line surging, margins expanding (wages arent keeping up) and household have enough excess cash to keep spending. q3 is likely to be fine. same with q4 now.
— Bob Elliott (@BobEUnlimited) October 16, 2022
Only creates more pain ahead.
This is also how Pepsi (PEP) looked last week.
If that proves correct it will mean more rate hikes for the Fed. We are in a 70's style inflationary environment spurred by an energy crisis (1970s) and a pandemic. Inflation is a tide that initially rises all boats before they eventually start taking on water. The first to go is the housing market as rates are raised aggressively. We are already seeing evidence of this. Earnings may take a little bit longer but they will get there. Already Pepsi and Dominos have shown us that in this initial phase consumers will tolerate higher prices on lower-cost items. Big ticket is not so good and the big box retailers alluded to consumers switching to lower-priced items in the last quarter.
Earnings season
A big week ahead which may help things to bottom for now.
#earnings for the week https://t.co/lObOE0uRjZ $TSLA $BAC $NFLX $SCHW $GS $JNJ $BK $T $UAL $VZ $LMT $SNAP $AAL $GNTY $SI $NOK $NUE $ASML $PG $IBM $HAS $AXP $ALLY $ACI $ABT $ISRG $BKR $BX $LRCX $FCX $NDAQ $AA $SLB $DOW $MRTN $STT $SBNY $JBHT $PLD $TRV $MNSB $ERIC $PM $ALK pic.twitter.com/qNhbscvAmE
— Earnings Whispers (@eWhispers) October 15, 2022
If we do manage to get a short-term bottom that brings us neatly into the mid-term elections. The S&P track record after midterms is pretty good so is 2022 the exception?
Exception that proves the rule 2022?? $SPX https://t.co/w92ftuKZZa
— Ivan Brian (@IvanBrian9) October 16, 2022
However just because we are down a lot does not mean there is not more pain to come. For every buyer there has to be a matching seller!
Looks good for next year though! https://t.co/ZNtFQATjQY
— Ivan Brian (@IvanBrian9) October 16, 2022
SPY technical forecast
That big Fibonacci retracement level at $351 is holding for now. A strong level and a break would lead to a move to $338, the pre-pandemic high (see weekly chart). If we can hold $352 then earnings season could be the catalyst for a move to $373 which remains my pivot. Above here and we think about an extended move due to midterms and earnings. $389 is the first target. Further adding to the support theory is the stochastic RSI being overbought and the 200-week moving average at current levels. The RSI is not however confirming the stochastic which would make for a stronger argument.
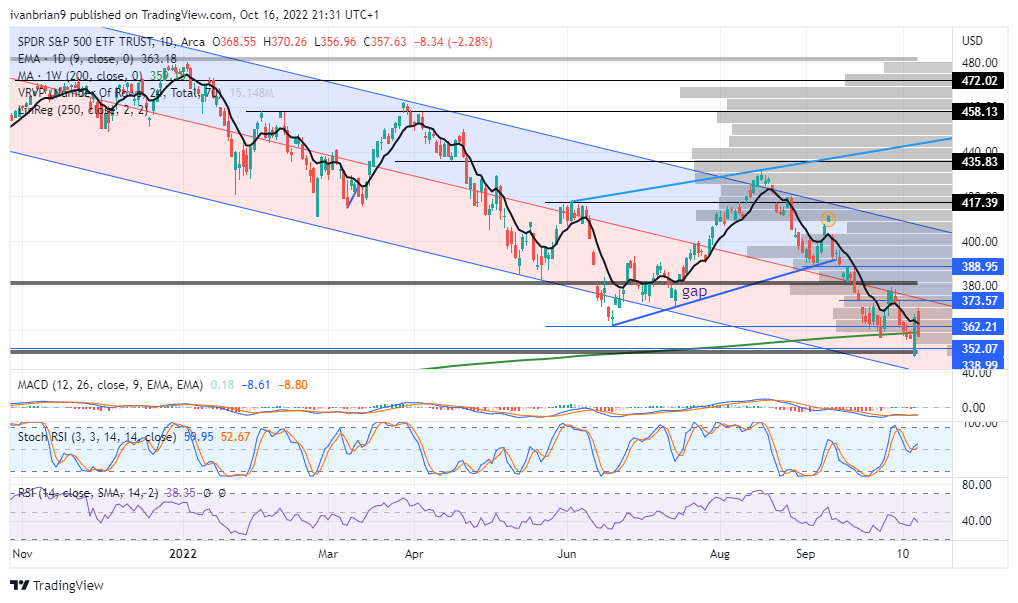
SPY daily
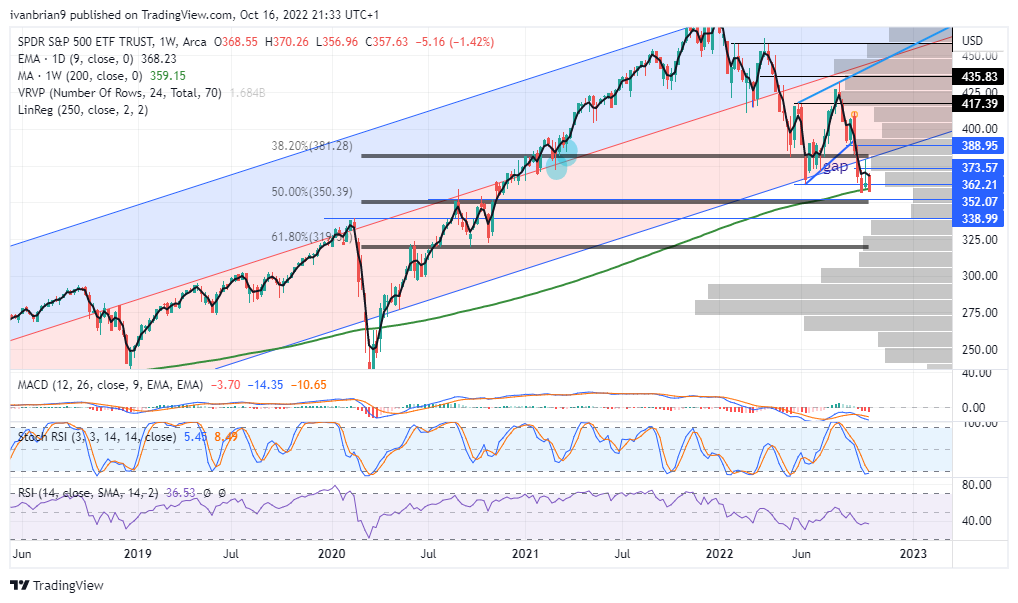
SPY weekly
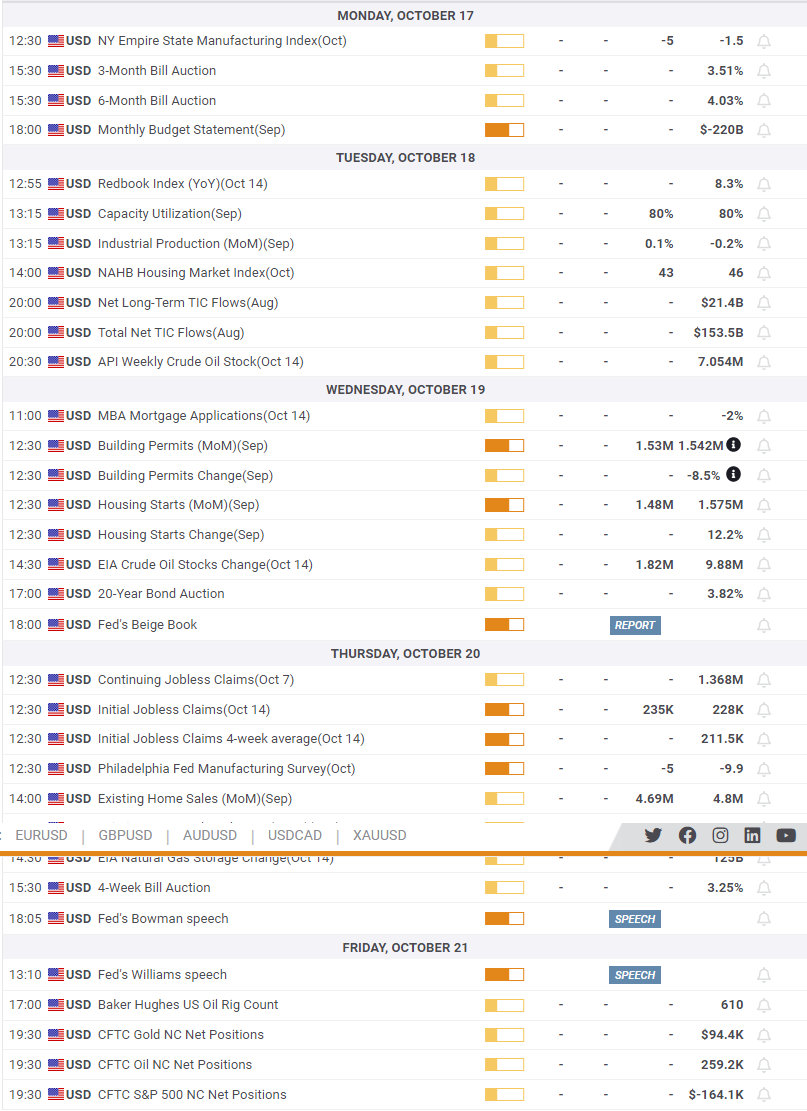
Economic releases
Author

Ivan Brian
FXStreet
Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.

















