US Non Farm payrolls: to confirm if the Fed does remain on hold in October


The jobs data for September is released on Friday, and the market is expecting a reading of 98k for last month, the unemployment rate is expected to remain steady at 4.1% and average hourly earnings are expected to edge up to a 3.2% annual rate.
In the lead up to this meeting, we have seen extreme volatility in the Treasury market, a mixed performance for stocks and a decline in expectations that the Federal Reserve will hike rates on consecutive meetings. After last month’s 25bp rate hike from the Fed, the prospect of a rate hike this month has dropped to just 24%, a week ago it was more than 70%.
Payrolls, a referendum on the next Fed meeting
The weaker core PCE report for August triggered the recalibration in October rate hike expectations, and Friday’s jobs report could be the final piece of the puzzle that will determine if the Fed does pause its mini hiking cycle. This jobs report is less a read on the state of the US labour market, and more of a referendum on whether the Fed should continue to raise interest rates.
Employers in wait and see mode
The labour market in recent weeks has generally been strong. ADP private sector payrolls were stronger than expected last month, and the Challenger, Gray and Christmas Inc report on job cuts reported a 20% decline in the number of jobs lost in the US last month compared to September 2025.
However, while companies are not letting go of workers, hiring was also subdued, suggesting that employers could be in wait and see mode on the back of high energy costs and Fed rate hikes that are eating into profits. AI still remains the top reason for employers to let go of staff this year, and we think that AI-linked layoffs may continue in the coming months, although they are not having a noticeable impact on the unemployment rate.
The Challenger jobs report suggests a steady labour market, and this is backed up by the latest initial jobless claim numbers, with 197,000 claims for US unemployment benefits reported last week, the lowest level since July.
Could payrolls surprise on the downside?
However, some analysts think that payrolls could surprise on the downside later on Friday because the 162k reading for August was down to seasonal factors that may have been erased last month.
Due to monthly revisions in the payrolls data, the focus could shift to the wage data. While the Fed could look through another month of hot jobs growth, if we get stronger signs of wage pressures building, this will be harder for the Fed to ignore.
The market impact
After last month’s stronger than expected payrolls report, the sovereign bond market sold off sharply, triggering weeks of bond price volatility, and the dollar rallied. The same could happen in October, if we get another hot reading. If we see payrolls rise by 130k + and wage growth rise by 0.4%, then we could see an October rate hike get repriced into the Fed Fund Futures market, and the 10-year Treasury yield push back towards 5.3%. It could also push USD/JPY back towards 160, the intervention zone, and it may start to weigh on US stock indices, with the S&P 500 and the Nasdaq finally selling off like the Russell 2000, as a rising discount rate neutralises the increase in earnings expectations.
A weaker reading could trigger a more nuanced market reaction. A September payroll number of 60k or below, and a rise in the unemployment rate could see Treasury yields fall sharply, which may weigh on the dollar and boost the US blue chip stock indices to fresh record highs. However, a sharp slowdown in job creation combined with an increase in the unemployment rate could raise concerns about the health of the US economy. This could send bond yields tumbling, but stocks may also follow suit, if it looks like the US economy could end the year on a weak note, and hurt future earnings growth.
Overall, today’s payrolls number is likely to seal the deal on the Fed’s decision at the October meeting. It will also have an impact on the direction of major asset prices as we start a new month.
S&P 500 remains close to all-time highs
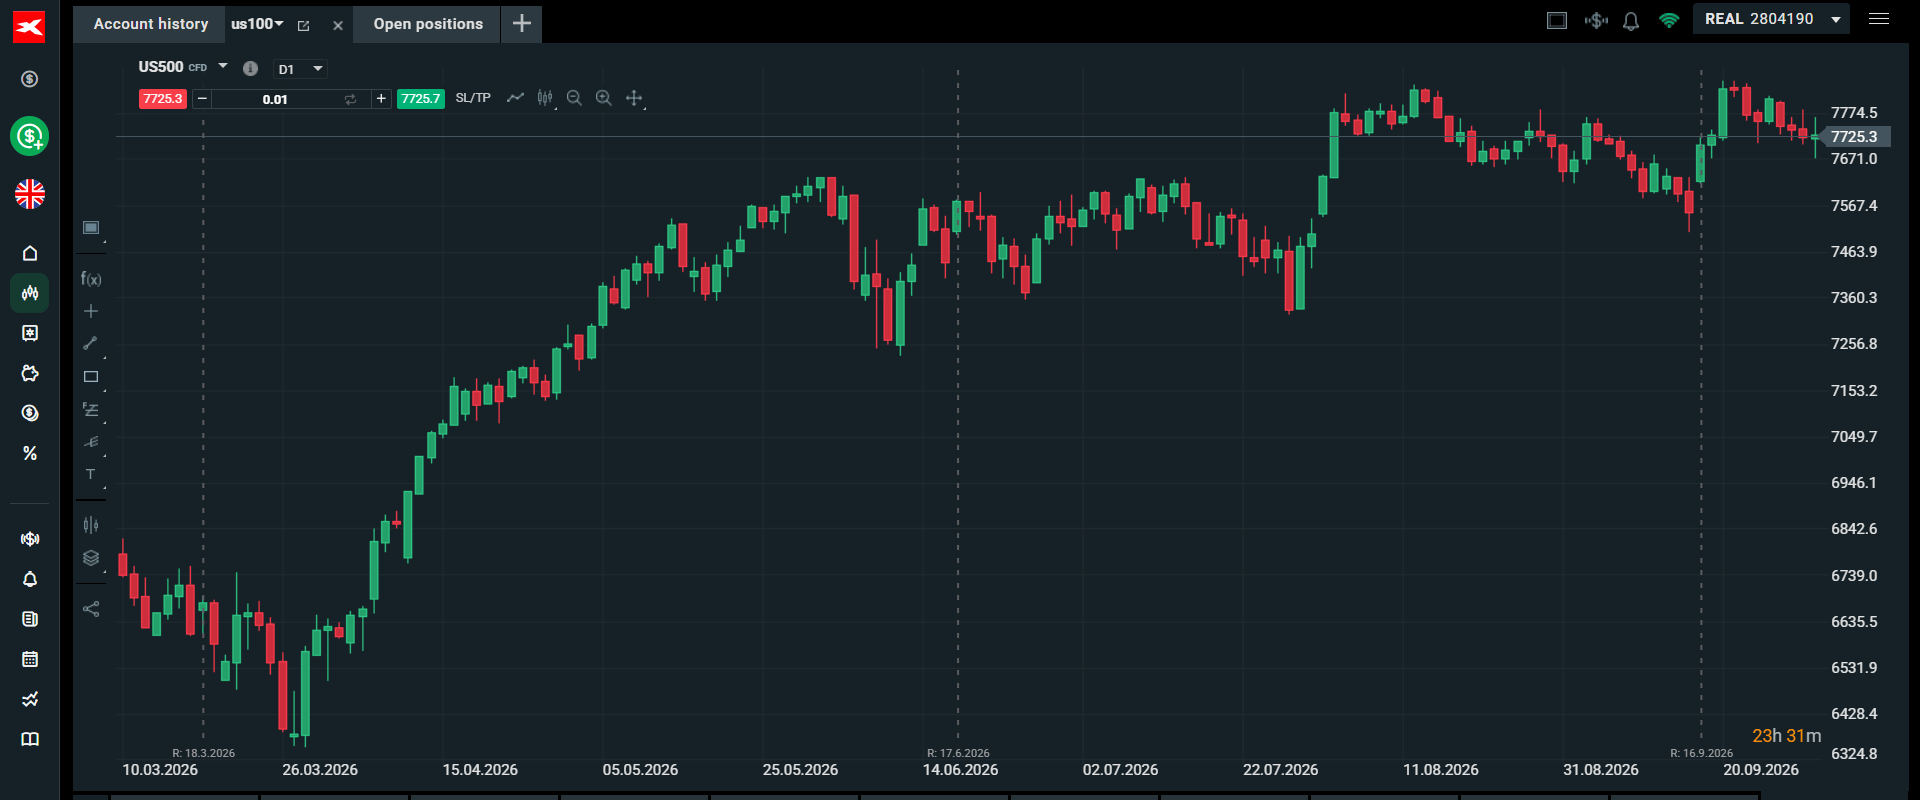
Source: XTB
USD/JPY, clawing back September’s losses
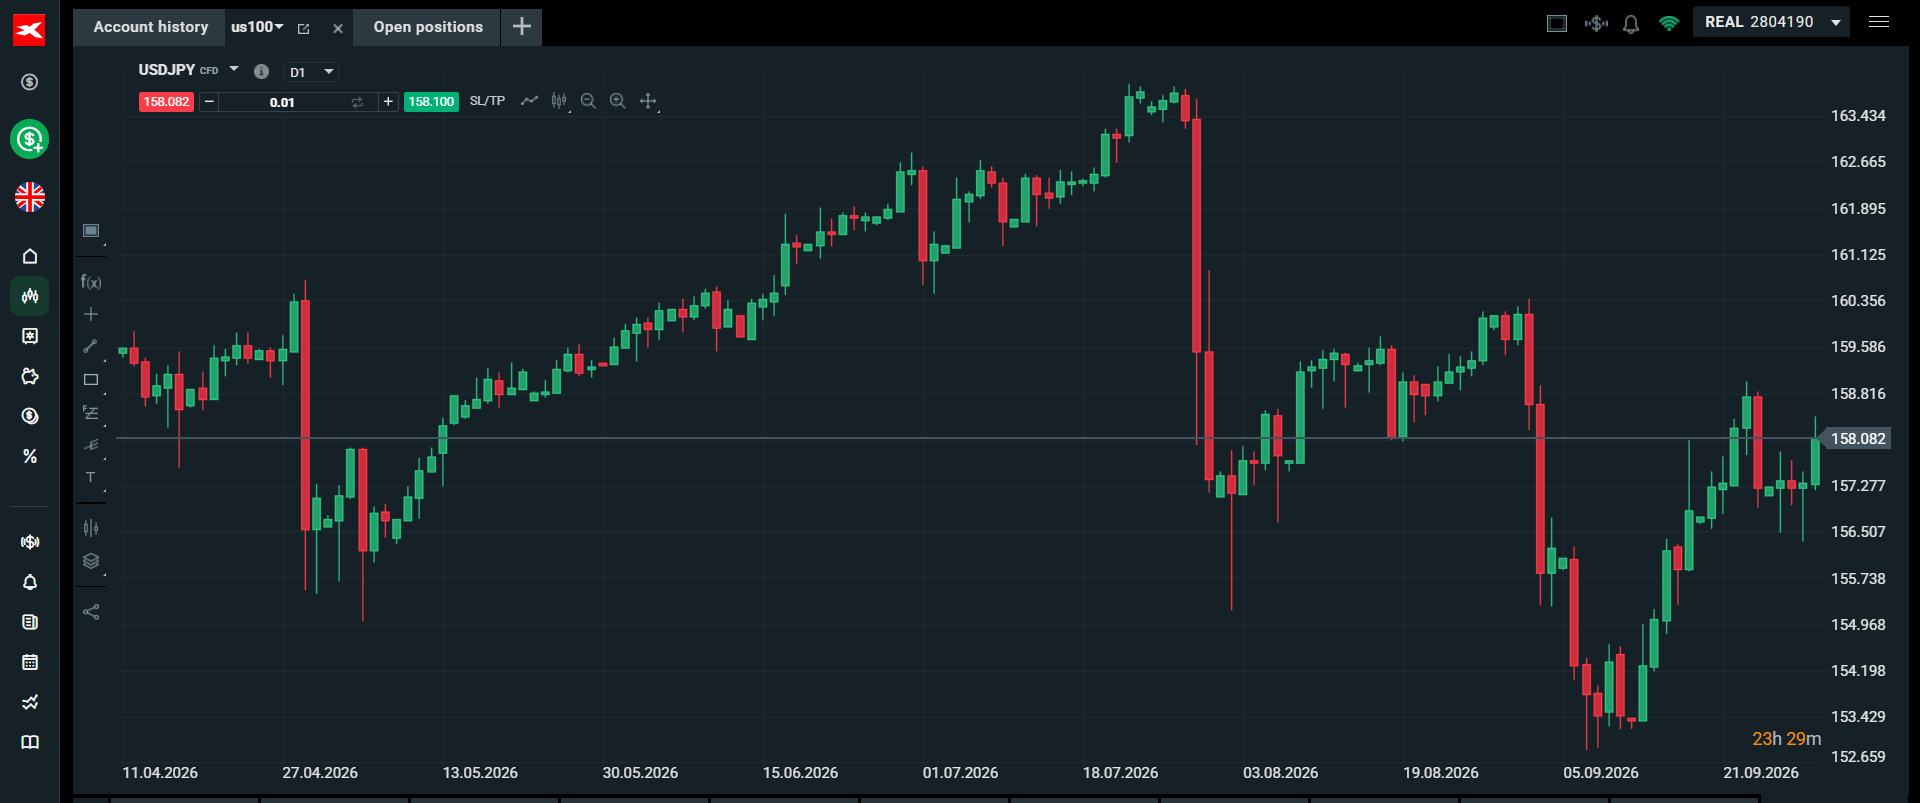
Source: XTB
Author
Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.

















