US Aluminium market will remain tight despite latest tariff changes
Washington's amended Section 232 aluminium tariffs
The Trump administration amended its Section 232 aluminium tariffs to encourage investment in domestic smelting. Companies that build, expand or refurbish US smelting capacity can apply to import qualifying volumes at a 25% tariff instead of the standard 50% rate, provided they meet approved investment milestones. The shift reflects the limited success of tariffs alone in reviving US primary aluminium production.
US remains structurally short of primary aluminium
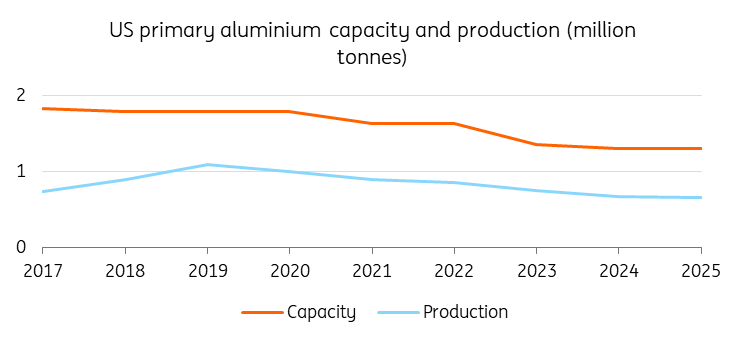
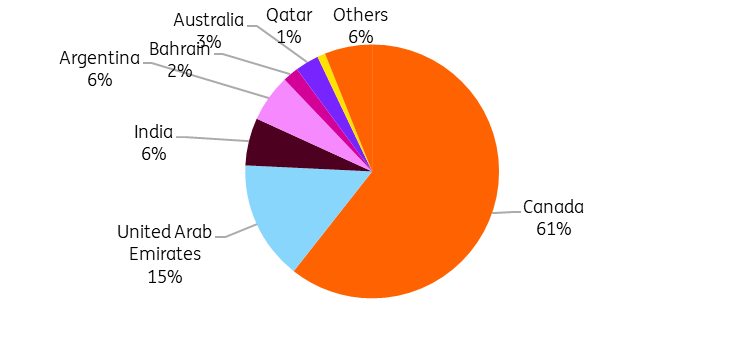
US primary aluminium output has steadily eroded despite years of tariff protection. The country is down to just four operating smelters, compared with more than 20 at the start of the century, leaving the US overwhelmingly dependent on imported metal. Canada remains the dominant supplier, while producers in the Middle East have become increasingly important in meeting US demand.
US primary aluminium production continues to decline
New supply will take years to arrive
Rebuilding US smelting capacity won’t happen quickly. At its core, primary aluminium production hinges on abundant, competitively priced electricity, not tariff protection. Levies may help the math on paper, but new smelters still demand billions in capital, long‑term power contracts, environmental approvals and years of construction before any fresh metal hits the market. That’s why the proposed 750ktpa EGA-Century Aluminum greenfield smelter in Oklahoma – the furthest along in the US pipeline – is unlikely to deliver meaningful domestic supply before 2030.
US demand remains heavily reliant on imports
Midwest premiums remain well supported
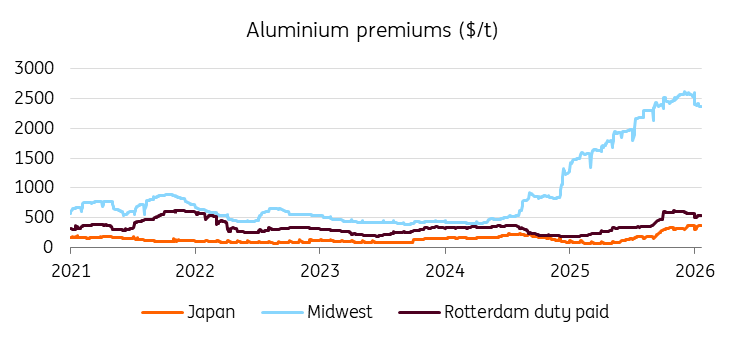
Recent disruptions in the Middle East increased pressure on an already tight US market by reducing global availability and increasing competition for alternative supply. However, elevated Midwest premiums primarily reflect the combination of high import tariffs, limited domestic production and continued reliance on overseas metal.
We expect the US Midwest premium to remain well-supported. While the new programme may improve the longer-term outlook for domestic production, it’s unlikely to materially reduce import dependence or procurement costs over the next several years.
US Midwest premium to remain elevated
Import dependence will persist
The latest changes are unlikely to materially alter the near-term US market. The reduced tariff applies only to qualifying volumes linked to approved investment plans, while meaningful additions to domestic smelting capacity remain years away. As a result, import dependence and elevated US delivery costs are likely to persist.
Ultimately, the programme should be viewed as a long-term industrial policy rather than a near-term solution to the country’s supply shortfall. If successful, it could support a gradual revival of US primary aluminium production. Until meaningful new capacity comes online, however, the US will remain structurally dependent on imports, keeping Midwest premiums well-supported.
Author

ING Global Economics Team
ING Economic and Financial Analysis
From Trump to trade, FX to Brexit, ING’s global economists have it covered. Go to ING.com/THINK to stay a step ahead.
















