The French debt crisis adds to pressure on the Euro
The yield on 10-year French government bonds has risen above 5%, its highest level since 2002. Political instability and difficulty reducing the budget deficit are increasing risks to the eurozone financial system and weighing on demand for the euro.
The ECB faces a difficult choice. Eurozone inflation reached 3.8% in September, with energy risks persisting amid the Iran conflict. Markets expect the ECB to leave rates unchanged at 2.65% at its next meeting but acknowledge the possibility of a rate hike in December. A more hawkish ECB stance could support the euro, although high borrowing costs pose a risk to growth.
Expectations of high US interest rates are supporting the dollar. Investors expect the Fed to leave rates unchanged at its 27–28 October meeting, although the likelihood of a December rate hike remains high. If inflation continues to accelerate, expectations of tighter monetary policy could further support the dollar.
France’s debt problems and the eurozone’s vulnerability to an energy shock are weighing on the euro. A possible ECB rate hike could ease this pressure, but in the short term, the Fed and ECB meetings, along with developments in the energy market, will remain the key factors.
Technical analysis
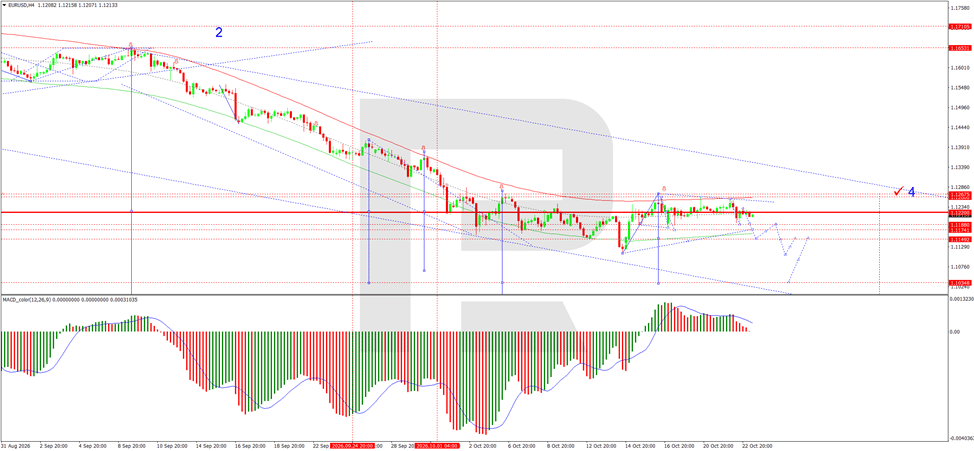
On the H4 chart, EUR/USD remains in a downtrend after completing an upward correction towards resistance at 1.1268. The market formed a local consolidation range at this level but failed to hold above the channel’s upper boundary. The current structure points to another downward move, with an initial target at 1.1188. A break below this support would open the way towards 1.1174 and then 1.1149. In the medium term, the main downward wave is likely to continue towards 1.1035. The MACD indicator supports this scenario: its signal line is above zero but pointing down, reflecting gradually weakening buying activity and creating the conditions for selling to resume.
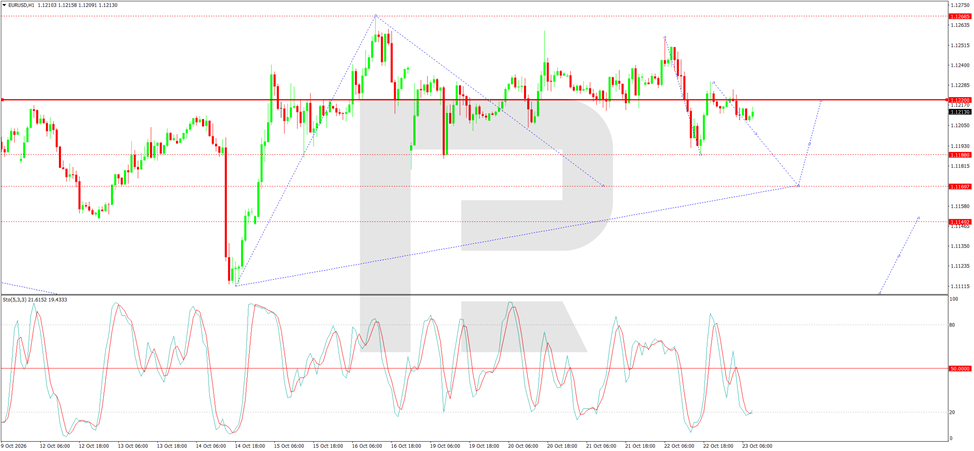
On the H1 chart, a local upward correction has been completed, after which the price returned to key resistance at 1.1220. A narrow consolidation range is currently forming around 1.1213. The priority scenario for the upcoming trading session remains a decline towards support at 1.1188, followed by a continuation of the move towards 1.1170. A close below this level would create the conditions for a downward wave towards 1.1149. An alternative scenario envisages a retest of resistance at 1.1220, but sustained growth would require consolidation above 1.1268. The Stochastic oscillator is near oversold territory, with its signal lines below 20, allowing for a short-term corrective rebound before the main decline resumes. At the same time, the lower-timeframe structure does not yet show signs of a sustained upward reversal. The main focus remains on successive breaks below the nearest support levels.
Conclusion
The euro remains under pressure as France’s debt crisis intensifies, with 10-year bond yields above 5% for the first time since 2002. Political instability and budget-deficit concerns are weighing on the eurozone’s financial stability and dampening demand for the single currency. The ECB faces a difficult balancing act between rising inflation and high borrowing costs, with markets expecting rates to hold at 2.65% but acknowledging a possible December rate hike. Meanwhile, expectations of tight Fed policy continue to support the dollar. Technically, EUR/USD remains bearish, with the next downside targets at 1.1188, 1.1174 and 1.1149, and a medium-term objective of 1.1035. A corrective rebound is possible given oversold conditions, but the broader structure remains bearish unless resistance at 1.1268 is decisively broken.
Author

RoboForex Analysis Department
RoboForex
RoboForex Analysis Department provides timely market insights, expert technical analysis, and actionable forecasts across forex, commodities, indices, and equities.

















