The ECB set to hike as SpaceX gets ready for take off
- SpaceX to dominate markets.
- What next for US stocks?
- Inflation may have peaked.
- ECB set to hike rates, but are they making a policy mistake?
Traders are digesting news that the flare up in tensions in the Middle East could be over, as the US says that it has completed strikes against Iran. Although the ceasefire remains fragile, the recent bout of hostility between the two sides did not impact the oil price. Brent crude jumped 1.8% late on Wednesday, but it has given back gains on Thursday and remains below $93 per barrel, which is the low end of its recent range.
As the oil price falls, this is helping stocks recover after a sharp sell off on Wednesday. The decline was in more than just the tech sector. Although tech slipped by more than 2% on Wednesday, there were also declines for healthcare, financials, consumer discretionary, materials stocks and utilities. The biggest decliners in the tech sector included Marvell, Arm, Qualcomm and Broadcom. Nvidia also slumped more than 3% on Wednesday. However, market sentiment has recovered, the FTSE 100 is higher today, and US index futures are also pointing to a strong open later today, as stocks get a boost from the world’s biggest ever IPO.
SpaceX to dominate markets
Today is lift off for the SpaceX IPO. Demand for the shares is reportedly high, and the excitement ahead of this listing suggests that it will be a success. SpaceX will start trading on the Nasdaq on Friday, and due to the mega valuation of the company, which is set to reach $1.7 trillion, investors may need to sell other tech names to make room for SpaceX in their portfolios. This could be one reason for the bout of volatility that we have seen in markets this week.
What next for US stocks?
After experiencing a strong performance in the first half of the year, similar to the strong first half performances in 2021, 2023 and 2024, the US index has broken with its seasonal pattern, and the risk is that it follows the pattern from 2022, when the index slumped for the second half of the year and posted an annual loss of 19%. The S&P 500 is still higher by 6% YTD, looking ahead, we need to see if the recent volatility is a rotation out of the tech sector and into other low beta sectors of the market, or if it is early warning signs of a more prolonged downturn.
Inflation may have peaked
On the macro front, there are some signs that US CPI might have peaked in May, and the June CPI figure could retreat from a 3-year high of 4.2%. This theory hinges on a stable oil price that remains below $100 per barrel. In recent weeks, the average price of gasoline in the US has fallen, along with the 10% decline in the oil price in the last 4-weeks. Partly this was down to the ceasefire, and partly because there are reports that tankers are traversing the Strait of Hormuz and are undetected because they have disabled their radars. Kuwait is also offering to sell crude into Asia for the first time since the onset of the war.
Donald Trump has also said that the US has helped to get 100mn barrels of oil out of the Gulf via the Strait of Hormuz. It’s hard to know how Iran will react to this news, but it suggests that the oil supply could be loosening and Middle East oil production is restarting. For now, this could keep a lid on oil prices, which is welcome news, especially for central bankers who are worried about upside risks to price growth from the conflict.
ECB set to hike rates, but are they making a policy mistake?
While the SpaceX IPO is likely to steal the limelight, along with the start of the World Cup, it is worth noting that the ECB is expected to hike interest rates later today, for the first time since 2023. We expect the ECB to hike today, but what they do next is up for debate. The market is expecting one further hike by year end, but we will be listening to Christine Lagarde closely to see if she pushes back on this narrative.
The problem for the ECB is that inflation is way above target at 3.2% YoY, but growth is rapidly slowing and contracted by 0.2% last quarter. The fear is that the ECB could make the same mistake as it did in 2011, when it hiked rates right before the sovereign debt crisis. Today’s hike could exacerbate the growth issues in the currency bloc, and that could weigh on the ECB’s credibility, something that Lagarde and co will want to avoid.
There is a growing chorus that this rate hike won’t bring down inflation, which is caused by an international energy supply crunch. Due to this, Lagarde may want to deliver as neutral a message as possible later today, and the bar is high for Lagarde to deliver a hawkish surprise.
European asset markets are moving on the back of global factors right now, but if Lagarde is seen as being less hawkish than expected, we could see European stocks outperform their US counterparts, yields fall and volatility in the euro, which dropped 2% in the past month vs. the USD. EUR/USD is managing to hold above the $1.15 level for now, but the technical signals suggest that there is little incentive to buy the euro. The seasonal picture also looks weak, EUR/USD appears to be tracking the pattern from 2021 and 2024, when the euro came under downward pressure for most of the second half of the year. With limited room for maneuver, we doubt that Christine Lagarde will shift the dial for the euro later today.
EUR/USD 3-month chart
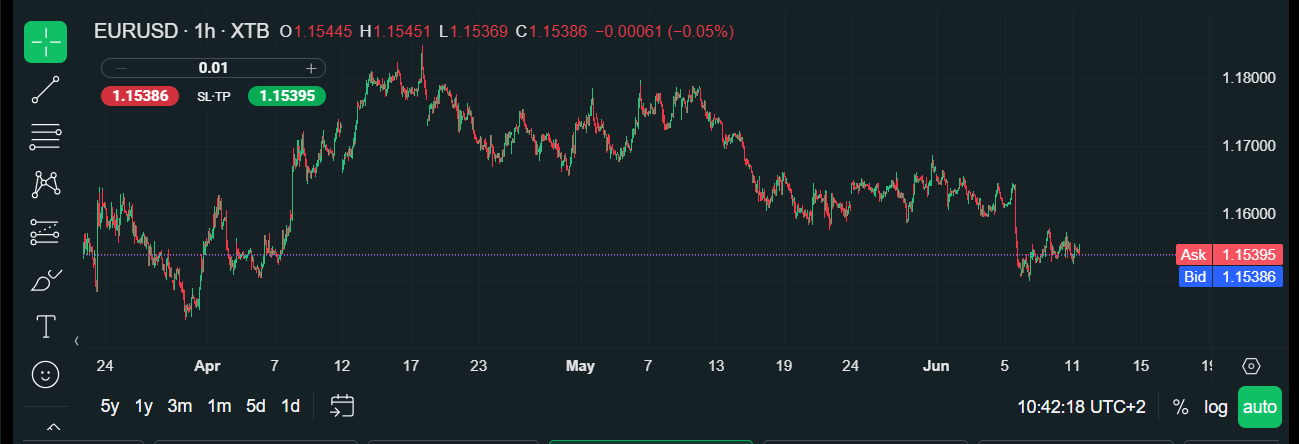
Source: XTB
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.

















