Still elusive rebound

S&P 500 obliged to the downside as reasonably fine NFPs brought back the justified bets on the Fed hiking yet again by 75bp in Nov, and by 50bp in Dec, which is in line with the Daly and Kashkari consistent utterances. That‘s right, as I told you on Tuesday in the article Fed Turn That Wasn‘t, Evans is still a lone dovish voice no matter the tightening cracks emerging overseas. After the opening bell, the selling pressure picked up, and kept delivering us, reasoned and patient traders, deserved open shorts profits.
That serves as key confirmation of the bears being firmly in the short-term driving seat, of markets not yet even thinking about positioning for Thursday‘s CPI data, which could bring about noticeable relief to both stocks and bonds – possibly in spite of core CPI, which I‘m looking for to come in really, really weak (meaning uncomfortably high) – that‘s an important distinction for future inflation path as e.g. core PCE excludes food and energy (both of which relented lately), and it would preclude the Fed‘s models from pausing the fight against inflation.
Sure, the lagging NFPs indicator brought in signs of internal job market deterioration – look at unemployment rate and participation – but the Fed would keep on tightening nonetheless. And that‘s what markets realized again Friday – long-dated yields are again surging as TLT is back at Sep lows. Hardly a conducive sign for stock market rally – I told you lately that Treasuries need to at least stabilize (if not turn noticeably up) as a precondition for the anticipated Q4 S&P 500 rally – the one that isn‘t here yet.
With the bond market closed today on Columbus Day, I‘m looking for less reliable trading performance interpretation when it comes to stocks, i.e. I wouldn‘t read too much into downswings and upswings intraday, and would try to view them in light of the dollar performance chiefly.
Today‘s analysis has been one of those extensive ones – keep enjoying the lively Twitter feed serving you all already in, which comes on top of getting the key daily analytics right into your mailbox. Plenty gets addressed there, but the analyses (whether short or long format, depending on market action) over email are the bedrock, so make sure you‘re signed up for the free newsletter and that you have Twitter notifications turned on so as not to miss any tweets or replies intraday.
Let‘s move right into the charts – today‘s full scale article features good 6 ones, and additional commentary on real assets in the opening section.
S&P 500 and Nasdaq outlook
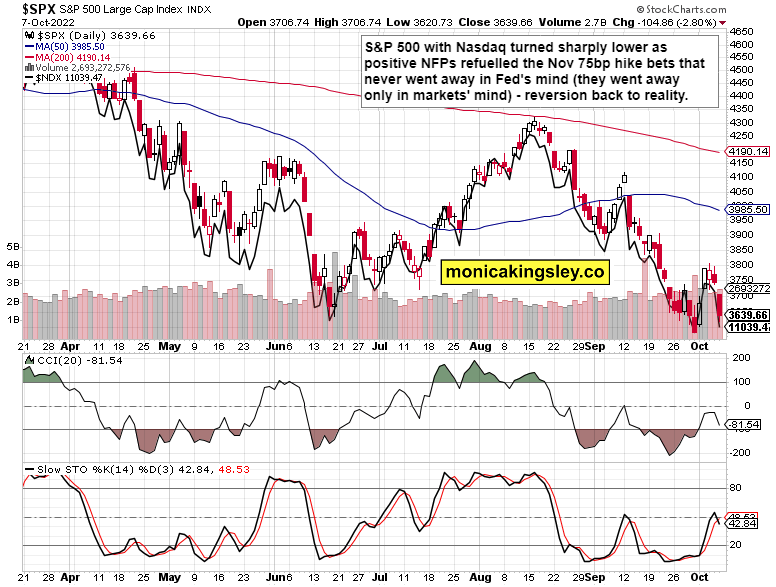
S&P 500 path of least resistance remains down – yet another rally attempt failed last week. Still, we haven‘t seen a true capitulation, and trading in the days preceding CPI would be telling as to the Q4 rally timing and its late Oct potential.
Credit markets
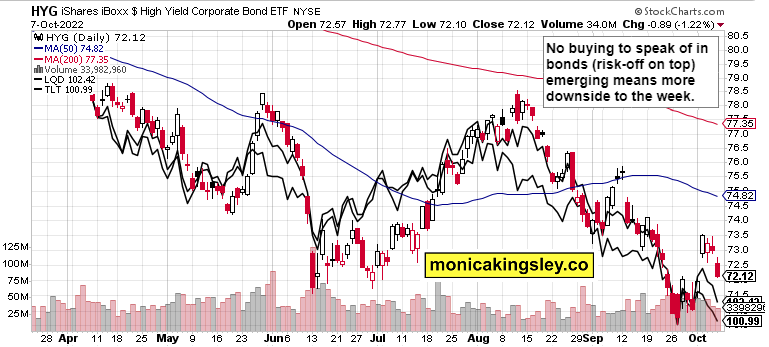
I‘m not yet drawing anyone‘s attention to the possible divergence in progress (HYG at much higher levels), because TLT hasn‘t yet found the bottom. Bonds are still risk-off, pointing bearish for stocks.
Author

Monica Kingsley
Monicakingsley
Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.

















