NFP pivotal to the direction of the Dollar

Macroeconomic snapshot
Federal Reserve’s (Fed), Federal Open Market Committee (FOMC)
The FOMC hiked interest rates by 0.25%, as expected. This is the highest level since 2001 and the Fed could raise rates again although the base case is to hold. The next meeting is on September 20th.
The interest rate situation is likely to lead to stabilised bond yields which may dissuade investors and may limit upward support on the value of the dollar.
Gross Domestic Product (GDP) growth rate
Over four years, GDP has been volatile with a low of 3.9% in Q4 ‘20 to a high of 7% in Q2 ‘21 but has been steady for the past six months. Q2 first estimate came in strong at 2.4% annualised expansion from 2.0% in Q1 2023 and beat expectations. The FOMC has a 2023 change in real GDP at 1.0% although Trading Economics are less optimistic with a Q3 2023 annualised growth forecast of 0.60%. The second estimate Q2 report is due on Thursday the 30th of August
GDP is anticipated to slow and see less investor confidence in US stocks which may limit downward pressure on the value of the dollar.
Consumer Price Index (CPI)
Over four years, CPI has been volatile with a low of 0.1% in May ‘20 to a high of 9.1% in June ‘22 but has been falling quickly for the past six months. June slowed to 3.0% annual inflation from 4.0% in May, slightly better than expectations. The FOMC has a 2023 PCE projection (PCE is not CPI) at 3.2% although Trading Economics are more optimistic with a Q3 2023 CPI forecast of 2.5%. The July report is due on Thursday the 10th of August.
CPI is anticipated to stabilise, leading to a less tight monetary policy and potentially support growth which may limit upward support the value of the dollar.
Labour
Over four years, unemployment has fallen from a high of 14.7% in Apr ‘20 to a low 3.4% in Apr ‘23 but has stabilised in the past six months. June fell to 3.6% unemployment from 3.7% in May as expected. The FOMC has a ‘23 unemployment rate projection at 4.1% although Trading Economics are more optimistic with a Q3 ‘23 forecast of 3.8%. The July report is due on Friday the 4th of August.
Unemployment is anticipated to climb slightly, potentially leading to reduced economic growth and US stocks which may limit downward pressure on the value of the dollar.
Russian invasion of Ukraine
The war is having a detrimental effect on the global and US economy by causing higher energy prices, higher food prices, higher inflation and is impacting economic growth. This is expected to limit the downward pressure on the dollar’s value.
China-US trade war
The trade war is having a detrimental effect on the global and US economy by causing higher prices for consumers, increased uncertainty for businesses, disrupted supply chains, job losses and is impacting economic growth. This is expected to limit the downward pressure on the dollar’s value.
DXY longer term (Four months)
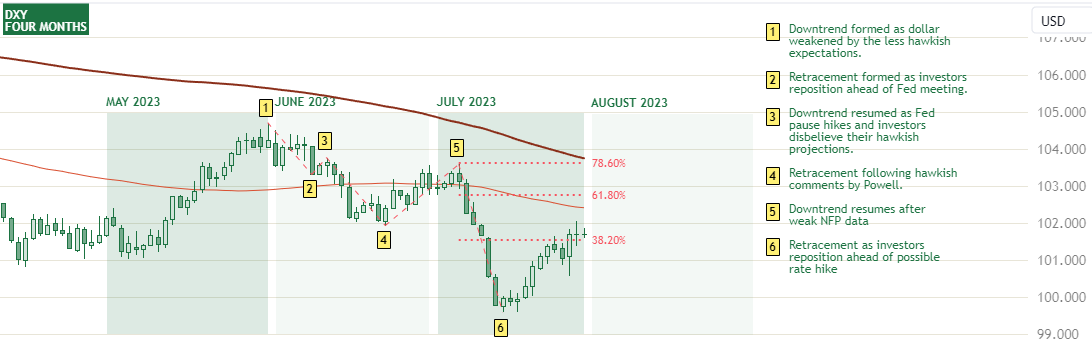
The US Dollar Index (DXY) has formed a downtrend since the start of June when investors began to price a lower peak interest rate which weakened the dollar. This dovish sentiment has been retraced three times as the Fed has not yet shown any signs that they will look to begin lowering rates in the near future. The DXY is currently retracing from the lows below 100.00 and testing the 38.20% fib. The downtrend will be broken on moves beyond the 78.60% level.
DXY (Four weeks)
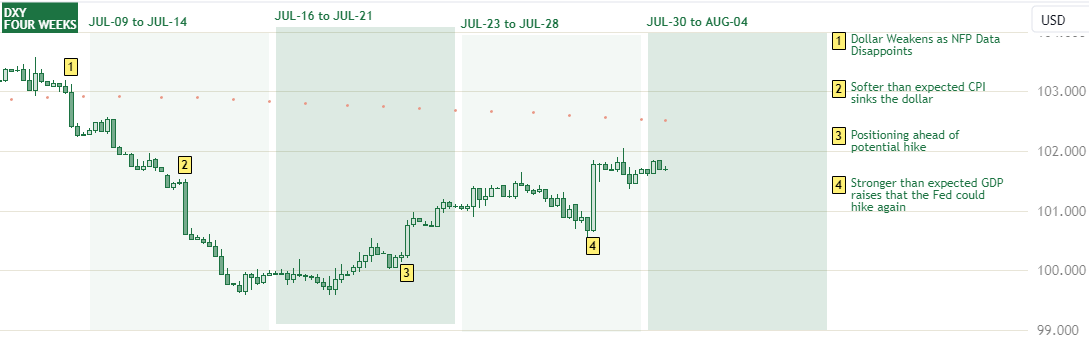
The US Dollar Index (DXY) has lost value over the previous three weeks, pressured by a cooling CPI although a stronger than expected economy raises the prospect of another hike.
Outlook
The events to keep an eye on:
Tuesday the 1st of August
- JOLTS Job Openings improvement to 9.6M exp. from 9.8M prev.
Wednesday the 2nd of August
- ADP Non-Farm Employment Change Big fall to 195K exp. from 497K prev.
Friday the 4th of August
-
Average Hourly Earnings slight fall to 0.3% exp. from 0.4% prev.
-
Non Farm Payrolls fall to 200K exp. from 209K prev.
-
Unemployment Rate remain at 3.6% exp.
CME group 30-day Fed Fund futures
-
September: rising sentiment of a hold, 78% in favour, 22% for a 0.25 hike.
-
November: rising sentiment of a hold, 67% in favour, 30% for a 0.25 hike.
Six month bond yields
- Treasuries: slightly rising at 5.55% from 5.50% last week.
Long Term Value of the US Dollar to Stabilise: As the Federal Reserve appears to plan on keeping rates at a high level for a lengthy period, growth may be limited which could see investors move hold onto some dollar safe havens. The US Dollar Index (DXY) over the long term is expected to retain its four month downtrend and remain below the 103.5 retracement unless NFP significantly beats its forecast.
Short Term Value of the US Dollar to Stabilise: The stronger than expected GDP data supported the dollar higher as investors look to caution themselves against a potential further hike although that is not the base-case. The US Dollar Index (DXY) over the short term is expected to remain above 100.00 unless NFP comes in below its forecast.
Author

Gavin Pearson
Independent Analyst
Gavin Pearson of Jeepson Trading is a currencies speculator from the UK focused on the G7 economies and is a recognized member of the eToro Popular Investor Program as well as being a funded prop trader with The 5%ers.

















