GBP/USD Forecast: Bearish pressure builds up as geopolitical tensions escalate
- GBP/USD trades at a fresh monthly low below 1.3400 on Monday.
- The US Dollar benefits from escalating geopolitical tensions.
- The technical outlook suggests that there is more room on the downside.
After losing nearly 1% in the previous week, GBP/USD stays under bearish pressure on Monday and trades at its lowest level in a month below 1.3400. In case safe-haven flows continue to dominate the action in financial markets in the second half of the day, the pair could continue to stretch lower.
British Pound PRICE Today
The table below shows the percentage change of British Pound (GBP) against listed major currencies today. British Pound was the weakest against the Euro.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.08% | 0.16% | 0.83% | 0.24% | 0.77% | 1.00% | 0.12% | |
| EUR | 0.08% | 0.23% | 0.93% | 0.33% | 0.80% | 1.07% | 0.16% | |
| GBP | -0.16% | -0.23% | 0.77% | 0.13% | 0.58% | 0.86% | -0.06% | |
| JPY | -0.83% | -0.93% | -0.77% | -0.60% | -0.09% | 0.23% | -0.78% | |
| CAD | -0.24% | -0.33% | -0.13% | 0.60% | 0.57% | 0.75% | -0.16% | |
| AUD | -0.77% | -0.80% | -0.58% | 0.09% | -0.57% | 0.26% | -0.66% | |
| NZD | -1.00% | -1.07% | -0.86% | -0.23% | -0.75% | -0.26% | -0.91% | |
| CHF | -0.12% | -0.16% | 0.06% | 0.78% | 0.16% | 0.66% | 0.91% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the British Pound from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent GBP (base)/USD (quote).
The negative shift seen in risk sentiment helps the US Dollar (USD) outperform its rivals and weighs on GBP/USD on Monday. Market participants grow increasingly worried about a widening and deepening conflict in the Middle East following the United States' decision to strike three nuclear facilities in Iran over the weekend.
Meanwhile, the data from the UK showed that the business activity in the private sector expanded at an accelerating pace in June, with the S&P Global Composite Purchasing Managers Index (PMI) improving to 50.7 from 50.3 in May. This reading, however, failed to support Pound Sterling.
Later in the day, the US economic calendar will feature S&P Global PMI data for June. Markets expect the Manufacturing PMI to edge lower to 51 from 52 in May and see the Services PMI retreating to 52.9 from 53.7. In case either of these PMIs come in below 50, the USD could come under selling pressure. Nevertheless, the market reaction could remain short-lived in the current market environment, with investors staying focused on geopolitics. A further escalation in the Iran-Israel crisis could boost the USD and cause GBP/USD to extend its slide in the near term.
GBP/USD Technical Analysis
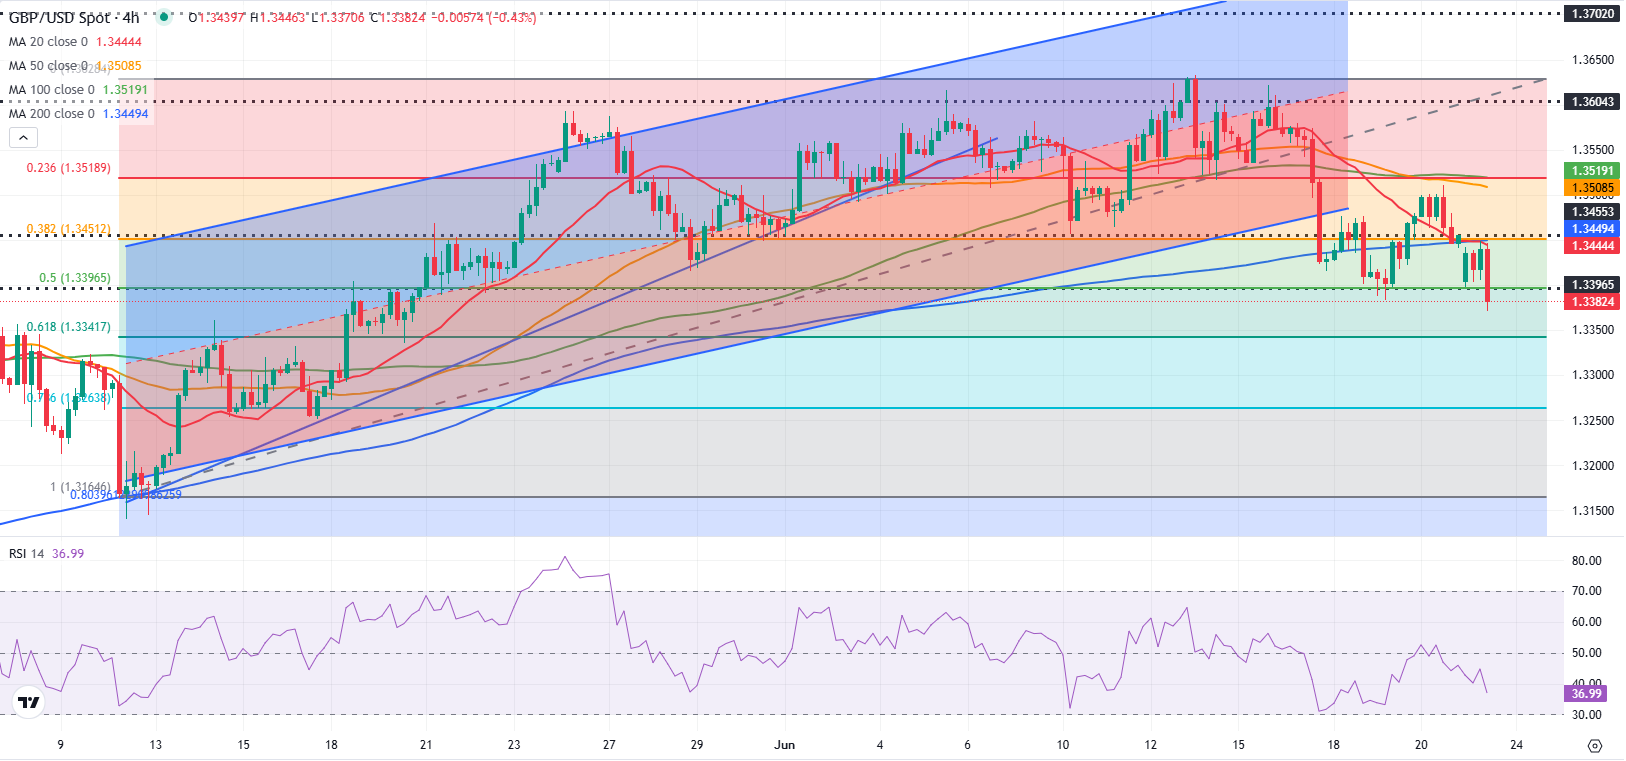
The Relative Strength Index (RSI) indicator on the 4-hour chart declines toward 30 and GBP/USD continues to pull away from the 200-period Simple Moving Average (SMA), reflecting a buildup of bearish momentum.
On the downside, 1.3340 (Fibonacci 61.8% retracement of the latest uptrend) aligns as the next support level before 1.3300 (round level, static level) and 1.3260 (Fibonacci 78.6 retracement). Looking north, resistance levels could be spotted at 1.3400 (Fibonacci 50% retracement), 1.3450 (Fibonacci 38.2% retracement, 200-period SMA) and 1.3500 (static level, round level).
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Eren Sengezer
FXStreet
As an economist at heart, Eren Sengezer specializes in the assessment of the short-term and long-term impacts of macroeconomic data, central bank policies and political developments on financial assets.















