DXY pauses near 102.00 as Fed Minutes come into focus
The US Dollar is taking a breather after its recent push higher, with DXY consolidating around the 102.0 area as markets turn their attention back towards the Federal Reserve.
US equities reached fresh highs yesterday as bonds finally caught a bid, temporarily easing the upward pressure on yields and weighing on the dollar. Oil also softened initially, with Brent briefly slipping below $100 before recovering as renewed Iranian strikes on tankers in the Strait of Hormuz kept geopolitical risk firmly in the picture.
That remains important for the dollar. Persistent energy prices complicate the inflation outlook, limiting how far bond yields can sustainably fall. In turn, that makes it difficult to build a strong bearish case for DXY while the market continues to price a relatively restrictive Fed path. Oil is particularly useful as a forward inflation input rather than simply reacting to reported inflation data.
Attention now shifts to today’s September FOMC minutes. Traders will be looking for more detail around the Fed’s reaction function, particularly what inflation outcomes could justify further tightening and how much support existed for a more dovish approach.
The hurdle for a fresh USD rally may nevertheless be fairly high. Markets already expect further tightening, while recent US data has been somewhat softer. Unless the minutes materially strengthen the case for additional hikes, much of the hawkish message may already be reflected in expectations.
Technical view
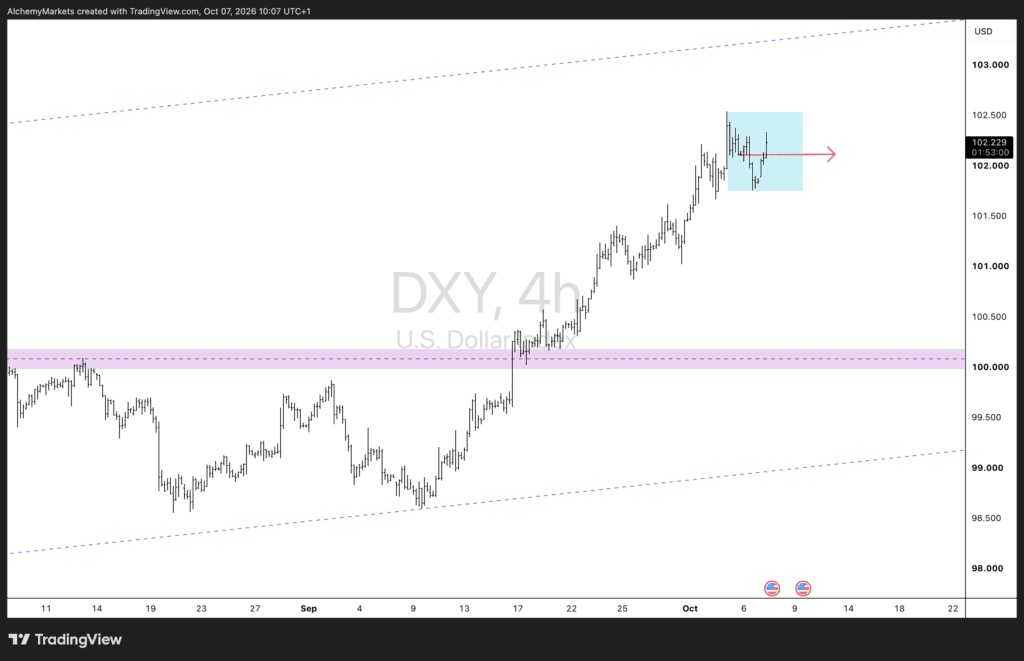
After a strong directional advance, DXY is now consolidating just above 102.00. We believe the more likely near-term outcome is a sideways correction rather than an immediate reversal lower, allowing some of the recent momentum to cool.
The current consolidation zone around roughly 101.80–102.50 therefore looks important. Holding this area would keep the broader bullish structure intact and leave the door open for another move higher once the correction has run its course.
Our view: DXY remains structurally supported, but for now we expect price to correct sideways around 102 before attempting its next directional move higher.
Author

Zorrays Junaid
Alchemy Markets
Zorrays Junaid has extensive combined experience in the financial markets as a portfolio manager and trading coach. More recently, he is an Analyst with Alchemy Markets, and has contributed to DailyFX and Elliott Wave Forecast in the past.