DXY extends climb into Fed decision, risk and EMFX tumble

Stocks Fall, Crude Oil, Metals Slide Amidst Omicron Angst
Summary: The Dollar Index, a popular measure of the Greenback’s value against a basket of 6 major currencies, rose to a 6-day peak at 96.58 (96.30 open yesterday) ahead of Federal Reserve decision tomorrow (6.00 am Sydney, 16 December). A large tumble in Emerging Market currencies against the Greenback led its Rivals lower. Markets continued to nervously monitor the spread of the Omicron variant. Risk currencies led by the Australian and Canadian Dollar fell against the Greenback. The Aussie (AUD/USD) slid 0.37% to 0.7100 (0.7137). Against the Canadian Loonie, the US Dollar rose 0.40% to 1.2860 (1.2797 yesterday) after trading to a near 3-month high at 1.2867. The Greenback ratcheted up 4.2% against the Turkish Lira to 14.400 (13.83) while the USD/INR pair (US Dollar- Indian Rupee) was up 0.26% to 76.04 (75.80), a near 5-month peak. The Euro extended its slide against the Dollar, down 0.22% to 1.1258 (1.1290). The ECB is widely expected to continue its resistance to raising rates at its policy decision. Sterling was little changed at 1.3225 (1.3220). After an initial climb to 1.3257 (overnight high), the British currency succumbed to a stronger Greenback and the threat of the Omicron variant in the UK. Wall Street stocks fell. The DOW closed 0.28% lower to 35,587 (35,742 yesterday), while the S&P 500 lost 0.74% to 4,640 (4,685).
A rise in US Producer Prices for November also provided support for the Greenback. Seasonally adjusted, the November US Headline Producer Price Index increased 0.8% from a previous 0.6%, beating economist’s expectations at 0.5%. Core PPI also beat forecasts, up at 0.7% against 0.4%.
Global treasury bond yields rose. The benchmark 10-year treasury yield gained two basis points to 1.44%. Germany’s 10-year Bund rate finished at -0.37% from -0.39% yesterday.
Other data released yesterday saw New Zealand’s Food Price Index climb to 0.6%, higher than estimates at -0.2%. Japan’s Capacity Utilisation Rate for October (m/m) rose to 6.2% from 0.7%. Japan’s October Industrial Production (m/m) beat expectations at 1.8% against 1.1%. The UK’s October Unemployment rate was at 4.2%, matching estimates. UK Claimant Count Change for November beat median estimates, falling by -49,800 against -31,500 expected. The Eurozone October Industrial Production was at 1.1%, better than the previous -0.2%, but lower than median forecasts at 1.2%. US November Core PPI (m/m) rose to 0.7% from 0.4%, beating forecasts at 0.4%.
- USD/CAD – Canada’s Loonie continued its underperformance in FX. Crude Oil prices slid 1.14% to USD 73.52 (USD 74.50). The USD/CAD pair finished at 1.2855 (1.2797), up 0.36%. The Greenback traded to an overnight and near 3-month high at 1.2867 before easing to its New York close. Amongst the majors, the Loonie was the worst performing currency.
- AUD/USD – slip-sliding away, the Aussie Battler fell 0.34% to 0.7100 from 0.7137 yesterday. Following closely behind the Canadian Loonie, the Aussie was the next worst FX performer. AUD/USD hit an overnight and near 3-week low at 0.7090 before managing to climb above the 0.7100 level.
- EUR/USD – the Euro dipped another 0.22% lower to finish at 1.1258 (1.1290 yesterday). Once again, broad-based US Dollar strength weighed on the shared currency. Eurozone Industrial Production rose 1.1%, lower than forecasts at 1.2%. Which didn’t help.
- USD/JPY – Against the Japanese Yen, the Dollar edged higher to 113.73 from 113.52 yesterday. Higher US bond yields lifted this currency pair. Overnight high traded was at 113.76. Japan’s 10-year JGB rate were unchanged at 0.04%.
On the Lookout: Today’s economic data calendar sees the release of the trifecta of Chinese data first up. First up is Chinese November Retail Sales (y/y f/c 4.9% from previous 4.95 – ACY Finlogix), followed by Chinese November Industrial Production (y/y f/c 3.6% from 3.5% - ACY Finlogix), China November Unemployment Rate (no f/c, previous was 4.9%). China’s NBS Press Conference follows shortly (traditionally no time is mentioned). Australia follows with its Westpac Consumer Sentiment (no f/c, previous was 0.6%). The UK kicks off Europe with its UK November CPI (y/y f/c 4.7% from 4.2%) UK November Core CPI (y/y f/c 3.8% from 3.4%). UK November Retail Price Index (m/m f/c 0.3% from 1.1%). France releases its Final November CPI (y/y f/c 2.8% from 2.6%). Italy follows with its Final November CPI (y/y f/c 3.8% from 3.0%). Canada starts off North American with its Canadian November Housing Starts (f/c 233,000 from previous 236,600 – ACY Finlogix), Canadian October Final Manufacturing Sales (m/m f/c 4.1% from -3% - ACY Finlogix), Canadian November CPI (y/y f/c 4.7% from 4.7% - ACY Finlogix), Canadian November Core CPI (y/y f/c 3.6% from 3.8%). The US rounds up today’s big data day with its November Retail Sales (m/m f/c 0.8% from 1.7%; y/y no f/c, previous was 16.3% - ACY Finloix). US Core (ex-autos) Retail Sales for November follows (m/m f/c 0.9% from 1.7% - ACY Finlogix), US December NY Empire State Manufacturing Index (f/c 83 from previous 83 – ACY FInlogix).
Trading Perspective: All eyes will be on the US FOMC Interest rate decision and its forward projections (which start at 6 am Sydney, 16 December). The Swiss National Bank, the Bank of England and the European Central Bank will have their policy meeting tomorrow evening. The Fed is widely expected to speed up reduction of its bond buying program. Markets expect the US central bank to raise rates 2-3 times in 2022. The Dollar Index (DXY) finished at a 6-day high (96.58). Expect the Greenback to hold firm ahead of tomorrow’s Fed meeting. The risk lies in elevated level of speculative long USD trades, which could tip over at any time. The trick lies in finding the catalyst.
- EUR/USD – the Euro extended its 2-day slide to finish at 1.1258 (1.1290 yesterday). Overnight the shared currency traded to a low at 1.1255 before settling to its New York close. Immediate support for today lies at 1.1250 followed by 1.1220. On the topside, immediate resistance can be found at 1.1290 and 1.1320. Look for the Euro to stay soft. Likely range today 1.1240-1.1310. Sell rallies.
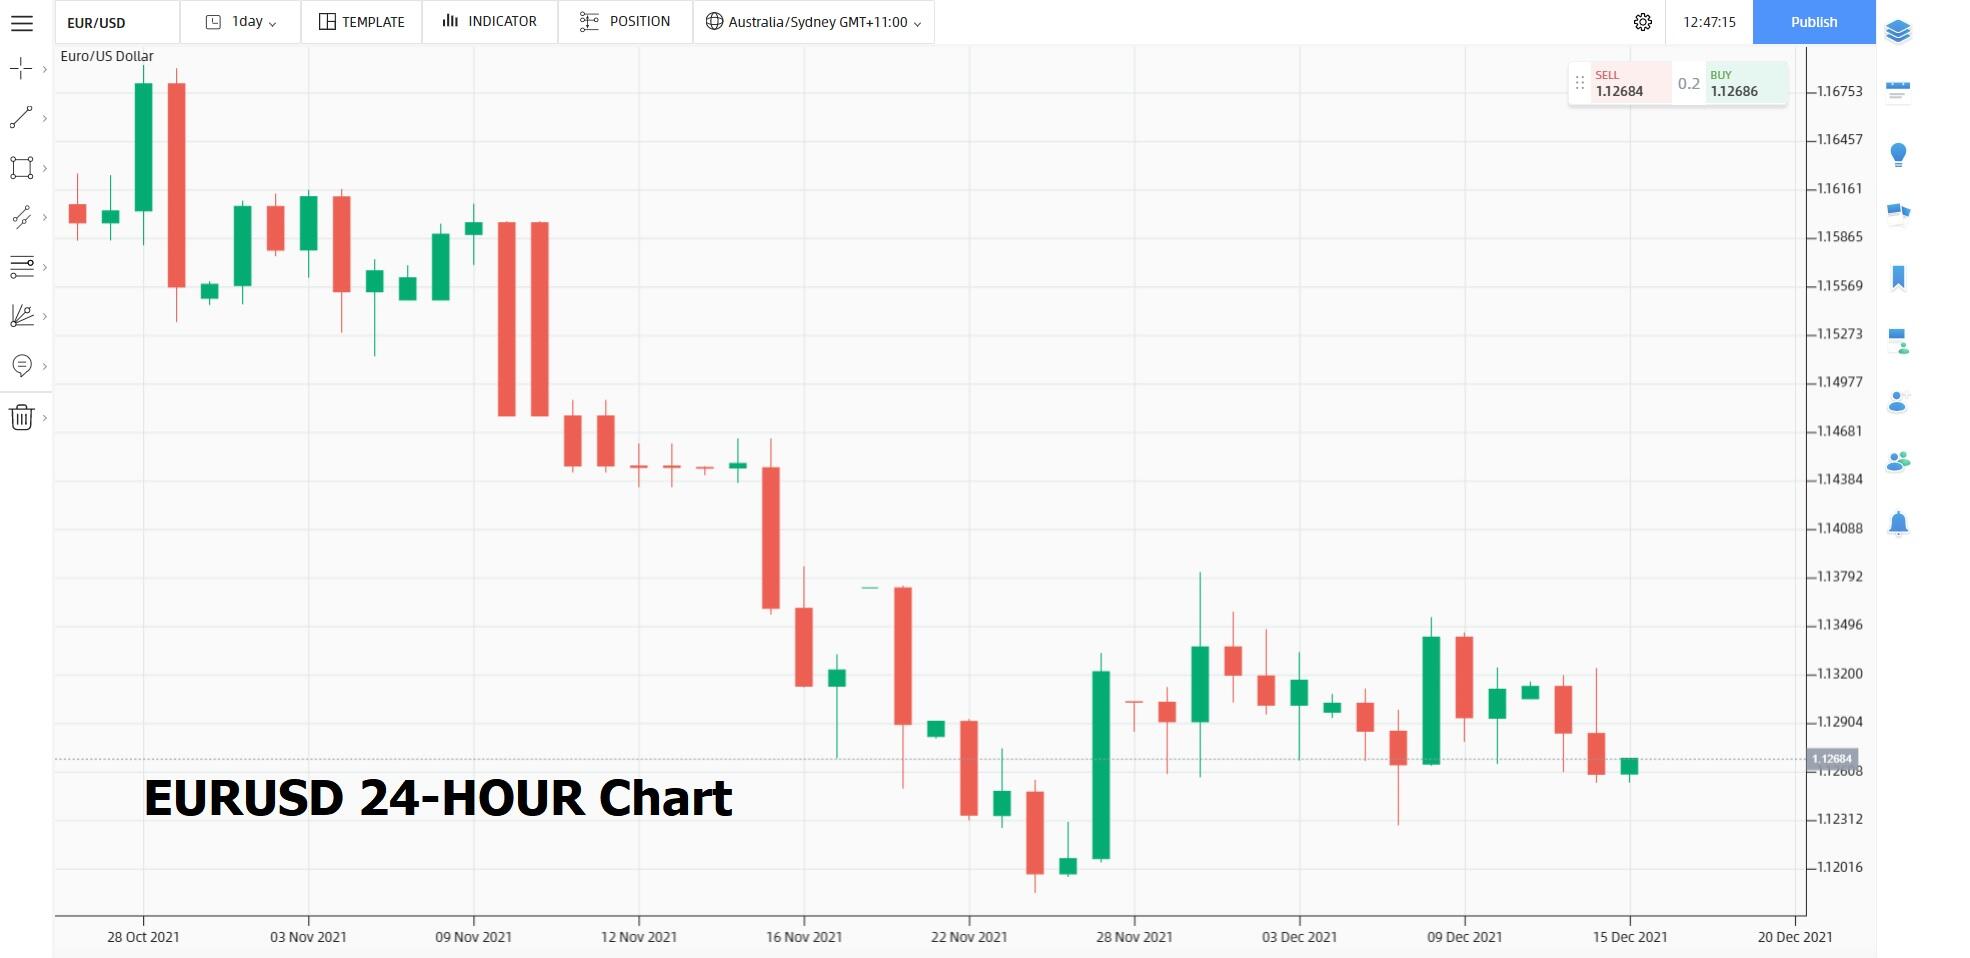
(Source: Finlogix.com)
- AUD/USD – In the current environment, expect the Aussie Battler to slide further. The weak finish in Emerging Market currencies will weigh on the AUD/USD pair. The Aussie finished at 0.7107 against 0.7137 yesterday. Overnight low traded was at 0.7090, which is today’s immediate support. The next support level lies at 0.7060. On the topside, immediate resistance can be found at 0.7135 (overnight high 0.7136). The next resistance level is at 0.7155. Look for the Aussie to drift lower in a likely range today of 0.7070-0.7120.
- USD/CAD – the Greenback soared to an overnight and near 3-month high at 1.2867 before easing to finish at 1.2858 in New York. For today, immediate resistance lies at 1.2870 followed by 1.2900 and 1.2930. Immediate support can be found at 1.2820, 1.2790 and 1.2760. Look for consolidation in a likely range today of 1.2780-1.2880. Watch for more fireworks on this currency pair.
- GBP/USD – Sterling managed to finish little changed against the Greenback at 1.3225 (1.3220 yesterday). Despite a stronger US Dollar against the other currencies, the British currency held its own. Immediate support for Sterling lies at 1.3190 (overnight low 1.3191(). The next support level is found at 1.3160. On the topside, immediate resistance can be found at 1.3255 (overnight high 1.3257). The next resistance level is found at 1.3285 and then 1.3305. Look for Sterling to trade a likely range today of 1.3185-1.3285. Trade the range shag on this puppy today.
Author

Michael Moran
ACY Securities
Michael has over 40 years’ FX experience, including running FX trading desks for some of the largest banks in the world.














