Dollar explodes higher as US-China tensions build, bond yields soar

AUD Plunges Post RBA Rate Hike; USD/JPY Takes Off in Choppy Trade
Summary: The Dollar Index (DXY), a popular measure of the Greenback’s value relative to a basket of 6 major currencies, exploded 0.84% higher in early Asia to 106.35 (105.25 yesterday). US House Speaker Nancy Pelosi touched down in Taipei, the capital of Taiwan despite warnings from China. Which saw risk-off soar on the possibilities of negative consequences for the world as tensions between the US and China were certain to build. Hawkish Fed rhetoric boosted US treasury rates. The benchmark US Ten-year bond yield climbed 10 basis points to 2.75% (2.65% yesterday. Risk FX leader, the Australian Dollar (AUD/USD) plunged 1.51% to 0.6920 after soaring to an overnight high at 0.7032. Yesterday the Reserve Bank of Australian (RBA) lifted its Overnight Cash Rate for the 4th time this year by 0.50% to 1.85%. The Kiwi (NZD/USD) tumbled to 0.6250 from 0.6285 yesterday. Against the yield sensitive Japanese Yen, the US Dollar (USD/JPY) ratcheted 1.34% higher to 133.15 against its 130.80 open yesterday. The Euro (EUR/USD) slumped 0.97% to 1.0165 from 1.0234 while Sterling (GBP/USD) slid to 1.2167 from 1.2185. The Greenback was mostly higher against the Asian and Emerging Market currencies. USD/THB (Dollar-Thai Baht) rallied 0.20% to 36.20 from 36.09 while the USD/CNH pair (Dollar-Offshore Chinese Yuan) edged higher to 6.7750 (6.7725 yesterday).
Other global bond yields were little changed. Germany’s 10-year Bund yield was last at 0.81% (0.81% yesterday). Japan’s 10-year JGB rate dipped to 0.16% (0.17%). Australia’s 10-year bond yield settled at 2.97%, against 3.05% yesterday. Wall Street stocks closed lower. The DOW fell 1.12% to 32,445 while the S&P 500 lost 0.64% to 4,095.
Data released yesterday saw Australia’s Building Approvals (m/m) climb to -0.7%, against expectations of -5.3% and a previously upward revised 11.2% from 9.9% read. UK Nationwide House Price Index (m/m) dip 0.1% against expectations and a previous 0.2%. Switzerland’s SECO Consumer Climate slumped to -42 from a previous -27, and lower than forecasts at -31. Swiss Manufacturing PMI rose to 58.0 beating forecasts at 56.3. Canada’s Manufacturing PMI eased to 52.5 from a previous 54.6. US JOLTS Job Openings fell to 10.77 million from a previous 11.30 million, and lower than estimates at 10.99 million. Early this morning New Zealand released its q/q Employment Change which eased to 0.0% against forecasts at 0.4%. New Zealand’s Q2 Unemployment Rate climbed to 3.3% from a previous 3.2%, missing expectations at 3.1%.
AUD/USD – In another volatile roller coaster ride, the Aussie eased further to 0.6920 in early Asia from yesterday’s 0.6930 close. On Monday, the Australian Dollar was trading at 0.6990 before the RBA’s rate decision. The RBA hiked rates by 0.50bp which was the fourth time this year. The AUD/USD plunged to 0.6920 from 0.7032 Monday high as risk-off hit Asia.
USD/JPY – The yield sensitive Japanese Yen tumbled against the Greenback after US bond yields took flight. The ten-basis point rise in the 10-year US bond rate to 2.75% from 2.65% saw the USD/JPY pair lift off to 133.18 overnight high from 130.80 yesterday. In early Asia today, USD/JPY jumped to a high at 133.62 before easing to settle at 133.33.
EUR/USD – Slid against broad-based US strength amidst risk-off stance to 1.0165 (1.0233 yesterday). The shared currency fell to an overnight low at 1.0161 with the weak finish suggesting further downside probes. Which re-opens the possibility of an attack at parity.
GBP/USD – Sterling slid against the Greenback to 1.2165 against 1.2202 yesterday. The British currency remained pressurised despite this week’s (Thursday, August 4) Bank of England meeting where the British central bank is widely expected to deliver a 50 basis-point rate increase.
On the Lookout: While all eyes will be on the upcoming central bank meetings, today’s economic data calendar features global Services PMIs. New Zealand kicked off with its Q2 Employment Change. Australia just released its Final Services PMI for July which eased to 50.9 from June’s 52.6. Japan releases its Jibun Bank July Final Services PMI (no f/c, previous was 54.0 -ACY Finlogix). Australia follows with its June Retail Sales report (f/c 0.2% from 0.2% - FX Street). China follows with its Caixin Services PMI (f/c 48 from previous 54.5 – FX Street). Germany kicks off European data with its June Trade Balance (f/c +EUR 0.2 billion from a previous -EUR 1 billion). Switzerland follows with its July CPI (m/m f/c -0.1% from previous 0.5%). Spain releases its July Global Services PMI (f/c 52 from 54 – FX Street), Italy follows with its July Services PMI (f/c 50.1 from 51.6 – ACY Finlogix), French July Services PMI (f/c 52.1 from 53.9 – ACY Finlogix), German July Services PMI (f/c 49.2 from 52.4 – ACY Finlogix. The Eurozone follows with its Eurozone July Services PMI (f/c 50.6 from 53.0 – ACY Finlogix). The UK releases its July Final Services PMI (f/c 53.3 from 54.3 – ACY Finlogix). The Eurozone follows with its June Retail Sales report (m/m f/c 0% from 0.2% - ACY Finlogix). The US rounds up today’s reports with its US July Final Services PMI (f/c 47 from 52.7 – ACY Finlogix), US July ISM Non-Manufacturing PMI (f/c 53.5 from 55.3 – ACY Finlogix), US June Factory Orders (m/m f/c 1.1% from 1.6% - ACY Finlogix).
Trading Perspective: The Dollar with retain its edge in FX given its risk advantage over its rivals. Traders will keep their eyes on the Chinese news releases coming from Pelosi’s Taiwan trip. China will want to make a big statement on Pelosi’s visit as it had warned against it. The geopolitical tension coupled with rising US yields will continue to support the Greenback. However, this rapidly rising tension in the region and the risk aversion it brings is not a one-way ticket higher for the US currency. An escalation of US-China tensions will eventually weigh on the US Dollar given the risks posed to the American economy. Watch the USD/JPY pair, a turnaround would be the first signal. The one common denominator for FX that we can expect is a continuation of heightened volatility in all FX pairs.
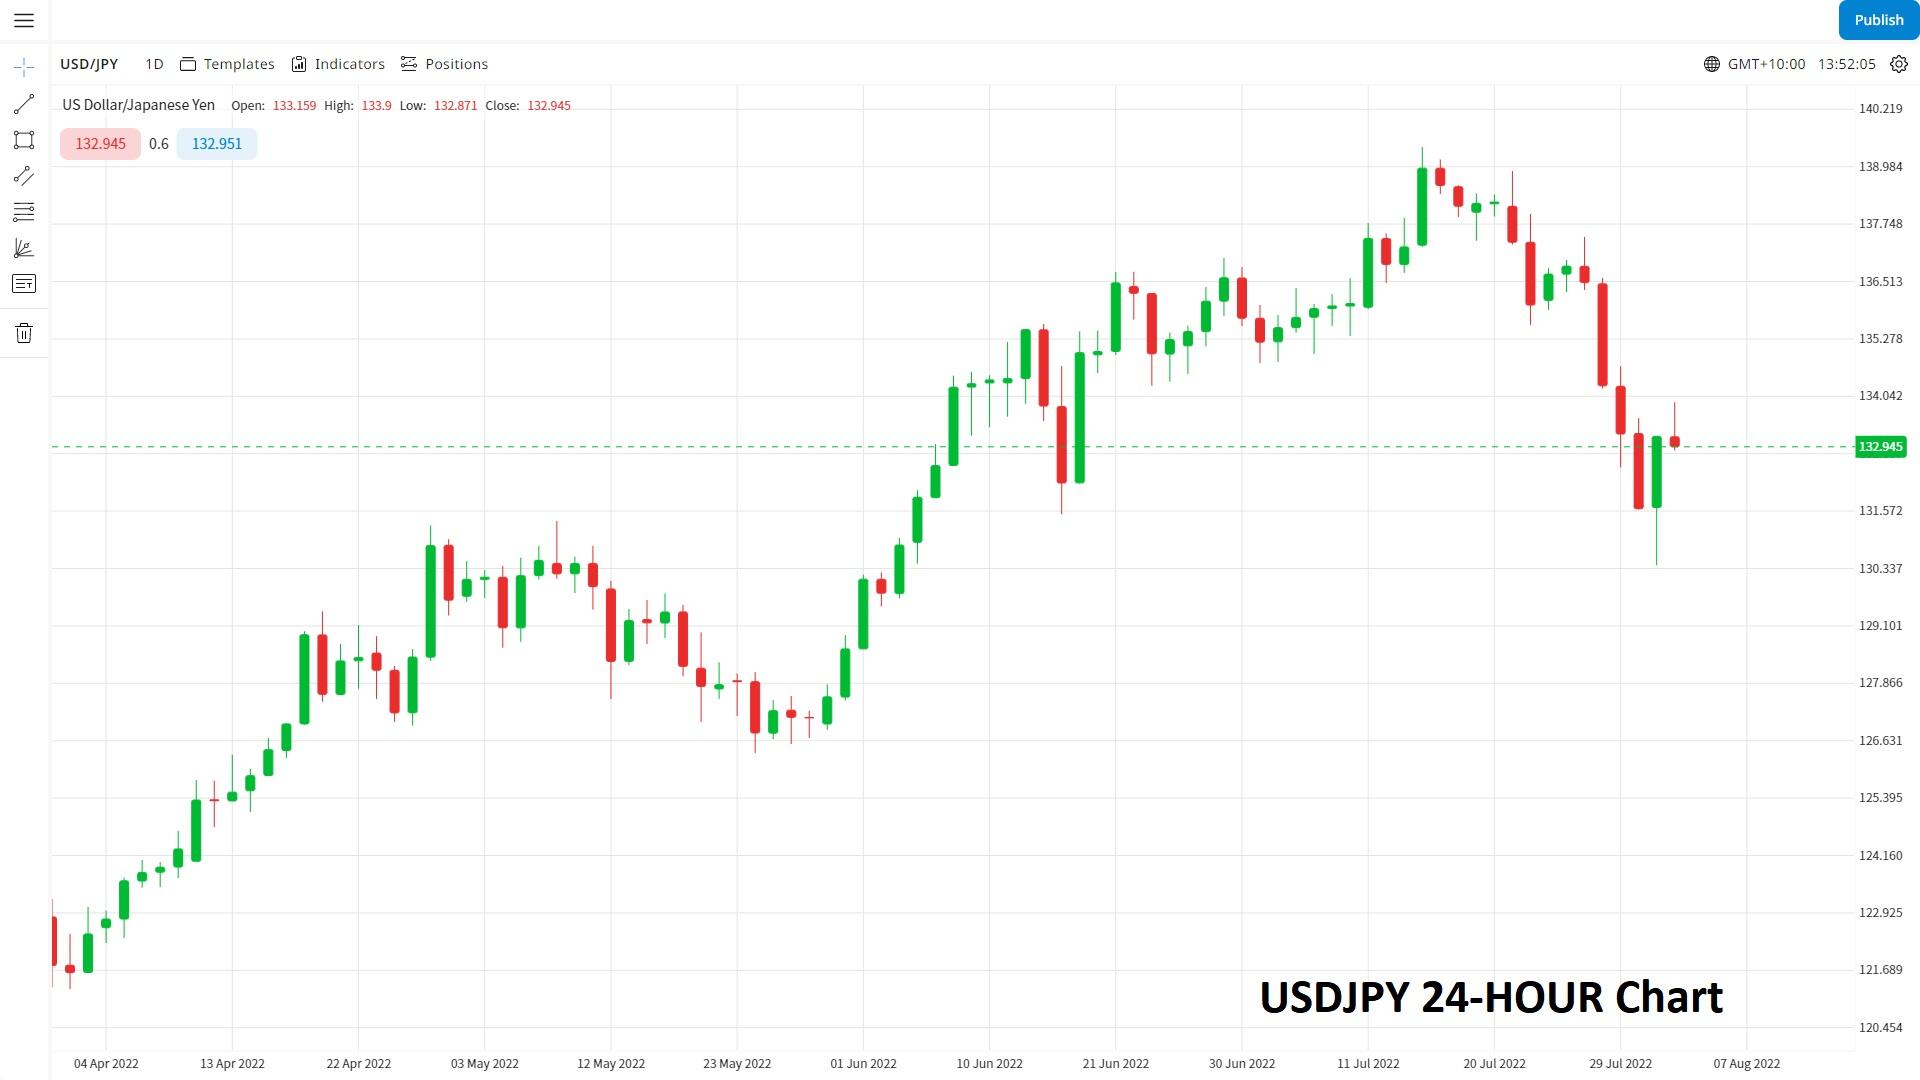
USD/JPY – The Greenback extends its grind higher in early Asia with the Dollar Yen pair no exception. USD/JPY ratcheted higher to 133.92 from 133.15 in volatile trade, settling at its current 133.60 level. On the day look for immediate resistance at 134.00 to cap further gains. The next resistance level is found at 134.50 and 135.00. Immediate support lies at 133.00, 132.55 and 132.05. Look for further volatility in this currency pair, likely range for today 131.70-134.20. Just trade the range, stay neutral is best.
(Source: Finlogix.com)
AUD/USD – The Australian Dollar inevitably suffers in risk averse markets. And this is no exception, particularly with China involved. Currently the AUD/USD pair trades at 0.6890 (0.6920 opening). Immediate support lies at 0.6885 (this morning’s recorded low). The next support level lies at 0.6850 and 0.6810. Immediate resistance is found at 0.6930, 0.6980 and 0.7020. Look for another choppy session in this currency pair, likely range 0.6850-0.7000. Preference is to sell rallies.
EUR/USD – The Euro continues its drift lower against the Greenback, currently at 1.0157 (1.0165 open). On the day, immediate support lies at 1.0150 (this morning’s low). The next support level is found at 1.0120 followed by 1.0080. Immediate resistance can be found at 1.0200, 1.0240 and 1.0280. Look for a likely, choppy trading range today between 1.0100-1.0250. Prefer to sell into Euro strength.
GBP/USD – Sterling dipped to 1.2145 from its 1.2165 NY close. Immediate support for the British Pound is found at 1.2130 (overnight low traded was 1.2134). The next support level lies at 1.2100 followed by 1.207. On the topside, look for immediate resistance at 1.0200, 1.0240 and 1.0280. With the Bank of England likely to hike rate 50 bp at the conclusion of its meeting tomorrow, look to trade a range between 1.2130-1.2230 today.
Keep those tin helmets on, we are in for more choppy times ahead. Have a good Wednesday all.
Author

Michael Moran
ACY Securities
Michael has over 40 years’ FX experience, including running FX trading desks for some of the largest banks in the world.

















