Why is the US Dollar rising despite October Fed hike odds fading?

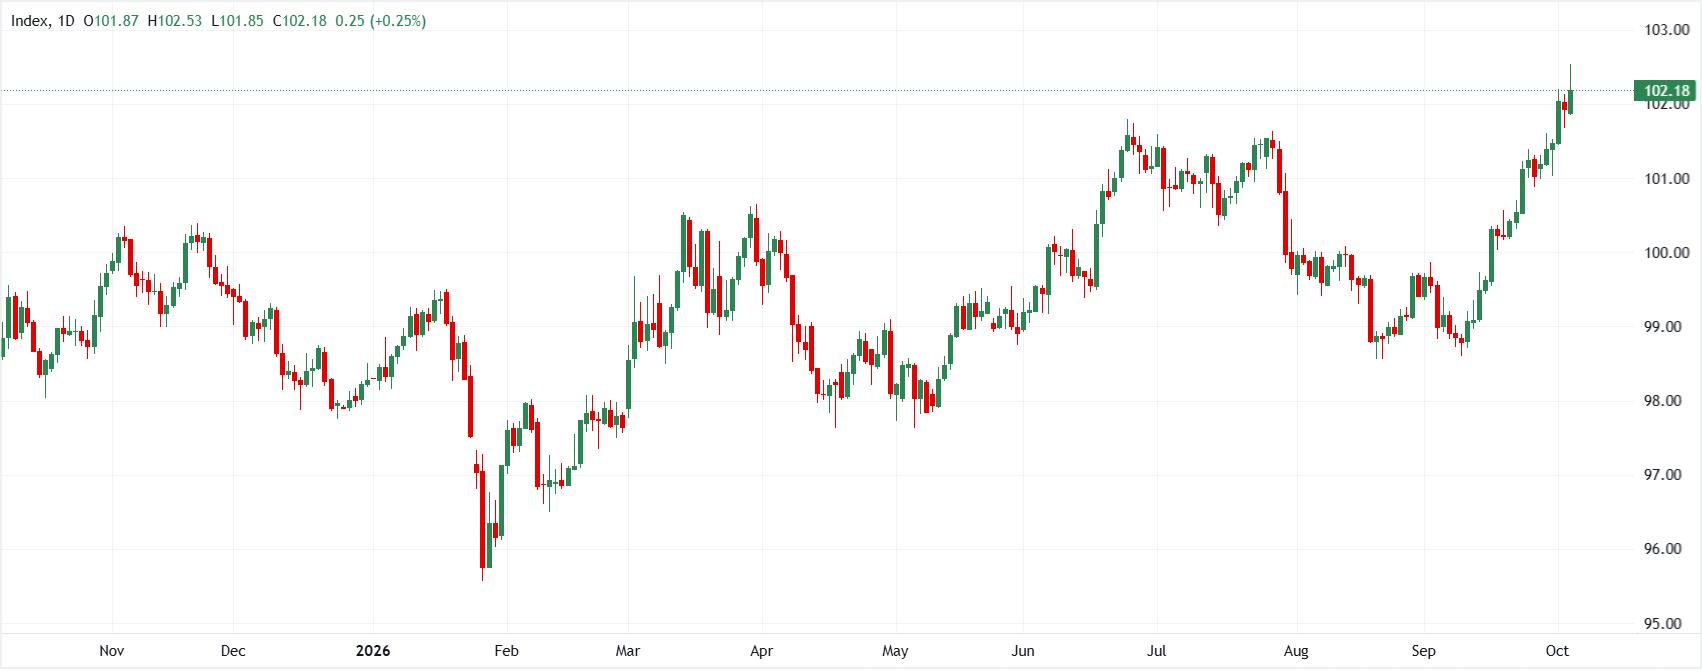
The US Dollar Index (DXY) is testing fresh yearly highs near the 102.50 zone, powered by independent Euro (EUR) weakness and relative resilience in the Federal Reserve's (Fed) rate path. However, as expectations for an October rate hike diminish following softer inflation and payrolls data, the fundamental drivers behind the Greenback’s momentum are coming under closer examination. While elevated US Treasury yields continue to lend broad support, market strategists are increasingly divided over whether rising term premia and upcoming US midterm election risks will stall the US Dollar's advance or if overseas monetary policy easing will keep the Greenback on a bullish trajectory.
Fading Fed hike expectations and fiscal yield drivers challenge USD momentum
Philip Wee at DBS Group Research cautions that the US Dollar's recent rally is running out of monetary policy impetus as senior Fed officials push back against a rate hike at the October 28 FOMC meeting. With softer PCE inflation and payrolls data altering rate expectations, attention is shifting to the composition of rising long-term US Treasury yields. Wee stresses that yields elevated by fiscal deficits, debt issuance, and term premia offer far less structural support to the Greenback than central bank tightening, while upcoming US midterm elections pose additional risks to the broader macro outlook.
"Higher yields driven by Fed tightening can support the USD. Higher term premia driven by concerns over debt supply, fiscal sustainability, and Treasury-market credibility need not. The November 3 US midterm elections add another constraint... If Republicans lose control of the House, markets could also reassess the US exceptionalism narrative that supported the USD..."
Euro weakness and resilient Fed outlook keep DXY upside target at 102.85
Taking a pro-US Dollar view, Chris Turner at ING emphasizes that the Greenback continues to gain ground against major peers, primarily fueled by heavy selling in the Euro. Despite soft September US labor data, markets remain comfortable with an October hold followed by a December Fed rate hike. With the European Central Bank’s (ECB) rate path subject to sharper dovish repricing compared to the Fed's, relative yield differentials and upcoming ISM services and FOMC minutes should continue to support DXY toward 102.85.
"DXY dollar index is pushing smartly to new highs of the year. It is being propelled by the sell-off in the euro, which represents 58% of the DXY basket. 102.85 would seem to be the next upside target here... Core support for the dollar should continue to come from the fact that expectations for the monetary policy tightening cycle remain far more resilient for the Fed than for overseas central banks – especially the ECB."
Key Takeaway
The US Dollar's move to fresh yearly highs near 102.50 demonstrates how central bank divergence and overseas weakness — particularly in the Eurozone — can sustain Greenback momentum even as the Fed pauses its tightening cycle. While DBS Group Research warns that elevated term premia and November midterm political headwinds could undermine the "US exceptionalism" trade, ING projects that smaller rate cut adjustments for the Fed relative to aggressive dovish repricing at the ECB will keep the US Dollar well-supported through year-end.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
Author
FXStreet Insights Team
FXStreet
The FXStreet Insights Team is a group of journalists that handpicks selected market observations published by renowned experts. The content includes notes by commercial as well as additional insights by internal and external analysts.

















