US stocks sink as Treasury yields boast another session of gains
- S&P 500, NASDAQ, Dow Jones also sell off in light of higher Treasury yields.
- US 2-year yield reaches 4.75%, the highest level since June 2024.
- Japan is the latest to hike interest rates by 25 bps, same as the Fed.
- Friday is a triple witching day and should foment higher volatility than usual.
Thursday's post-rate-hike rally dissipated on Friday as bulls paused the run in light of rising US Treasury yields. Government bond yields rose across the curve on Friday, with the 2-year yield up 1.5% to 4.75% and the 10-year back above 5.00%.
While the NASDAQ Composite and S&P 500 saw large gains on Thursday in spite of the Federal Reserve's (Fed) 25 bps rate hike on Wednesday, Japan's subsequent 25 bps hike overnight lent more credence to the view that the world is in the midst of a major hiking trend.
While the NASDAQ is only slightly negative at the time of writing, down 0.1%, the S&P 500 is off 0.2%, and the Dow Jones Industrial Average (DJIA) has given up 0.4%.
Importantly, the third Friday in September is a 'triple witching day,' wherein stock options, stock index futures contracts, and stock index options all expire by the close. This makes these days more prone to heavy volatility as investors close out of their options trades. This leaves the final hour of trading, the 'witching hour' between 15:00 and 16:00 EST, one of the most volatile periods of the entire quarter. Triple witching days often see double the average volume level.
Markets turn bearish on higher bond yields
The stock market remains in the grip of an artificial intelligence (AI) rally or bubble, depending on who you ask, and that rally depends on the heavy capex spending of hyperscalers that have launched a parallel boom in bond issuance.
Higher bond yields might not cause the end of the AI boom or the beginning of an economic recession, but they do make equities look relatively less attractive. At the margins, some institutional investors will likely view a 4.75% yield on the 2-year as a winning bet, which could lead to less buying pressure on equities. Over the longer term, higher bond yields mean higher private-sector borrowing costs that could also cut into margins.
As it stands, the higher Treasury yields appear to be hurting the materials and utilities sectors the worst, both of which are known for high debt profiles. But financials and real estate are also feeling the pressure as well.
In other news, Warren Buffett has stepped down as Chairman of Berkshire Hathaway (BRK.B) after holding that position for 61 years. His son Howard Buffett replaces him. The elder Buffett already handed the CEO job to Greg Abel last year.
Additionally, Federal Reserve Vice Chair for Supervision Michelle Bowman said the central bank's board is considering revisions to its capital requirements.
"Our approach will achieve this increased transparency and public accountability while making capital-related stress testing more accurate, effective, predictable and fair," Bowman said.
S&P 500 trades back to June 2 resistance
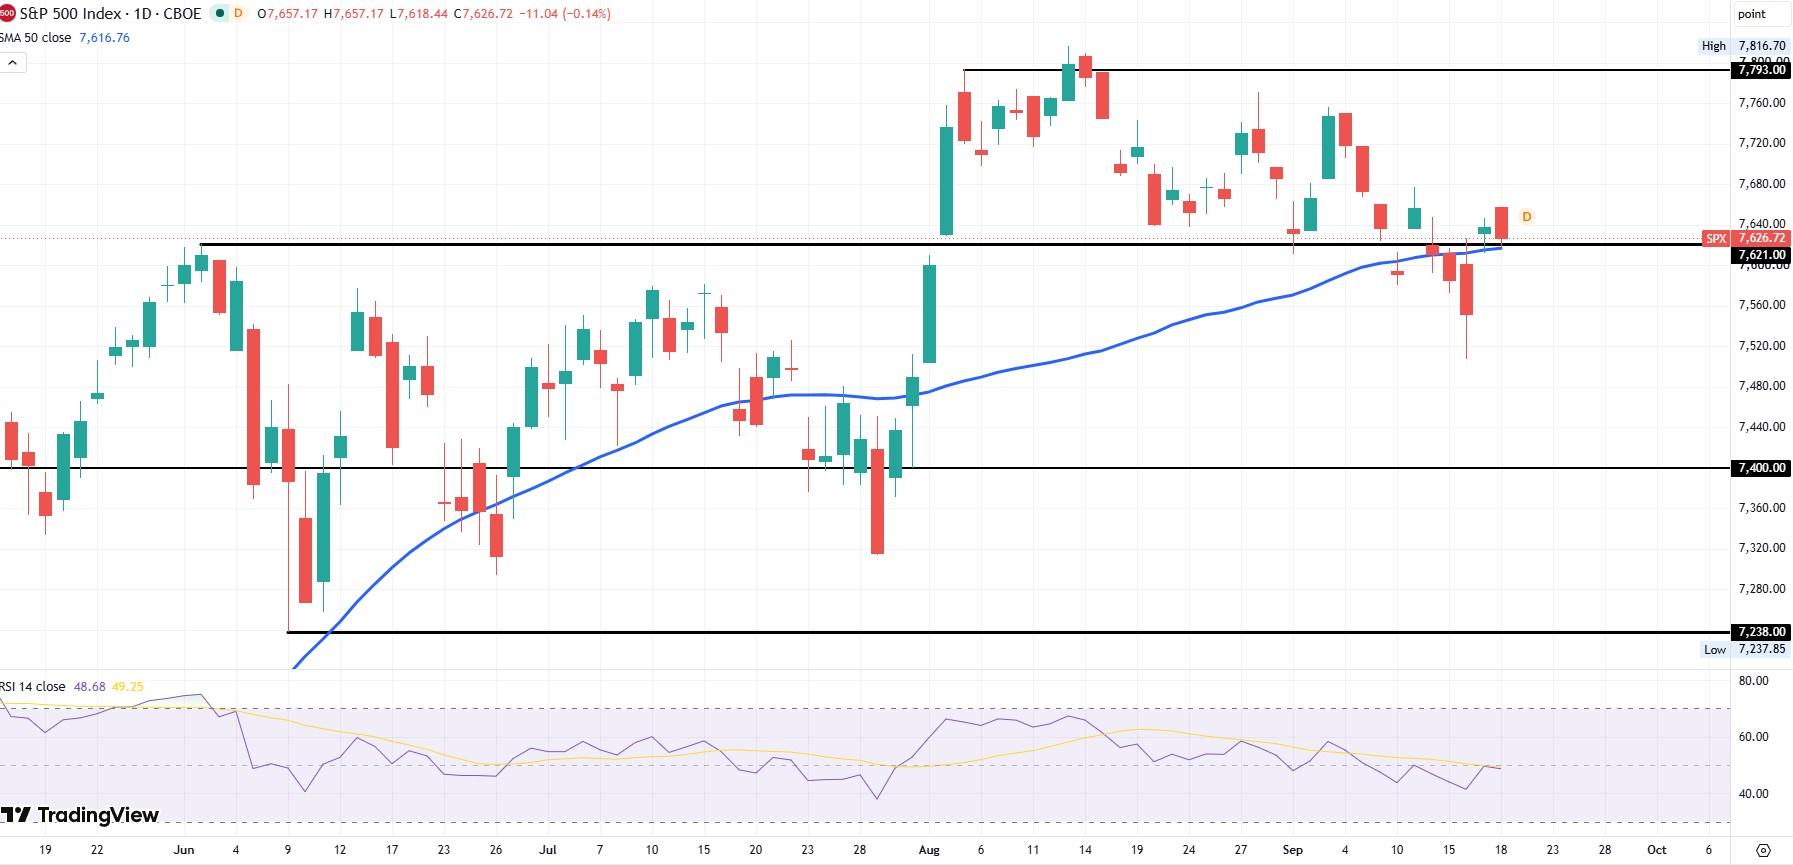
The technical levels are significant once again for the S&P 500 on Friday. The index opened dramatically higher but shot down to the June 2 high at 7,621. If that level largely holds, then it's a bullish sign for the index. This is particularly the case, since the 50-day Simple Moving Average (SMA) also appears to have held in the morning session.
Traders will notice that the Relative Strength Index (RSI) isn't showing much strength or weakness. The longer it sits near the 50 neutral level, the more firepower will build for the next breakout.
Any sustained break of 7,621 on the downside could see a push to Wednesday's low near 7,508. Otherwise, expect bulls to retest resistance at 7,800 sometime next week or at least before the month is out.
Author

Clay Webster
FXStreet
Clay Webster grew up in the US outside Buffalo, New York and Lancaster, Pennsylvania. He began investing after college following the 2008 financial crisis.

















