United States Dollar Index slumps in countdown to FOMC minutes
- The US Dollar faces selling pressure against its peers ahead of FOMC minutes.
- The Fed maintained the status quo in the July policy meeting.
- Experts believe August’s US CPI and job data, and the outcome of the Jackson Hole, will be key triggers for the US Dollar.
The US Dollar (USD) trades lower against its major currency peers on Wednesday ahead of the Federal Open Market Committee (FOMC) minutes of the July policy meeting, which will be published at 18:00 GMT.
At press time, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades 0.2% lower at around 99.45, closer to its two-month low at 99.29 posted on Monday.
US Dollar Price Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the weakest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.25% | -0.24% | -0.35% | -0.19% | 0.09% | -0.05% | -0.23% | |
| EUR | 0.25% | 0.00% | -0.11% | 0.08% | 0.33% | 0.17% | 0.01% | |
| GBP | 0.24% | -0.00% | -0.09% | 0.07% | 0.35% | 0.18% | -0.00% | |
| JPY | 0.35% | 0.11% | 0.09% | 0.17% | 0.42% | 0.27% | 0.09% | |
| CAD | 0.19% | -0.08% | -0.07% | -0.17% | 0.25% | 0.10% | -0.07% | |
| AUD | -0.09% | -0.33% | -0.35% | -0.42% | -0.25% | -0.15% | -0.31% | |
| NZD | 0.05% | -0.17% | -0.18% | -0.27% | -0.10% | 0.15% | -0.16% | |
| CHF | 0.23% | -0.01% | 0.00% | -0.09% | 0.07% | 0.31% | 0.16% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
The impact of the FOMC minutes is expected to be limited on Federal Reserve (Fed) interest rate expectations as Chairman Kevin Warsh remained committed to its “no forward guidance” policy. In the meeting, the Fed decided to leave interest rates unchanged in the range of 3.50%-3.75% and cited upside inflation risks.
Market experts also believe that the FOMC minutes won’t be a key trigger for the US Dollar’s outlook.
Dollar steadies as FOMC minutes eyed but Fed seen short of a game changer
Analysts at ING say that, for today, attention is firmly on "tonight's release of the FOMC minutes for the July meeting." They recall that "the vote was 9-3 for unchanged rates and the event proved a dovish one for the short end of the US curve and the Dollar, while the long end sold off."
ING argues that "the suspicion is that the 12-member FOMC is less hawkish than the participants whose projections delivered forecasts of a 9:9 split for a hike in the June set of Dot Plots." As a result, while "there may be a few hawkish references in tonight's minutes that could nudge the Dollar and short-dated rates a little firmer," ING stresses that "we do not see the minutes as a game changer."
Regarding the US Dollar’s outlook, analysts judge that "another batch of CPI and jobs data, plus the end-of-month Jackson Hole symposium, will have a bigger say in whether the Fed hikes in September," adding that "our base case is that it does not, and the Dollar softens a little."
According to the CME FedWatch tool, there is a 67% chance that the Fed will hold interest rates steady in September.
US Dollar Index Technical Analysis
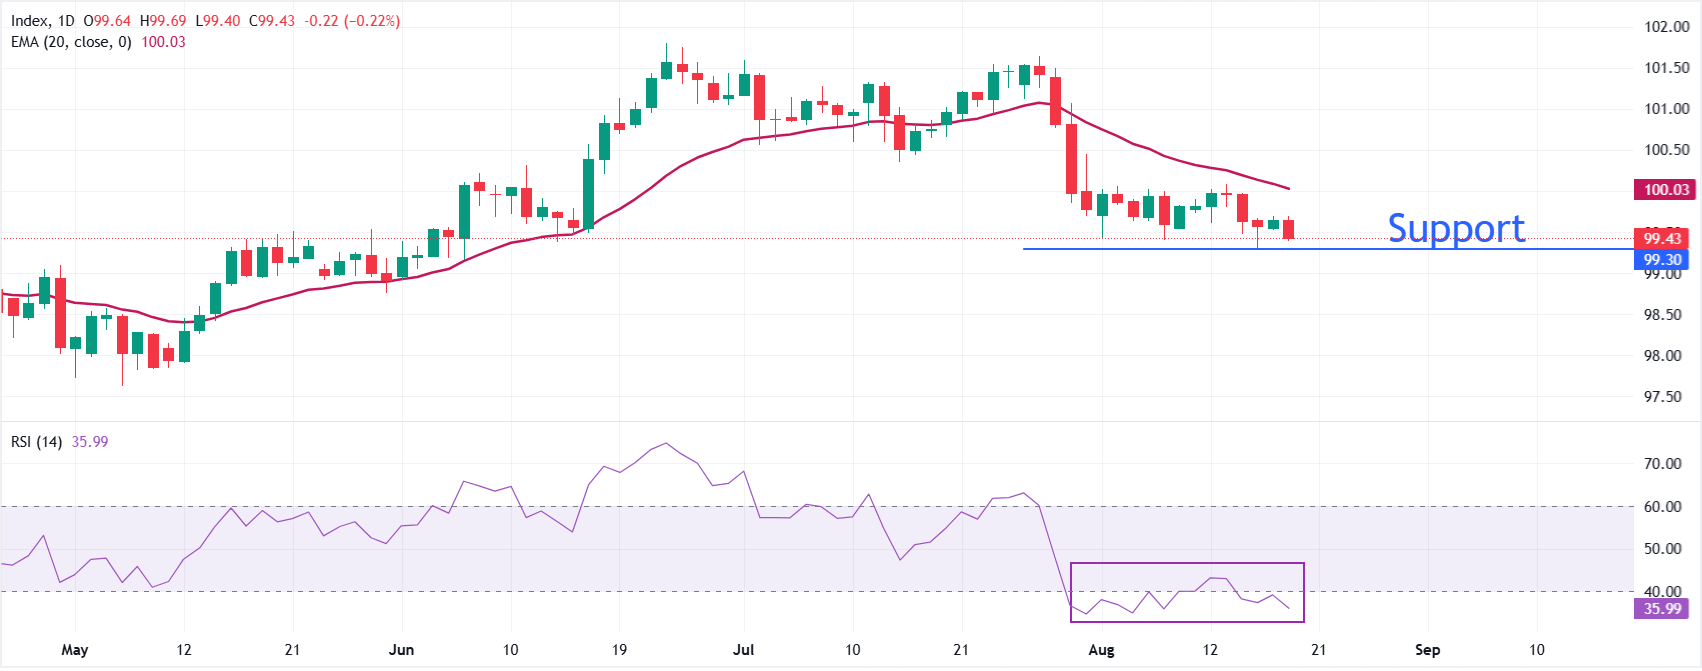
In the daily chart, Dollar Index Spot trades at 99.43, extending its decline below the 20-period exponential moving average (EMA) at 100.03, which now acts as immediate overhead resistance and keeps the near‑term bias bearish. The Relative Strength Index (RSI) at 35.95 hovers just above oversold territory, suggesting that while downside pressure dominates, selling momentum could be nearing exhaustion rather than intensifying.
On the topside, the first hurdle is the 20‑day EMA at 100.03, and a daily close above this level would be needed to ease the current bearish tone and open room toward higher recovery levels. On the downside, with no nearby structural supports from the provided dataset, short‑term traders will likely focus on price behavior around the psychological 99.00 area, while the subdued RSI reading hints that any fresh slide may become increasingly vulnerable to a corrective rebound.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Fed FAQs
Monetary policy in the US is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability and foster full employment. Its primary tool to achieve these goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, it raises interest rates, increasing borrowing costs throughout the economy. This results in a stronger US Dollar (USD) as it makes the US a more attractive place for international investors to park their money. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates to encourage borrowing, which weighs on the Greenback.
The Federal Reserve (Fed) holds eight policy meetings a year, where the Federal Open Market Committee (FOMC) assesses economic conditions and makes monetary policy decisions. The FOMC is attended by twelve Fed officials – the seven members of the Board of Governors, the president of the Federal Reserve Bank of New York, and four of the remaining eleven regional Reserve Bank presidents, who serve one-year terms on a rotating basis.
In extreme situations, the Federal Reserve may resort to a policy named Quantitative Easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used during crises or when inflation is extremely low. It was the Fed’s weapon of choice during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy high grade bonds from financial institutions. QE usually weakens the US Dollar.
Quantitative tightening (QT) is the reverse process of QE, whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing, to purchase new bonds. It is usually positive for the value of the US Dollar.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















