Three central banks held rates this week. Here's what has them all worried
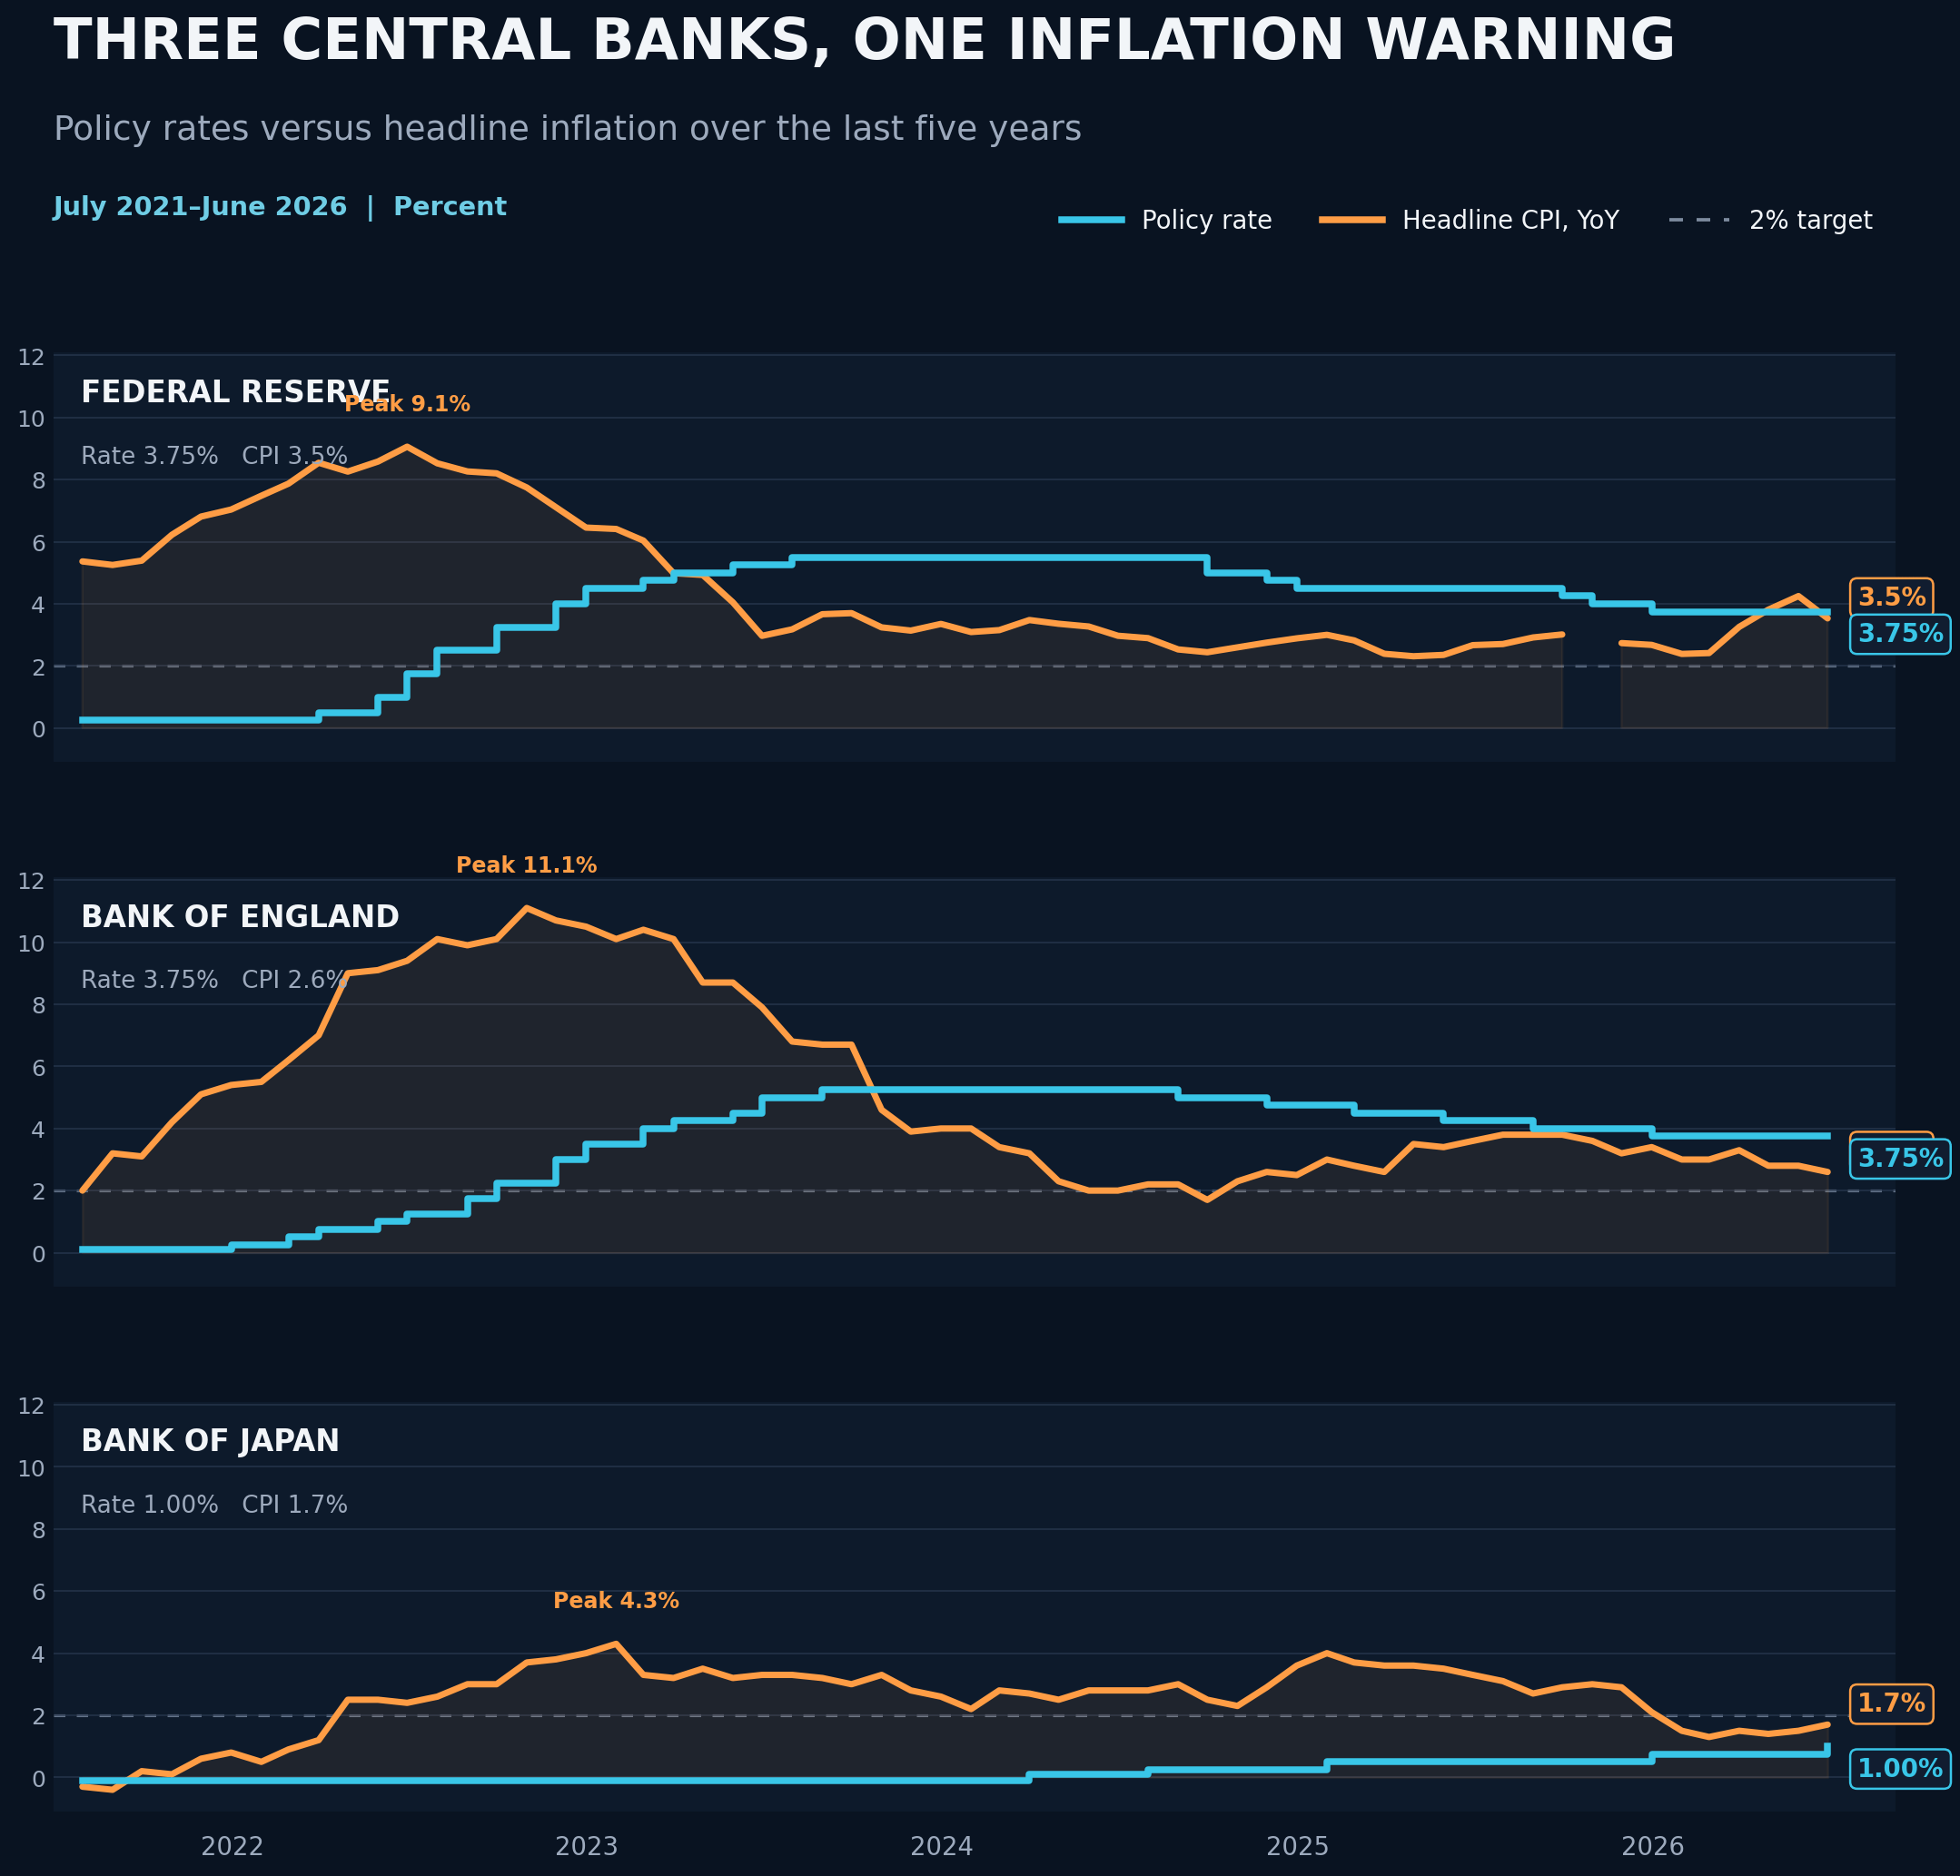
The Federal Reserve (Fed), Bank of England (BoE) and Bank of Japan (BoJ) all kept interest rates unchanged this week. Anyone looking at the decisions alone might conclude that monetary policy had entered a quiet period.
The message beneath the surface was very different.
All three central banks warned that inflation risks were building again: energy prices, geopolitical tensions, currency weakness, and the AI investment boom are creating new cost pressure, and policymakers appear increasingly willing to raise rates before they spread through wages, expectations and consumer prices.
Three holds with a hawkish message
The Fed maintained its target range at 3.50%-3.75%, but the decision produced an unusually forceful challenge from within the Federal Open Market Committee (FOMC). Beth Hammack (Cleveland), Neel Kashkari (Minneapolis) and Lorie Logan (Dallas) all voted for an immediate 25-basis-point increase.
Chair Kevin Warsh reinforced the hawkish tone during his press conference. He rejected any suggestion that the Fed had become comfortable with inflation above its target, insisting there was “no soft target” and that the central bank would deliver 2%.
The BoE delivered a strikingly similar decision. Its Monetary Policy Committee (MPC) voted 6-3 to keep the bank rate at 3.75%, compared with expectations for a 7-2 split. Megan Greene, Huw Pill and Catherine Mann wanted an immediate quarter-point increase.
The BoJ also stood pat, maintaining its short-term rate target at 1.0% in an 8-1 vote. But Governor Kazuo Ueda reiterated that the bank expected to keep raising rates if the economy and inflation developed in line with its forecasts.
These were rate holds, but none amounted to an all-clear on inflation.
Different economies, same problem
The convergence is notable because the three central banks are operating in very different economic environments.
The US economy remains resilient, with solid output and a stable labour market. Britain faces subdued activity, softer employment conditions and growth expected to slow toward zero. Japan, meanwhile, is still moving away from decades of exceptionally loose monetary policy.
Despite those differences, their concerns are beginning to look remarkably similar.
Middle East tensions and elevated Oil prices represent the most immediate threat. The BoE estimates that the indirect consequences of the energy shock will add around 0.5 percentage points to UK inflation during the second half of 2026.
Japan is already experiencing the combined impact of high Oil prices and a weaker Yen. Import costs have risen sharply, with the BoJ expecting those increases to spread gradually into the prices paid by consumers.
The Fed also identified supply shocks, including energy, as one reason inflation remains elevated.
AI is becoming an inflation story
Technology is adding another layer of uncertainty.
Strong demand for AI-related equipment and components is increasing pressure on global supply chains. The BoE identified demand for AI components as an upside risk to inflation, while the BoJ is closely watching the effect of higher memory-chip prices on durable goods.
The longer-term promise of AI is greater productivity and stronger economic growth. In the shorter term, however, enormous investment in data centres, electricity generation, semiconductors and related infrastructure could increase demand faster than supply can respond.
That leaves central banks facing an uncomfortable possibility: the AI boom may eventually reduce inflation, but it could add to price pressure first.
Why central banks may act earlier this time
The most important change is not the source of inflation, but how policymakers are responding to it.
Central banks appear less willing to assume that supply shocks will disappear without leaving a lasting mark. The inflation surge earlier in the decade demonstrated how quickly temporary increases in energy and goods prices could spread through wages, expectations and broader pricing behaviour.
The BoE explicitly warned that it might need to act before evidence of second-round effects become conclusive. Its three dissenters concluded that waiting for confirmation carried too great a risk.
Governor Andrew Bailey said there was still no clear evidence of those effects in Britain. Weak demand is limiting companies’ ability to pass on higher costs, while spare capacity in the labour market is likely to restrain wage growth. But he also warned that a prolonged Middle East conflict accompanied by broader price pressure would probably require higher rates.
Ueda was similarly cautious. He said it was more important than ever to guard against an inflation overshoot, especially as some measures of medium and long-term inflation expectations were rising significantly.
Warsh delivered the clearest warning. With US growth and employment remaining solid, the Fed has room to concentrate on price stability. Inflation, he said, cannot be defeated in nine weeks — and the central bank will not hesitate to act.
Holding rates buys time, not comfort
None of the three central banks committed to an immediate increase.
The BoE majority believes weak demand and tighter financial conditions provide time to assess how the energy shock is spreading. Bailey also suggested that the rate increases embedded in financial markets partly reflected risk premiums rather than the Bank’s central expectation.
The Fed is avoiding a predetermined policy path. Warsh said officials would focus on the underlying inflation trend, the transmission of supply shocks and the information contained in financial markets.
The BoJ is also keeping its options open. The timing and speed of additional increases will depend on inflation, economic activity, foreign exchange movements, AI-related demand and developments in the Middle East.
That flexibility should not be mistaken for indecision. Central banks are preserving their ability to respond quickly because the range of possible outcomes has widened.
The burden of proof has shifted
This is not a coordinated global tightening campaign. The Fed, BoE and BoJ have different starting points, economic conditions and domestic constraints.
What has converged is their attitude toward inflation risk.
External shocks are no longer receiving an automatic pass simply because they begin with Oil, currencies or imported components. Policymakers are focused on what happens next: whether companies raise prices more broadly, workers demand compensation, and households begin to expect inflation to remain elevated.
For now, the three central banks have chosen to wait. But their message is unmistakable: holding rates does not mean the inflation threat has passed, and the threshold for renewed tightening may be lower than markets previously assumed.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.
















