The British Pound slips again as bets on an October Fed hike build
- GBP/USD slips again under 1.3400 as bets on an October Fed hike build.
- UK August borrowing forecast at £15.7 billion, after £1.8 billion in July.
- Three of the six Bank of England members who voted to hold speak on Thursday.
GBP/USD has stalled at 1.3400 in each of the last three sessions, and it trades just under that level again on Monday. The Dollar is up against most major currencies, so this is more a Dollar move than a Pound one. Traders put the odds of a second Fed increase on October 28 at 53%, according to CME FedWatch, up from about 40% straight after the September 16 decision. The UK calendar before Friday has a borrowing figure, two surveys and three speeches, and none of them changes the UK's interest rate.
A second Fed increase is now more likely than not, eight days before the Bank of England next meets
Chicago Fed President Goolsbee said in London on Monday that if US inflation is coming from overheated demand as well as from oil and tariffs, the Fed's increases should be bigger and come sooner. Talk like that raises the odds of an October increase, and higher odds have meant a stronger Dollar against the Pound since September 16. Fed Chair Warsh said on September 16 that the Fed needn't hurt the job market to cut inflation, and President Goolsbee's remarks say doing it fast means pushing employment below the Fed's goal.
The UK's Bank Rate, which is what the Bank of England (BoE) calls its main interest rate, has been 3.75% since December 2025, and the BoE doesn't meet again until November 5. A Fed increase on October 28 would lift what a Dollar deposit earns more than a week before the BoE can do the same for a Pound deposit. That timing is why the odds move this pair.
August's borrowing forecast is bigger than the Chancellor's remaining margin
UK public sector borrowing for August is due at 06:00 GMT on Tuesday, forecast at £15.7 billion. The jump from £1.8 billion in July happens every year, because July is when the self-employed pay their second tax instalment. KPMG estimated on Monday that Chancellor Healey's margin against the government's borrowing rules has shrunk to about £12 billion from £23.6 billion at the spring forecast, with about £9 billion of that lost to higher interest costs. Investors who worry about Britain's budget hold fewer Pounds.
The Office for Budget Responsibility (OBR) works out the government's interest bill for the October 28 Budget from yields on gilts, the UK government's bonds, averaged over ten working days, and it hasn't said which ten. The 10-year gilt yield hit its highest since 2008 on September 1, and every high-yield day that falls inside the window means bigger tax rises or spending cuts. Both slow the economy and make a November increase harder for the BoE to justify, and that increase is what would lift the Pound.
A November increase needs two of the six to switch, and three of them speak on Thursday
Early readings of the UK Purchasing Managers Index (PMI) surveys are due at 08:30 GMT on Wednesday, and anything above 50 means business activity is growing. Manufacturing is forecast at 51.4 after 51.7 and services at 52 after 52.5. BoE Chief Economist Pill and external members Greene and Mann, the three who voted for an increase, argued that stronger growth means spare capacity has stopped growing. Soft surveys help the six who held and make a November increase less likely, which is bad for the Pound.
BoE Deputy Governor Breeden and external member Dhingra speak at 09:30 GMT on Thursday and Deputy Governor Lombardelli at 14:00 GMT. All three held on September 17, so any hint of a switch from them would lift the Pound. In the minutes, external member Dhingra still saw value in waiting, and Deputy Governor Breeden said an increase grows more appropriate if knock-on rises in wages and prices appear. Deputy Governor Lombardelli said the case for an increase builds the longer the Middle East war runs without a lasting resolution, which is a vote written in pencil.
The US PMI surveys follow at 13:45 GMT on Wednesday, with services forecast at 56 after 56.5. Durable goods orders are due at 12:30 GMT on Friday, forecast at -0.3% after 1.1%. The University of Michigan survey at 14:00 GMT on Friday is forecast to show one-year inflation expectations steady at 4.6%. Strong numbers from any of them raise the chance of an October increase, which means a lower GBP/USD.
Speculators held 58.7K more contracts betting against Sterling than for it in the latest weekly count from the Commodity Futures Trading Commission (CFTC), and the next count is due at 19:30 GMT on Friday. Anything on Thursday that makes November look likely would push some of those speculators to cut their bets, and cutting them means buying Pounds.
Levels and bias
Resistance: The Pound has failed to hold above 1.3400 in three straight sessions, with the 200-day average just above that level. Beyond it, 1.3500 is where the September 16 fall started.
Support: The session low just above 1.3350 comes first, then the September low just under it, set on September 17 and tested again on September 18. Below that, the Pound hasn't traded under 1.3300 since late July.
Bias: Bearish while the Pound stays below 1.3450, with 1.3300 as the first objective and 1.3200 as the second. The daily Stochastic Relative Strength Index (Stoch RSI), a momentum gauge, is near 15 and has been flat near the bottom of its range for more than a week, so the fall has slowed without turning. A daily close above 1.3450 would put the Pound back over its 200-day average and end the bearish case.
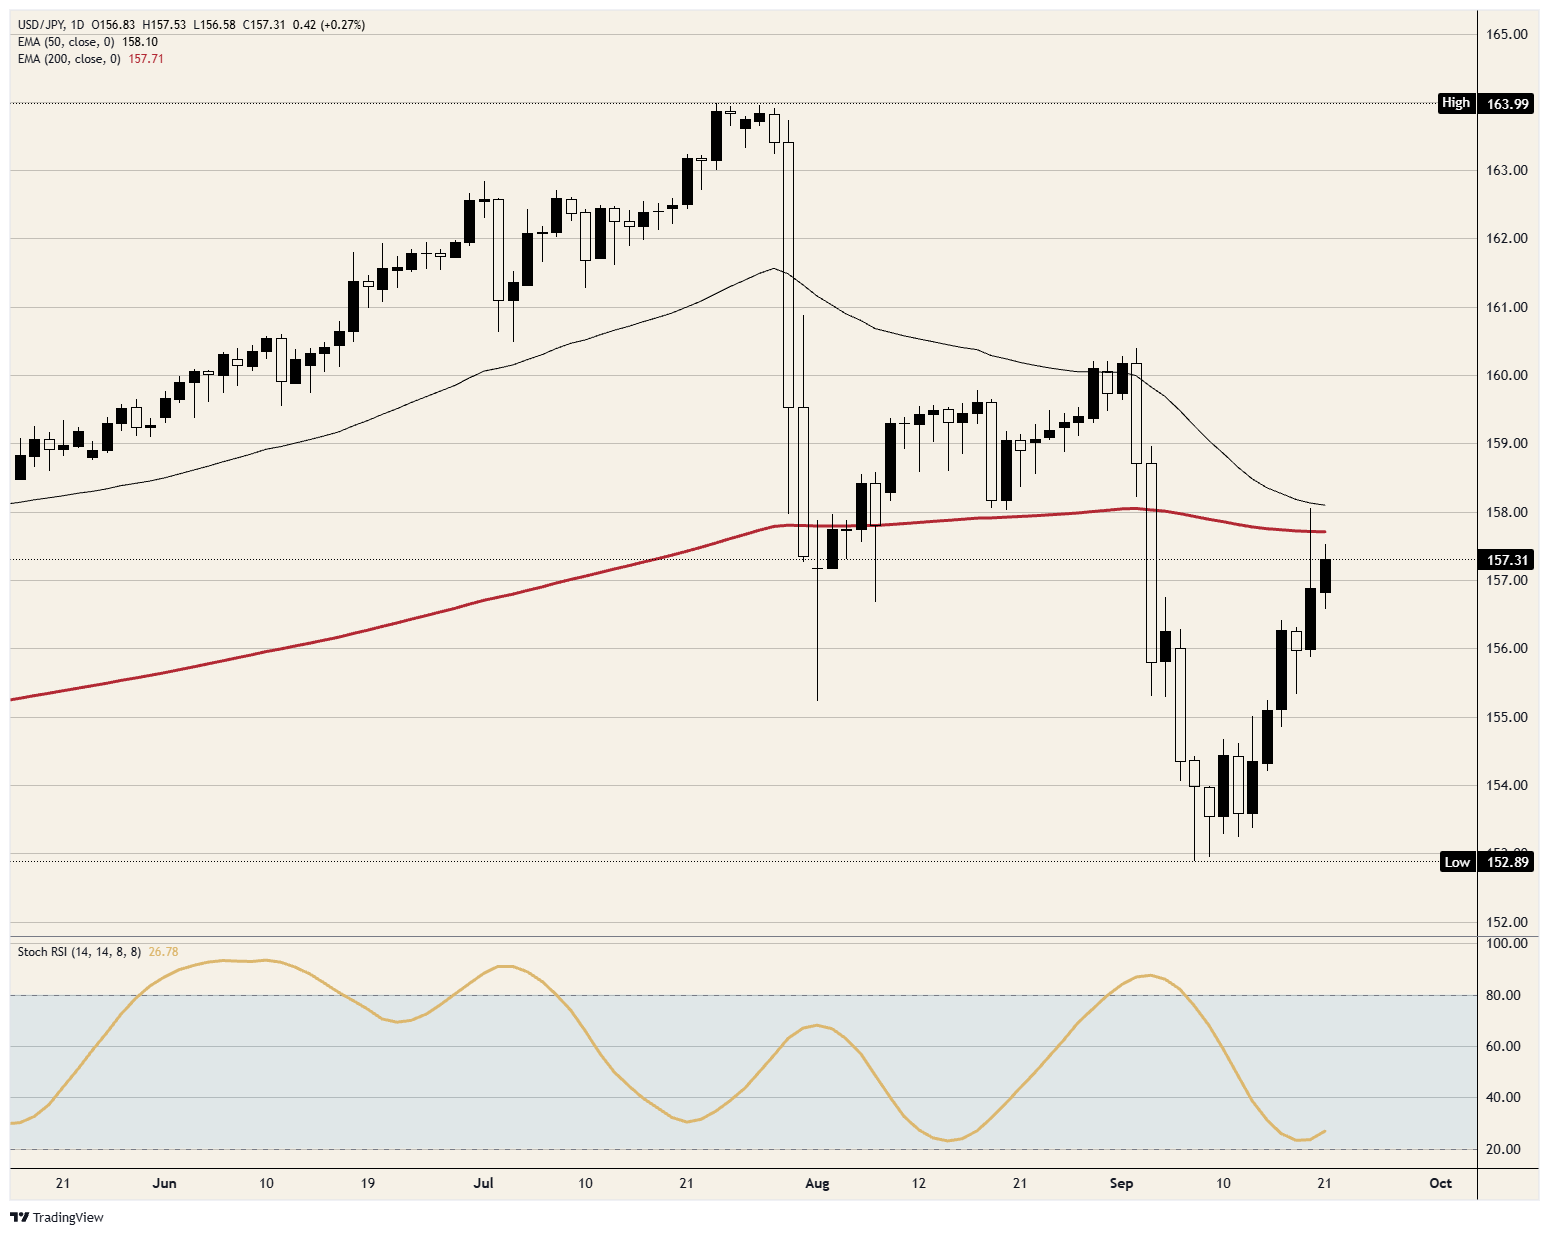
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.















