|

NZD/USD hits YTD low amid China’s real estate concerns, high US yields

  • China’s property crisis and weak recovery data amplify global risk aversion, favoring the US Dollar.
  • US 10-year Treasury bond yield at 4.172%, with the DXY index gaining 0.18%, pressuring the NZD/USD.
  • RBNZ will likely maintain a 5.50% rate, as Kiwibank analysts predict a hold until inflation targets are met.

NZD/USD posts modest gains in the North American session amid a risk aversion spurred by China’s real estate woes triggering a flight to safe-haven assets and bolstering the Greenback, which remains underpinned by high UST bond yields. The NZD/USD is trading at 0.5985, up 0.07%, after reaching a new year-to-date (YTD) low of 0.5943.

Greenback gains strength as risk aversion dominates; RBNZ anticipates to hold rates amid New Zealand economic challenges

Wall Street has turned positive in the day, though the story favors the Greenback in the FX space. The latest week’s soft data from China portrays a weaker economic recovery, while its property crisis keeps investors uneasy.

US Treasury bond yields edged higher during the session, though they had pared their earlier gains, with the US 10-year Treasury bond yield sitting at 4.172%, clinging to gains of one basis point. The US Dollar Index (DXY), which measures the buck’s value against a basket of peers, gains 0.18% and stays at 103.034, with headwinds for the NZD/USD.

The US economic calendar will feature US Retail Sales, which are expected to improve compared to June’s data, while Import and Export prices are expected to increase a tick. Manufacturing activity in New York is expected to remain subdued, while Fed speakers could give some clues regarding the Fed’s forward path.

On the New Zealand front, the Reserve Bank of New Zealand (RBNZ) is expected to keep rates unchanged at 5.50%, as the NZ economy remains in a mild recession, while inflation has fallen to 6.0%, from 7.3% last year. Analysts at Kiwibank said, “The cash rate has peaked...and will remain there until the RBNZ is convinced inflation will return to the target.”

NZD/USD Price Analysis: Technical outlook
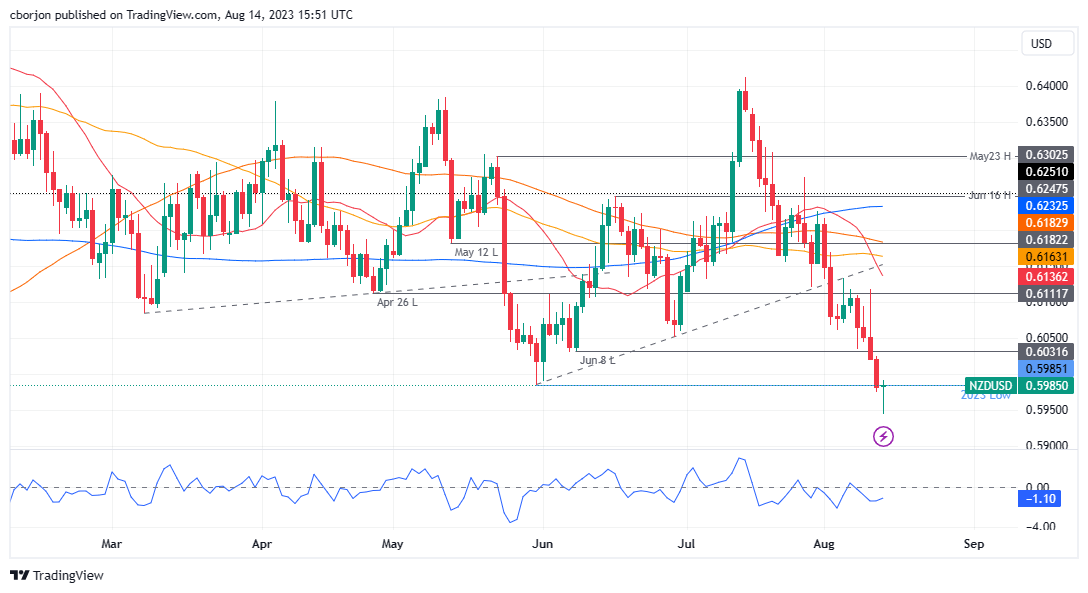
From a technical standpoint, the NZD/USD remains downward biased, reaching a new YTD low, but buyers entered the market, lifting the pair to test the prior’s YTD low of 0.5985. A daily close above the latter and the NZD/USD could regain the 0.6000 figure, with the next resistance emerging at 0.6024. Otherwise, the NZD/USD could extend towards 0.5900 before testing last year’s November 10 swing low of 0.5840.

NZD/USD

Overview
Today last price0.5984
Today Daily Change0.0000
Today Daily Change %0.00
Today daily open0.5984
 
Trends
Daily SMA200.6153
Daily SMA500.6164
Daily SMA1000.6184
Daily SMA2000.6233
 
Levels
Previous Daily High0.6089
Previous Daily Low0.5974
Previous Weekly High0.6118
Previous Weekly Low0.5974
Previous Monthly High0.6413
Previous Monthly Low0.612
Daily Fibonacci 38.2%0.6018
Daily Fibonacci 61.8%0.6045
Daily Pivot Point S10.5942
Daily Pivot Point S20.5901
Daily Pivot Point S30.5827
Daily Pivot Point R10.6057
Daily Pivot Point R20.613
Daily Pivot Point R30.6172
 

Author

Christian Borjon Valencia

Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.


More from Christian Borjon Valencia
Share:

Editor's Picks

AUD/USD consolidates above 0.7000; remains close to monthly top

AUD/USD holds steady above 0.7000 during the Asian session on Friday, trading just below the previous day's monthly low amid diverging forces. A hawkish RBA continues to support the Aussie, while the recent decline in US bond yields keeps the US Dollar depressed near a three-week low. However, oil-driven inflation fears reinforce Fed hike bets, which, along with geopolitical risks, could benefit the safe-haven buck and cap the currency pair.

USD/JPY bounces off one-month low; climbs to 157.00 amid reviving USD demand

USD/JPY rebounds from the 156.00 neighborhood, or a one-month low touched during Friday’s Asian session, with bulls looking to extend momentum beyond 157.00 amid the emergence of some US Dollar buying. Meanwhile, Japan's National CPI rose to a nine-month peak and reaffirmed BoJ rate-hike bets, which could support the Japanese Yen and cap gains for the currency pair.

Gold treads water around $4,000

Gold prices maintain its offered stance in place at the end of the week, hovering around the key $4,000 threshold per troy ounce. The persistent selling bias in the precious metal comes amid decent gains in the US Dollar and an acceptable rebound in US Treasury yields across the curve, all alongside further upside traction in crude oil prices.

Week ahead: Central bank and earnings bonanza could roil markets

After joining the rate-hike club in September, the Federal Reserve looks set to stand pat in October, waiting to assess more data before deciding to hike again. Whilst this isn’t an unusual move for a central bank, it somewhat contradicts Fed Chair Kevin Warsh’s new mantra of data dependency and zero forward guidance.

CFTC Report: WTI rally runs ahead of positioning
The week in one sentence: WTI prices surged while speculative longs were cut in the week to October 20, creating the clearest price/positioning divergence. Sterling and the Canadian Dollar led the constructive currency shift, while Yen longs also rebuilt. Speculators turned less constructive on the WTI, reducing their net exposure to around 89.3K contracts.
What November 3 means for the Fed's rate path and the US Dollar

The USD faces a decisive period ahead of the November 3 midterm elections. While markets anticipate another interest rate increase from the Fed in December, the battle for control of Congress could reshape fiscal policy expectations and, indirectly, the path of US monetary policy in 2027.















