New Zealand Dollar grinds lower as US bond yields climb to new highs
- NZD/USD grinds to its lowest since late June as US bond yields climb to new highs.
- Markets price at least a 75% chance of an RBNZ hike to 3% on October 28.
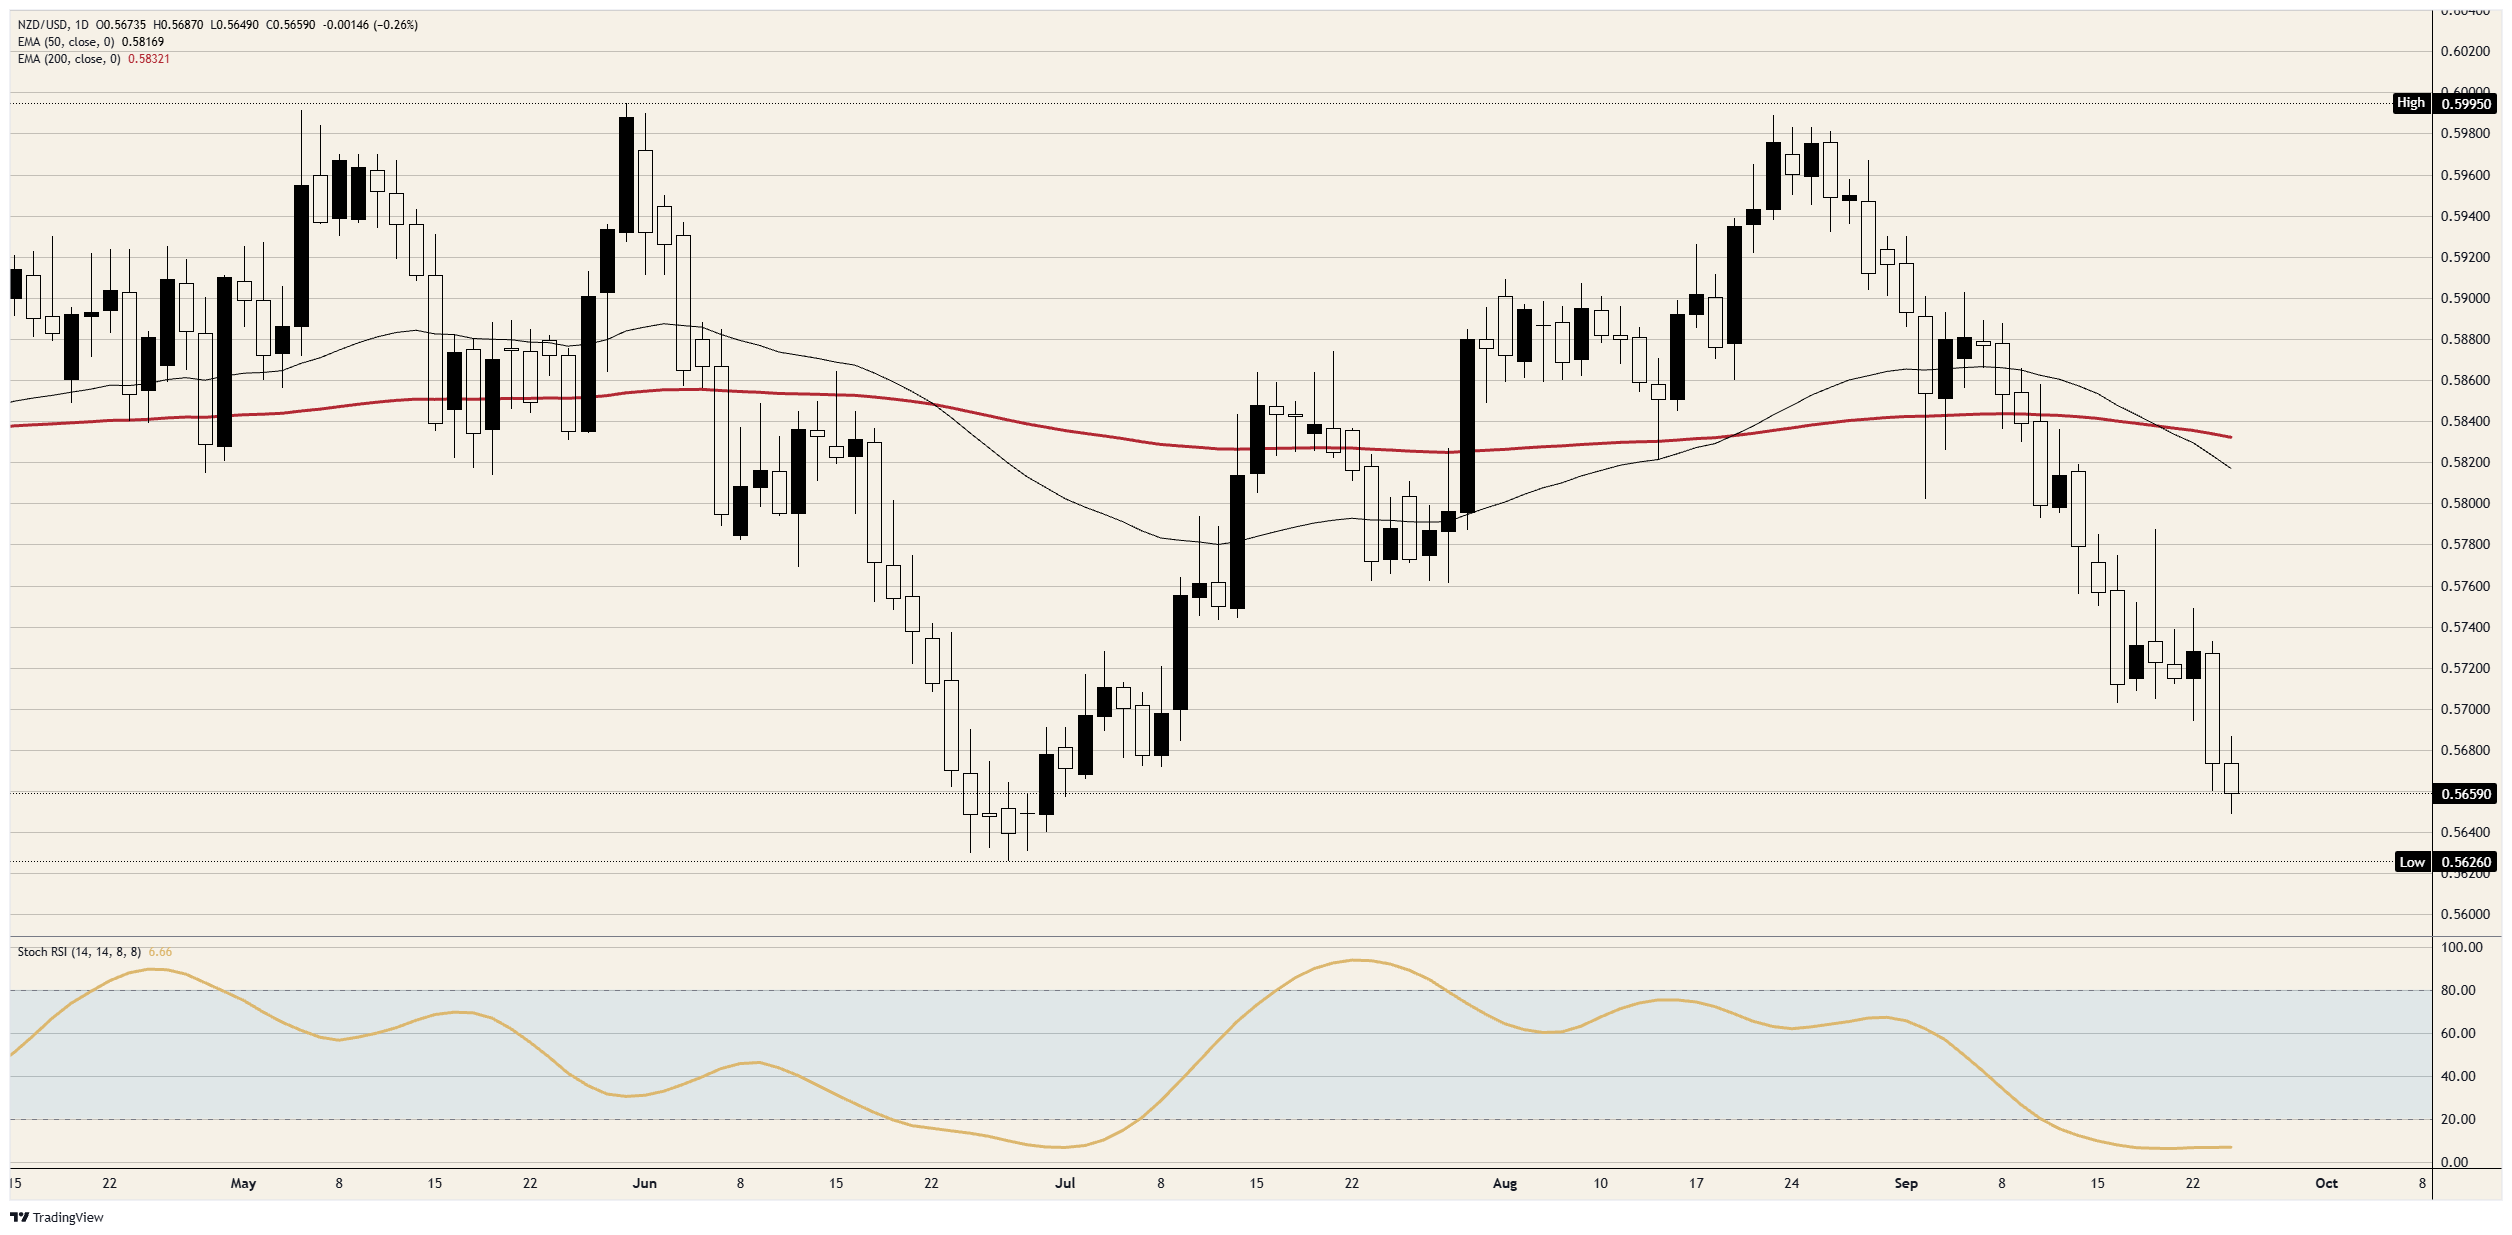
- About nine-tenths of the late-June to August rally is gone.
The Reserve Bank of New Zealand (RBNZ) has its Official Cash Rate (OCR) at 2.75%, and markets now price at least a 75% chance that it goes to 3% on October 28, against about 30% right after the September 2 hike. NZD/USD is trading just above 0.5650, its lowest since late June. The Kiwi has kept falling while the odds of a hike at home more than doubled, because the Fed is expected to raise rates on the same day.
RBNZ Governor Breman said on Tuesday that near-term inflation could run above the RBNZ's forecast if higher Crude Oil prices persist, and the pricing moved within a day. New Zealand imports its fuel, so Brent trading above $106 a barrel on Thursday feeds straight into that argument. The RBNZ's own rate track, published on September 2, pointed to a pause in October and a hike in December, which puts markets a full meeting ahead of the central bank's forecast.
The RBNZ decides 17 hours before the Fed does
The RBNZ announces at 01:00 GMT on October 28 and the Fed at 18:00 GMT, so a Kiwi rally on an RBNZ hike would have most of a day before the US decision lands. The Fed's range is 3.75%-4.00% after its September 16 hike, and futures put the odds of another quarter-point in October at better than even. US 10-year Treasury yields topped 5.15% on Thursday, their highest since July 2007.
For the Kiwi to gain on rates alone, the RBNZ has to hike while the Fed holds. It's possible the Fed holds in October, although 16 of its 18 policymakers projected at least one more hike this year in their September forecasts.
Building permits won't move a hike bet this size
New Zealand's own calendar is thin. Building permits for August come out on Wednesday, September 30 at 21:45 GMT, after a -4.3% fall in July, and ANZ-Roy Morgan consumer confidence follows on Thursday, October 1 at 21:00 GMT, previously at 98. Neither is likely to shift an October hike that markets already rate at three-in-four or better.
US releases will do more of the work. Durable goods orders on Friday at 12:30 GMT are forecast to fall 0.4% after a 1.1% rise, which in this market would count as good news for the Kiwi. The Personal Consumption Expenditures (PCE) price index lands on September 30, after core prices rose 3.3% YoY in July, and the Institute for Supply Management (ISM) manufacturing survey on October 1 comes after a prices-paid reading of 71.1. Payrolls close the run on October 2.
Levels and bias
Resistance: 0.5700 gave way on Wednesday, the larger of the two down days, and Thursday's bounce stalled short of it. Above that, 0.5750 capped Tuesday's rebound.
Support: Thursday's low is just under 0.5650. Under that, the late-June low just above 0.5600 is the only stop before 0.5550.
Bias: Short below 0.5700, aiming for 0.5600 and then 0.5550. The daily Stochastic Relative Strength Index (Stoch RSI) has been pinned in single digits for more than a week, so a bounce could come without changing the lean. A daily close above 0.5750 cancels it.
NZD/USD daily chart
New Zealand Dollar FAQs
The New Zealand Dollar (NZD), also known as the Kiwi, is a well-known traded currency among investors. Its value is broadly determined by the health of the New Zealand economy and the country’s central bank policy. Still, there are some unique particularities that also can make NZD move. The performance of the Chinese economy tends to move the Kiwi because China is New Zealand’s biggest trading partner. Bad news for the Chinese economy likely means less New Zealand exports to the country, hitting the economy and thus its currency. Another factor moving NZD is dairy prices as the dairy industry is New Zealand’s main export. High dairy prices boost export income, contributing positively to the economy and thus to the NZD.
The Reserve Bank of New Zealand (RBNZ) aims to achieve and maintain an inflation rate between 1% and 3% over the medium term, with a focus to keep it near the 2% mid-point. To this end, the bank sets an appropriate level of interest rates. When inflation is too high, the RBNZ will increase interest rates to cool the economy, but the move will also make bond yields higher, increasing investors’ appeal to invest in the country and thus boosting NZD. On the contrary, lower interest rates tend to weaken NZD. The so-called rate differential, or how rates in New Zealand are or are expected to be compared to the ones set by the US Federal Reserve, can also play a key role in moving the NZD/USD pair.
Macroeconomic data releases in New Zealand are key to assess the state of the economy and can impact the New Zealand Dollar’s (NZD) valuation. A strong economy, based on high economic growth, low unemployment and high confidence is good for NZD. High economic growth attracts foreign investment and may encourage the Reserve Bank of New Zealand to increase interest rates, if this economic strength comes together with elevated inflation. Conversely, if economic data is weak, NZD is likely to depreciate.
The New Zealand Dollar (NZD) tends to strengthen during risk-on periods, or when investors perceive that broader market risks are low and are optimistic about growth. This tends to lead to a more favorable outlook for commodities and so-called ‘commodity currencies’ such as the Kiwi. Conversely, NZD tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.