Euro watches its best arguments sink in the Strait of Hormuz
- EUR/USD logged its weakest close since last Wednesday, surrendering a third of a percent to finish at 1.1406, essentially on the session low.
- Hawkish-scored remarks from one of the European Central Bank's most reliable doves and a soft American payrolls proxy bought the single currency nothing.
- Late-day United States strikes on Iran and a full sanctions snap-back set a nervous stage for Wednesday's Federal Reserve minutes at 18:00 GMT.
The Euro spent Tuesday assembling the sort of case that should buy a currency a bid: hawkish-leaning remarks from an unlikely corner of the European Central Bank (ECB), a softening American payrolls proxy, and a Federal Reserve (Fed) regional president content to say nothing new. The market read the file, shrugged, and sold the single currency anyway, fading it from an early peak just shy of 1.1450 to a 1.1406 close, its weakest finish since last Wednesday.
The Strait of Hormuz then finished the job, with late-session headlines confirming fresh Iranian strikes on commercial shipping and an American military and sanctions response that handed the Dollar a haven bid into the close. What began as quiet positioning ahead of Wednesday's Federal Open Market Committee (FOMC) minutes ended with the pair pinned near its low and Brent Crude Oil sharply higher.
A hawkish dove, a soft payrolls proxy, and nobody buying
Tuesday's European calendar was headlined by remarks from a Governing Council member long counted among the ECB's most reliable doves, and the speech registered well to the hawkish side of that speaker's own scoring average. The intervention extended Monday's pattern, when an Executive Board member warned that the inflation fight is not finished, and it lands against market pricing that treats one further quarter-point ECB hike this year as likely while assigning almost nothing to the July 23 meeting itself.
Across the Atlantic, the four-week average of ADP's employment change series slipped to 21,000 from 24,250, another reading that suggests the private hiring engine is idling, while the New York Fed chief delivered a studiedly neutral message. A softening labour pulse set against a hawkish ECB chorus is the textbook recipe for a firmer Euro; that the pair could not even hold the 1.1440s on that mix says the market's attention was already elsewhere.
The Strait of Hormuz reprices the week
The elsewhere in question arrived from the Gulf, where Iranian forces struck three commercial vessels transiting the Strait of Hormuz from Monday into Tuesday, among them a Qatari liquefied natural gas carrier and a Saudi tanker. One ship was left burning off the Omani coast, with no crew casualties reported.
Washington's answer landed late Tuesday in two parts, with United States Central Command announcing retaliatory strikes on Iranian missile, drone, and radar sites and calling the vessel attacks a clear violation of the ceasefire signed at Versailles. The Treasury separately revoked its sanctions relief on Iranian Crude Oil exports in its entirety, giving buyers until July 17 to wind down existing transactions.
Brent Crude Oil jumped roughly three percent toward $76 per barrel on the news, and the Dollar caught the haven flow that Middle East re-escalation reliably produces. The single currency absorbed the move directly, stepping down through 1.1410 in the final hours of trade to settle a whisker above the session trough.
The escalation also cuts against the Euro through a second channel that matters more than any haven bid. American consumer price inflation ran at 4.2 percent in May, a three-year high driven substantially by energy, and that energy-led persistence is exactly what pushed nine FOMC participants to pencil in at least one hike by year-end while the easing bias vanished from the June statement. Every dollar added to a barrel of Crude Oil is another argument for the hawks whose minutes arrive Wednesday.
Minutes first, ministers after
Wednesday's centrepiece is the 18:00 GMT release of minutes from the June FOMC meeting, the first full internal record of the committee under its new Chair. The headline outcomes are already known: rates held at 3.75 percent on a unanimous vote, the median 2026 projection lifted to 3.8 percent, and the easing bias stripped out.
What the minutes can add is texture, chiefly how broad the appetite for an outright hike runs and how the committee weighs energy-driven inflation against a cooling hiring pulse. Futures pricing carries roughly a three-in-four probability of a July 29 hold, with the residual tilted toward a hike rather than a cut and no easing priced for 2026 at all.
The European side of the week is quieter but not empty, with a Governing Council appearance slated for Wednesday at 07:30 GMT, the Eurogroup meeting through Thursday, and another Governing Council speech closing the week on Friday morning. American initial jobless claims arrive Thursday at 12:30 GMT, with consensus at 218,000 against 215,000 previously, alongside a second appearance from the New York Fed chief. None of it outranks the minutes, and little of it will matter if the strait produces another burning hull.
Levels to watch
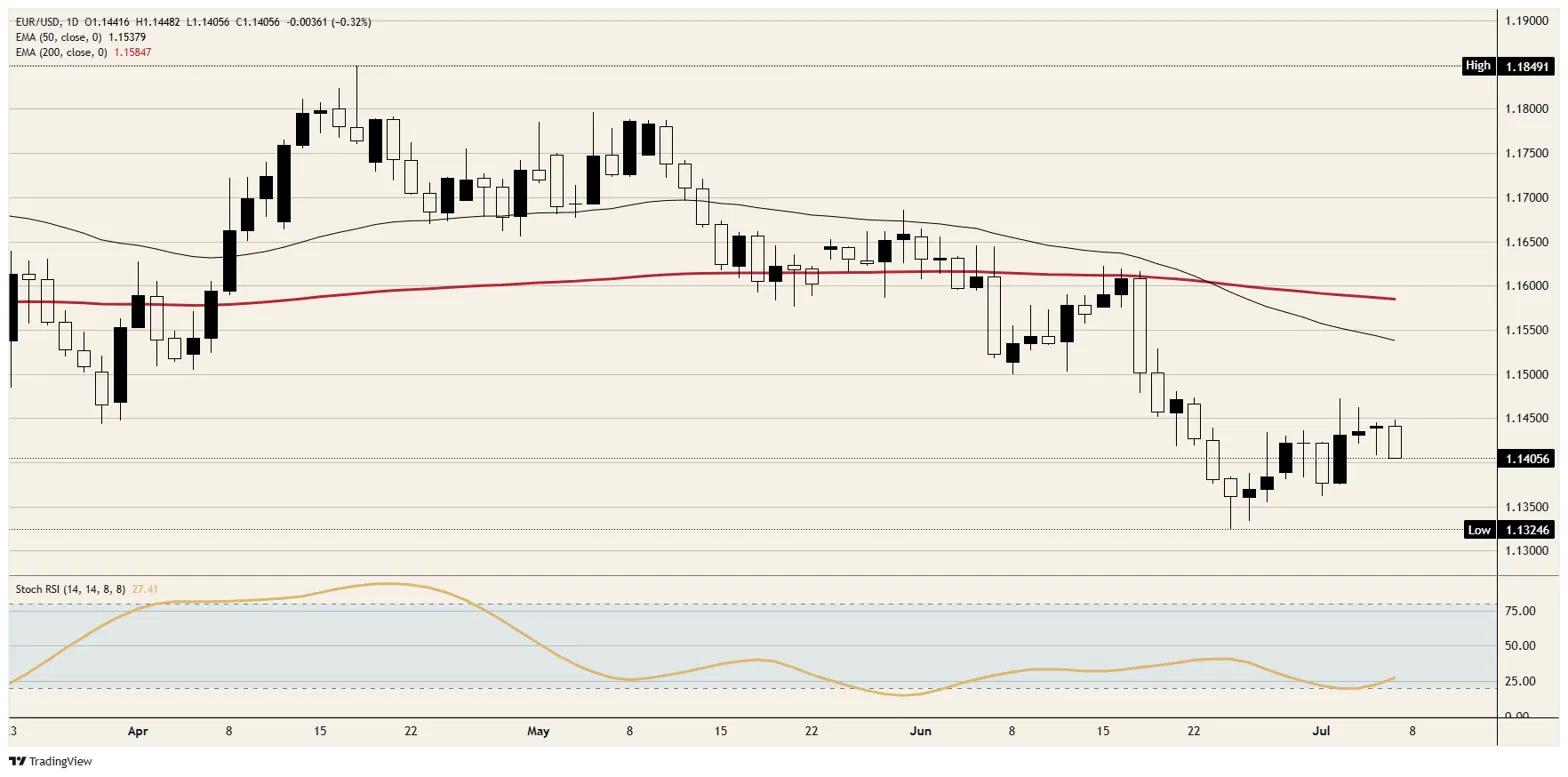
Resistance: Tuesday's rejected ceiling near 1.1450 is the first hurdle, with the 1.1500 round figure behind it and the descending 50-day Exponential Moving Average waiting just shy of 1.1550.
Support: The 1.1400 handle held by a handful of pips at Tuesday's low; beneath it, 1.1350 marks the halfway shelf toward the late-June base sitting just above 1.1300.
Bias: Bearish. Sellers own the tape below 1.1450; the 50-day average crossed beneath the 200-day in late June; a hawkish read of Wednesday's minutes opens 1.1350 on the way to a retest of the June floor near 1.1300. Only a dovish surprise in the minutes or genuine de-escalation in the strait changes that arithmetic.
EUR/USD daily chart
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















