Canadian retail sales give the Loonie a pause at a 19-month low
- USD/CAD slips from a 19-month high after rising in seven of eight sessions.
- Statistics Canada's own early estimate has October retail sales falling 1.5%.
- BoC Governor Macklem speaks Tuesday, with US core PCE and GDP due on Wednesday.

Seven gains in eight sessions took USD/CAD to a 19-month high on Thursday, and Friday's pullback has given back very little of them. The pair has slipped from just above 1.4350 and hasn't traded below Thursday's low. A Canadian retail sales number a tenth above forecast and a softer US Dollar (USD) are behind the move.
The Federal Reserve's (Fed) rate is 3.75%-4.00%, and the Bank of Canada (BoC) lifted its own to 2.50% on October 28. Both decide on December 9, where a quarter-point Fed hike is fully priced and Fed officials have floated a half-point. The gap between US and Canadian two-year yields has widened about a fifth of a point in November, and USD/CAD has climbed with it.
Canadian retail sales rose 0.8% in September, beating the 0.7% forecast, and sales excluding autos rose 1%. Gasoline stations led with a 6.9% gain, volumes rose 0.1%, and Statistics Canada's early estimate for October is a 1.5% fall, so the beat arrived with its own retraction. Crude Oil is heading for a third weekly fall, which removes the other reason to buy the Loonie.
On the calendar
BoC Governor Tiff Macklem speaks at 16:30 GMT on Tuesday, about two weeks before the BoC chooses whether to follow October's hike with a second. Canada's third-quarter current account follows at 13:30 GMT on Friday, November 27.
At 17:15 GMT on Friday, Fed Governor Cook speaks. Wednesday brings October core Personal Consumption Expenditures Price Index (PCE) inflation and preliminary third-quarter Gross Domestic Product (GDP) at 13:30 GMT, with GDP forecast at an annualised 3.4%. Both feed the size of the Fed's December hike, the US side of the gap.
On the charts
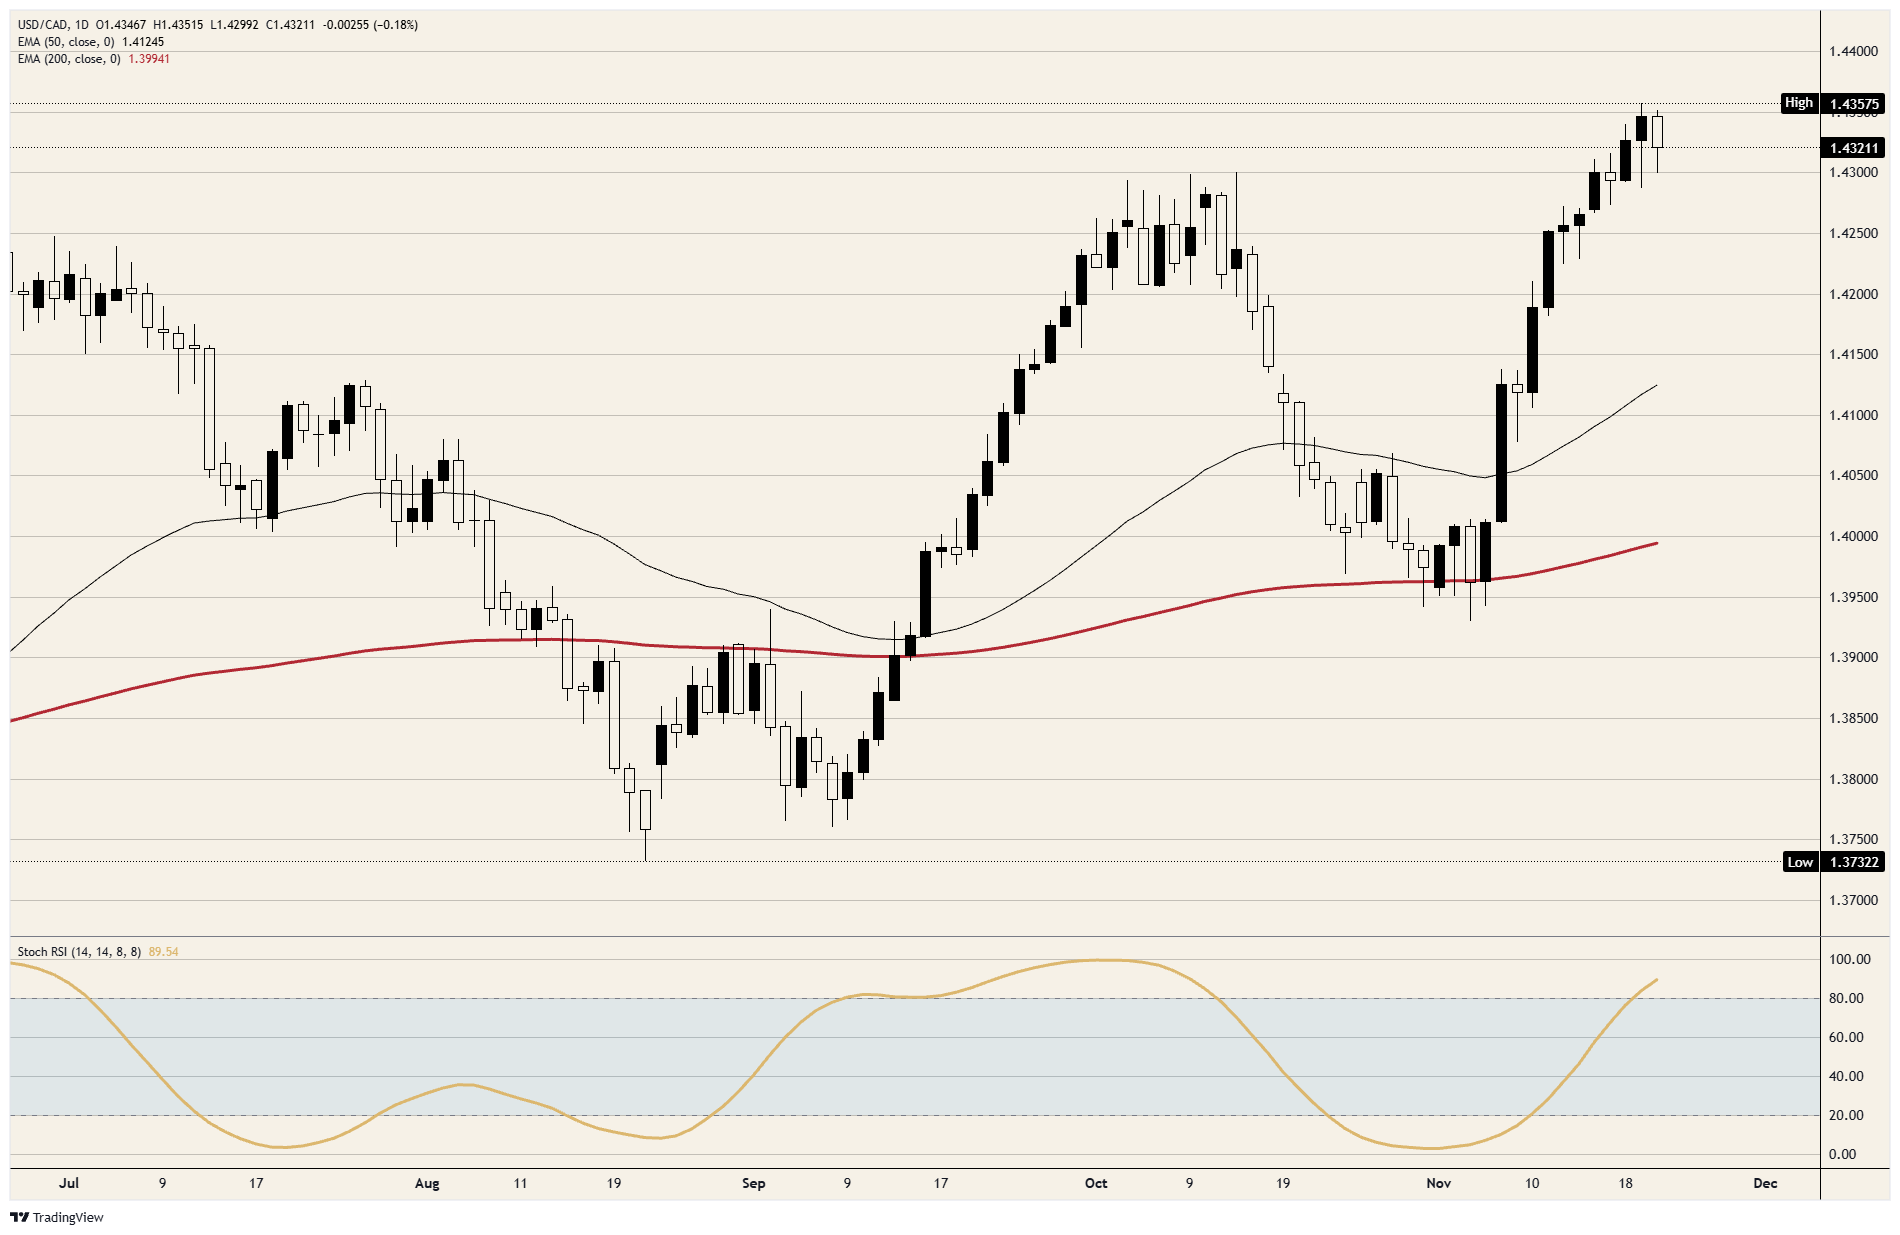
The run started just under 1.3950 on November 4, and Friday's pullback is about a seventh of it. The session low was just under 1.4300, where the pair peaked three times in October. The 50-day Exponential Moving Average (EMA), just above 1.4100, and the 200-day EMA, just under 1.4000, are both rising beneath the pair, and daily momentum is overbought for the first time since early October.
USD/CAD daily chart
Canadian Dollar FAQs
The key factors driving the Canadian Dollar (CAD) are the level of interest rates set by the Bank of Canada (BoC), the price of Oil, Canada’s largest export, the health of its economy, inflation and the Trade Balance, which is the difference between the value of Canada’s exports versus its imports. Other factors include market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – with risk-on being CAD-positive. As its largest trading partner, the health of the US economy is also a key factor influencing the Canadian Dollar.
The Bank of Canada (BoC) has a significant influence on the Canadian Dollar by setting the level of interest rates that banks can lend to one another. This influences the level of interest rates for everyone. The main goal of the BoC is to maintain inflation at 1-3% by adjusting interest rates up or down. Relatively higher interest rates tend to be positive for the CAD. The Bank of Canada can also use quantitative easing and tightening to influence credit conditions, with the former CAD-negative and the latter CAD-positive.
The price of Oil is a key factor impacting the value of the Canadian Dollar. Petroleum is Canada’s biggest export, so Oil price tends to have an immediate impact on the CAD value. Generally, if Oil price rises CAD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Oil falls. Higher Oil prices also tend to result in a greater likelihood of a positive Trade Balance, which is also supportive of the CAD.
While inflation had always traditionally been thought of as a negative factor for a currency since it lowers the value of money, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Higher inflation tends to lead central banks to put up interest rates which attracts more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in Canada’s case is the Canadian Dollar.
Macroeconomic data releases gauge the health of the economy and can have an impact on the Canadian Dollar. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the CAD. A strong economy is good for the Canadian Dollar. Not only does it attract more foreign investment but it may encourage the Bank of Canada to put up interest rates, leading to a stronger currency. If economic data is weak, however, the CAD is likely to fall.
Author
Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















