US Dollar Index Price Forecast: Supported by rising Oil prices
- The US Dollar Index gains further to near 99.90 amid rising Oil prices.
- Traders have trimmed hawkish Fed bets due to weakness in the US labor market.
- Investors shift their focus to the US CPI data, which will be released on Wednesday.

The US Dollar (USD) extends its Monday recovery move on Tuesday, as rising Oil prices due to prolonged fears of energy supply disruption keep global inflation expectations de-anchored.
At press time, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades slightly higher to near 99.90.
Meanwhile, fears of a near-term Federal Reserve (Fed) interest rate hike have eased as the latest United States (US) Nonfarm Payrolls (NFP) data for July revealed a reduction in the overall labor force and a downward revision in labor additions figures of previous months.
Strategists at ING say the latest US labor market data has delivered “clearly dovish and dollar-negative” signals, reinforcing their conviction that the Fed is done hiking. They highlight that, as James Knightley notes, “the -20k payroll print was not the only concern,” with “more than 100k of downward revisions” leaving “average payroll growth at just 20k over the past three months, with health and social care still doing most of the heavy lifting.”
Against that backdrop, ING argues that “our dovish Fed call is strengthening, and so is our bearish bias on the Dollar.” They point out that “despite Friday’s repricing, 11bp are still priced in for September, 28bp for December and 40bp for April,” and conclude that “there remains ample room for dovish repricing to harm the Dollar if we are right about the Fed.”
The CME FedWatch tool shows that the odds of the Fed leaving interest rates unchanged in the September meeting are 48.3%, up from 30.4% seen a month ago.
Going forward, investors will focus on the US Consumer Price Index (CPI) data for July, which will be released on Wednesday.
US Dollar Index Technical Analysis
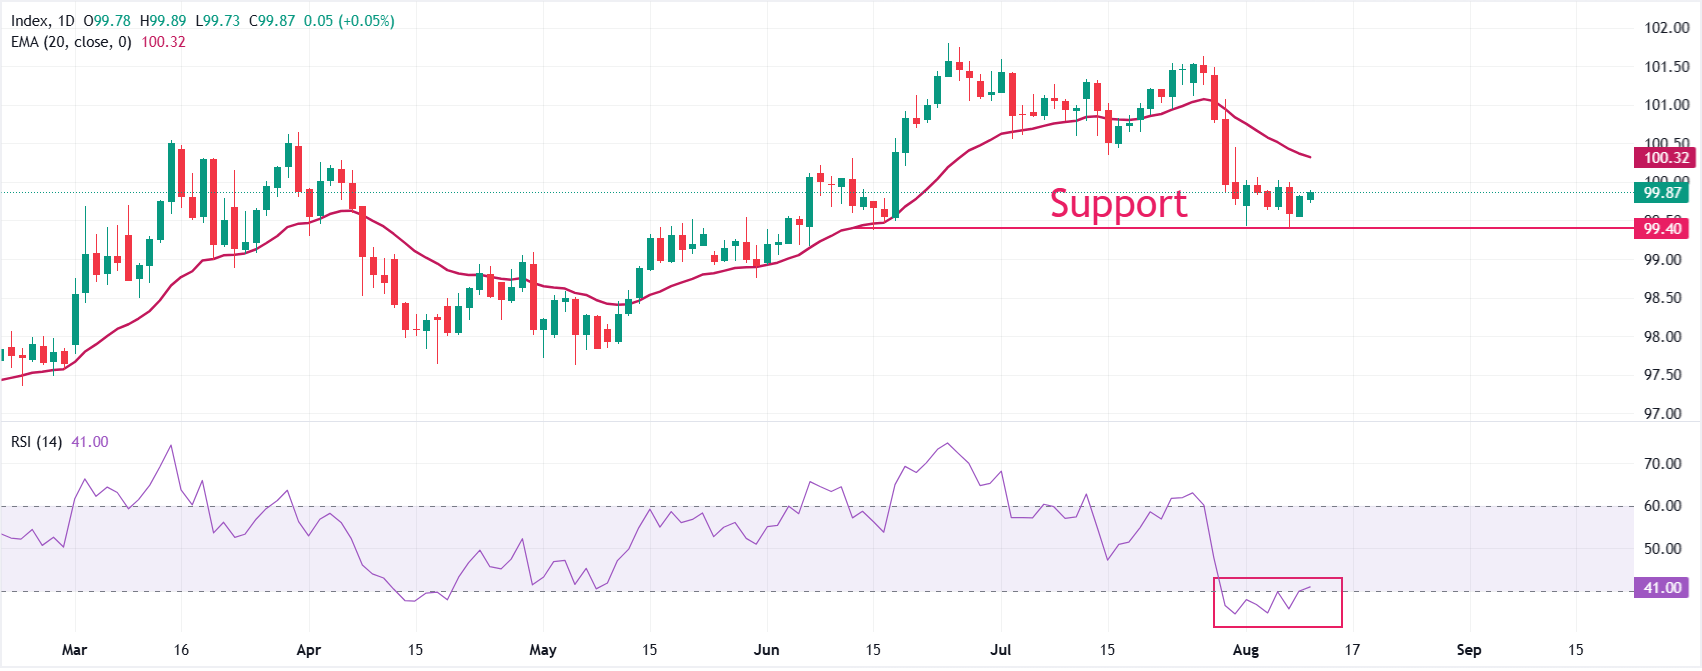
In the daily chart, the Dollar Index DXY trades at 99.87, keeping a bearish near-term tone as it holds beneath the 20-day exponential moving average (EMA) at 100.32. The index has retreated from earlier highs, and the EMA now acts as immediate overhead supply, while the Relative Strength Index (RSI) around 41 shows subdued momentum, hinting at a lack of strong buying interest on current dips.
On the topside, the first hurdle is the 20-day EMA at 100.32, and a sustained break above this level would be needed to ease downside pressure and open the way for a more constructive recovery. On the downside, the US Dollar index could slide towards 99.00 and the May 29 low at 98.75 if it fails to hold Friday's low at 99.40.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.
















