United States Dollar Index approaches 101.80 as bond yields keep rallying
- The US Dollar trades higher against its peers as US Treasury Yields continue to soar.
- Higher energy prices and Fed’s higher for longer interest rates narrative are fuelling US bond yields.
- Fed’s Williams said that inflation is a big concern for the central bank.
The US Dollar continues to outperform its peers as United States (US) Treasury Yields keep rallying due to firm expectations of more interest rate hikes by the Federal Reserve (Fed) in the near term.
As of writing, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades close to its eight-week high of 101.30 posted on Thursday. Meanwhile, 10-year US Treasury Yields are close to its 19-year high of 5.23% posted on Thursday.
The CME FedWatch tool shows an almost 58% chance that the Fed will hike interest rates in both remaining policy meetings this year.
Higher-for-longer Fed expectations drive US yields above 5%
Analysts at ING highlight that US borrowing costs have climbed as markets respond to “elevated energy prices and a belief that the Federal Reserve is set to tighten policy and keep interest rates higher for longer.” They note that, against a backdrop of “substantial government fiscal deficits and anxiety about debt sustainability,” longer-dated US Treasury yields have “pushed above 5%.”
Latest remarks from Fed officials have signaled that they are highly concerned about high inflation and are gaining confident about an improvement in labor market conditions.
Williams flags resilience and inflation risks as Fed tone stays firmly hawkish
Fed’s Williams delivered a notably firm message, with the FXS Speechtracker score at 7.2/10, above the 6.2/10 historical average, underscoring a more hawkish tone relative to the established baseline. Emphasis on “remarkable resilience” in the US economy, receding downside risks to maximum employment, strong AI-related demand, and the “reasonable” prospect of another rate hike by year-end all point to a Fed still focused on taming inflation, even as explicit forward guidance is dialed back and uncertainty over the persistence of higher yields is acknowledged. The combination of strong demand, inflation concerns, and openness to further tightening is supportive of the Dollar, while the shift away from rigid guidance injects more rate-path uncertainty into FX pricing.
The FXS Fed Sentiment Index slipped by 0.18 points to 148.63, a modest pullback that still leaves the gauge deep in hawkish territory well above the neutral 100 mark. Despite the slight decline, the elevated index level, in tandem with the stronger-than-average FXS Speechtracker score, confirms that Fed communication remains broadly supportive of the Dollar, even as markets reassess the durability of higher yields.
US Dollar Index Technical Analysis
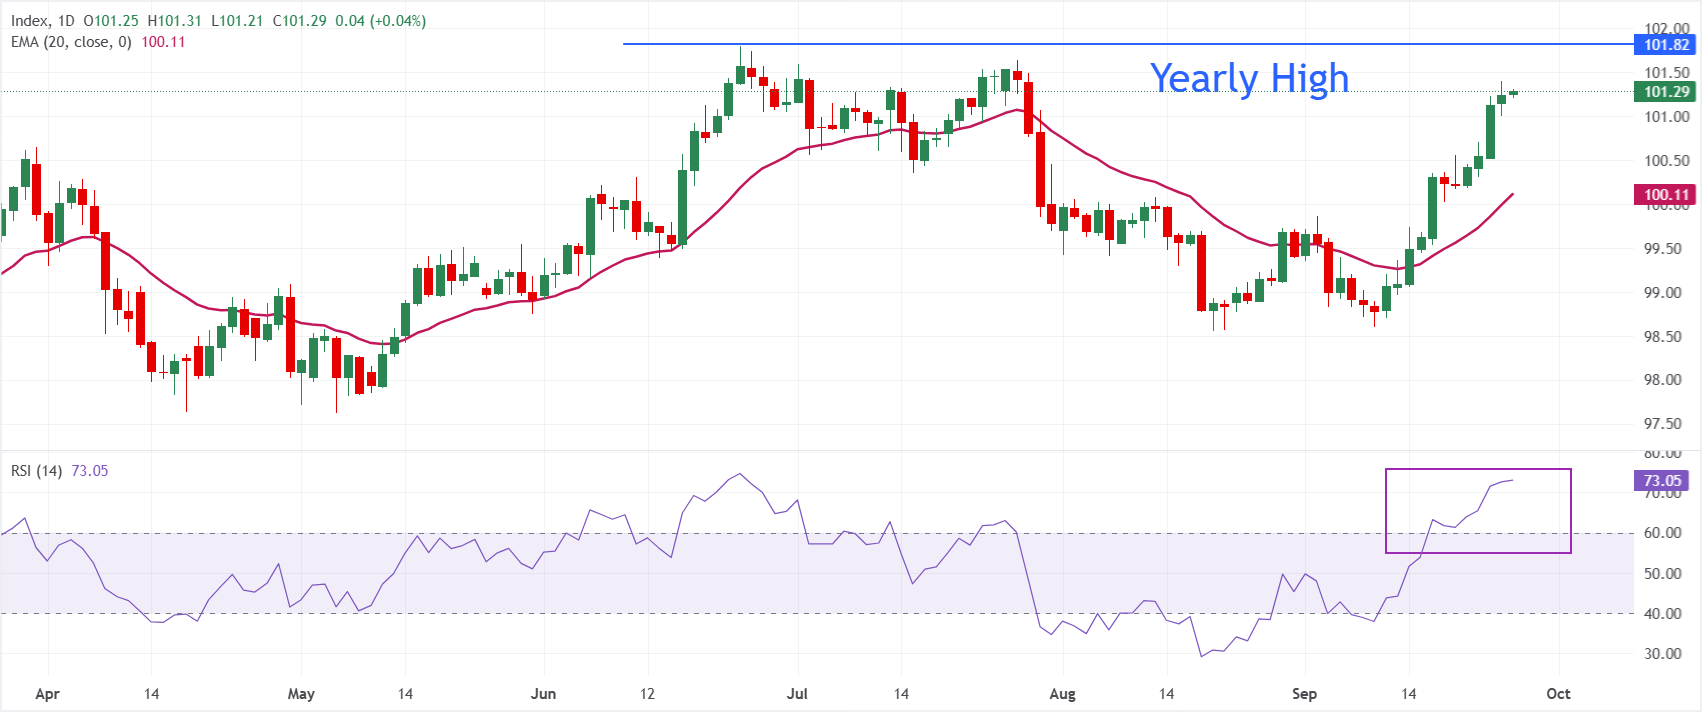
In the daily chart, Dollar Index Spot trades at 101.29. The near-term bias is bullish as price holds above the 20-day exponential moving average (EMA) at 100.11, reinforcing a constructive tone after the recent advance from sub-99.00 levels. However, the Relative Strength Index (14) at 73.05 has entered overbought territory, suggesting upside momentum is strong but vulnerable to a corrective pause or consolidation in the sessions ahead.
On the downside, immediate support is seen at the current pivot area near 101.29, with stronger underlying demand emerging at the 20-day EMA around 100.11, where buyers could attempt to defend the broader recovery structure. Looking above, the ongoing rally in the DXY could find hurdle near the yearly high at 101.80
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.