Week ahead – Summer lull could be tested by geopolitics and central bank expectations
- US dollar stabilizes as September Fed hike bets remain subdued.
- Market volatility stays low, but thin liquidity could amplify movements.
- Key UK data could challenge pound strength; euro craves bullish catalysts.
- Middle East tensions could upset markets; yen weakness persists.
Dollar gains, equities trade sideways but bond yields rise
It has been a relatively monotonous week, with the US dollar desperately trying to recover from last Friday’s nonfarm payrolls-induced losses, the main equity indices trading mostly sideways amidst a quiet earnings calendar, and sovereign bond yields reminding everyone of their pivotal role in the current financial system.
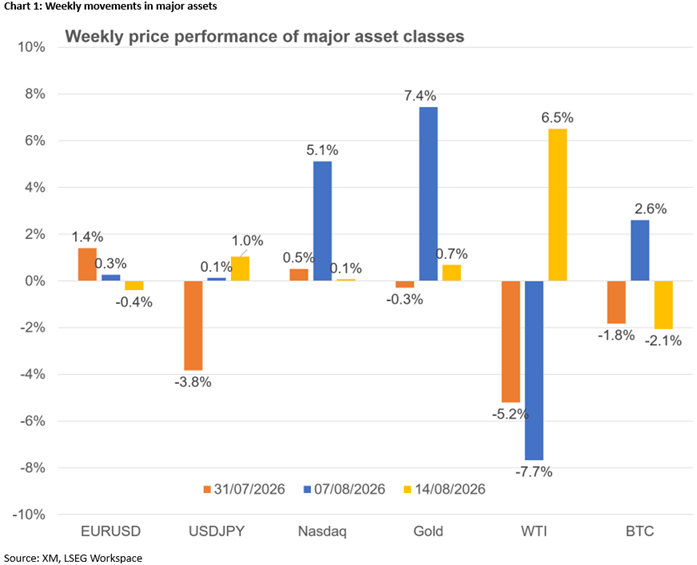
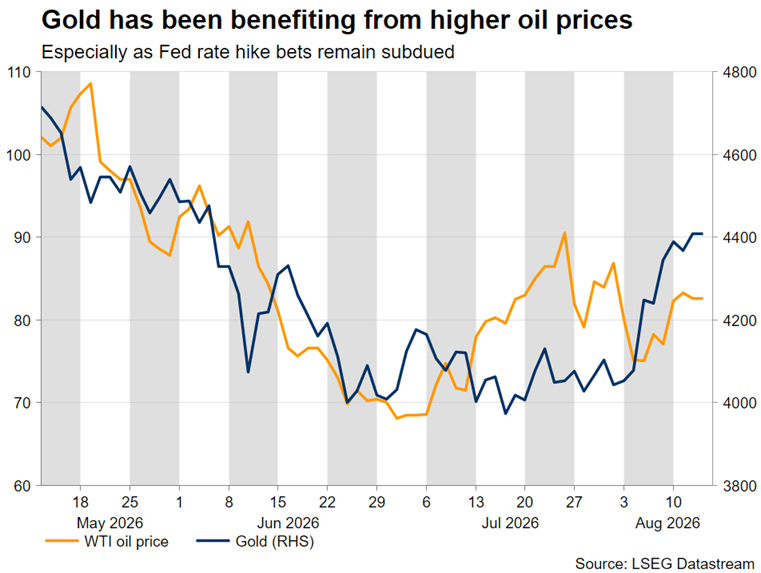
These market moves are partly connected to the Middle East developments. At the time of writing, an interim US-Oman-Iran agreement remains elusive, increasing the chances of fresh military operations. Oil prices remain elevated, with the December 2026 WTI oil futures contract clearly pointing to elevated uncertainty and angst.
The main derivative of the oil price rollercoaster is the softer Fed rate hike expectations, with the September hike bets hovering below 50% despite Fed hawks coming out in force. Wednesday’s July US CPI report failed to produce an upside surprise, with the Jackson Hole Symposium gradually gaining importance.
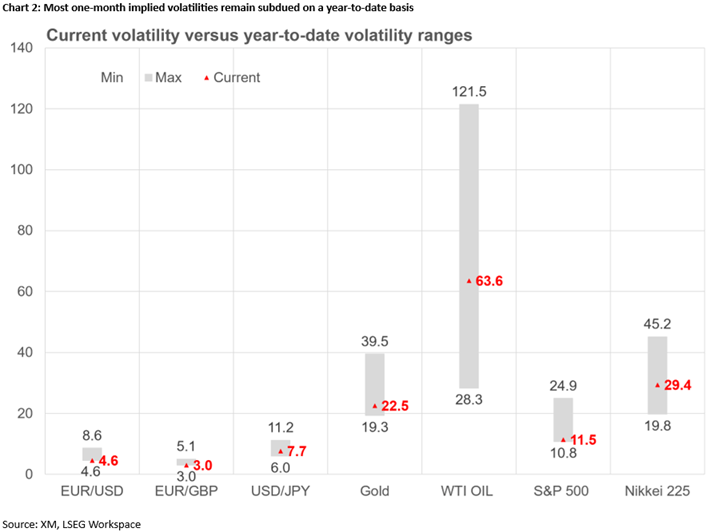
Interestingly, with the exception of yen crosses, the Nikkei 225 index and WTI oil, one-month implied volatilities for most assets are near year-to-date lows. This confirms the current low appetite for aggressive positioning amidst the summer lull and thin liquidity conditions.
Light US data calendar, but the September hike bets will remain in focus
Investors will have to make do with a less impressive data calendar next week. Numerous housing data releases, key business surveys such as the Philadelphia Fed Manufacturing survey and the S&P Global PMIs will offer valuable insight into the Fed’s next action.
But the most important event might prove to be Wednesday’s release of the July 29 FOMC meeting minutes. While usually treated as an out-of-date event, the minutes could offer a clearer view of the hawkish sentiment within the committee. A hawkish set of minutes could add further weight to the hawkish voices calling for a September rate hike and boost the US dollar. We already heard from Cleveland’s Hammack and Minneapolis’ Kashkari, who dissented at the July 29 Fed meeting, and a number of non-voters like St Louis’ Musalem, Boston’s Collins and Dallas’ Logan supporting rate hikes.
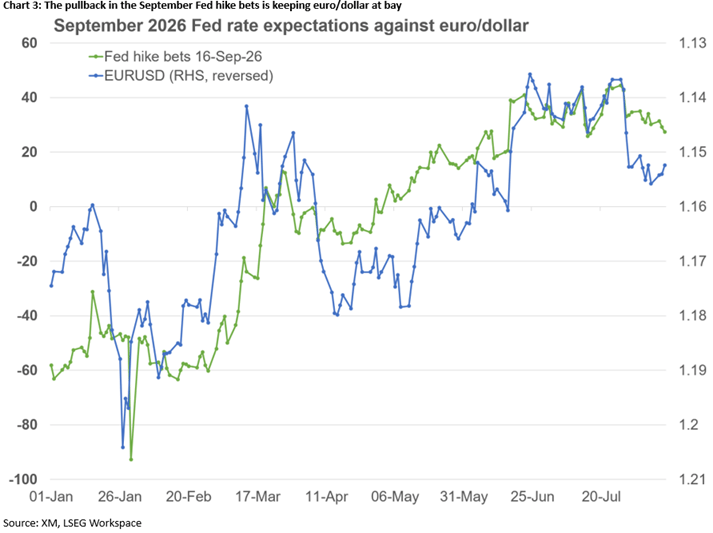
As Chart 3 above shows, the probability of a rate hike in September has dropped aggressively lately, keeping the dollar under pressure, while the first 25bps move is currently fully priced in for December, a significant adjustment from mid-July.
The FOMC voting committee is dominated by dovish members, thus making it even more difficult for hawks to push through their opinions, unless Chair Warsh decides to pick a side. Crucially, the countdown to the late-August Jackson Hole Symposium has commenced, where Warsh might have to choose between opening the door to a September rate hike or just setting out his priorities for the following 12 months.
Could pound strength be challenged by UK data?
The pound has been showing unexpected strength against both the dollar and the euro since July 29, with investors probably forgetting the dovish rhetoric from BoE Governor Bailey and the reduced chances of BoE rate hikes in the remainder of 2026. One rate hike is currently priced in for December, down from 49bps of tightening expected ahead of the July meeting.
Key labour market data, the July CPI and PPI reports, the July retail sales figures and the preliminary PMI surveys for August are expected to keep pound traders exceptionally busy next week. Obviously, Wednesday’s CPI report stands out, as an upside surprise in the core indicator could prove to be the most market-moving event.
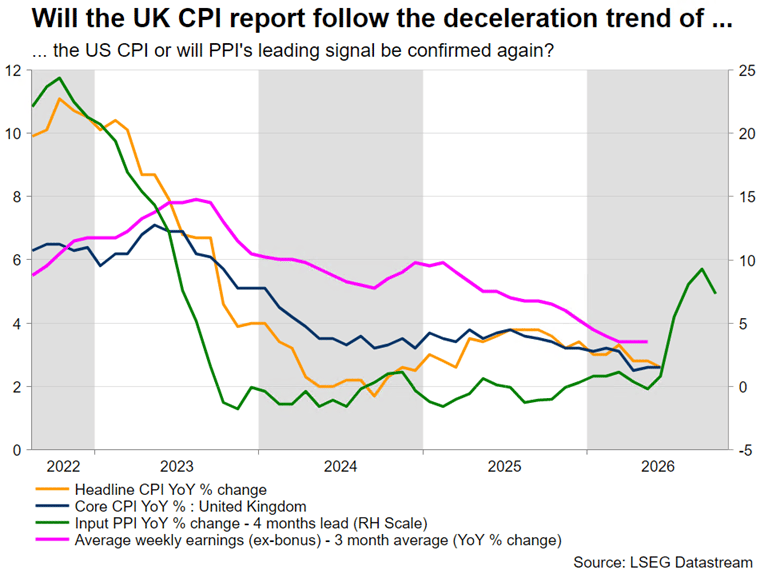
Core inflation has been stabilizing at current levels, ignoring the persistent deceleration seen in the headline figure. An acceleration towards 3% could upset market expectations and further boost the pound mostly against the euro, but also against the dollar if Fed hike bets remain subdued. Crucially, euro/pound is hovering at the critical area of 0.8530, with a potential drop towards 0.8504 opening the door to a retest of the one-year low of 0.8454.
Could bullish catalysts arise for the euro?
The euro has gained around two big figures since late July against the dollar, fully capitalising on the greenback’s broader weakness. However, euro-based bullish catalysts remain scarce, with expectations for a September ECB hike being the euro’s main tailwind.
With ECB members taking advantage of the summer lull, next week’s preliminary PMI surveys could test the current euro strength. A significant weakness in the PMIs, signalling weaker growth momentum, could raise questions about the ECB’s next steps. An upset to the current solid September hike bets could prove market-moving, challenging the euro’s gains, as market tightening via higher bond yields might prove sufficient for many ECB members.
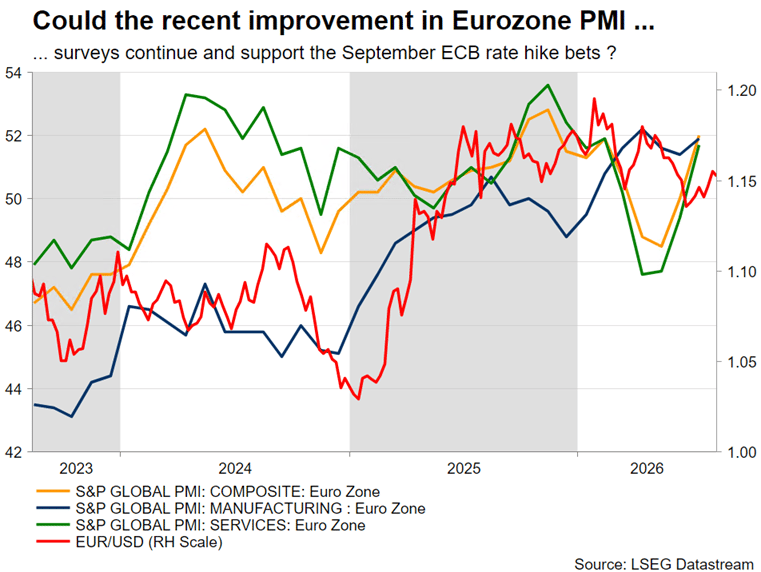
At the end of the day, though, the ECB’s actions depend on Middle East developments. The lack of an interim agreement could overshadow data releases and maintain the ECB’s current course of action, supporting the euro. In the low-probability scenario of positive news from the Oman-Iran negotiations, weaker eurozone data could offer a way for the ECB doves, thus denting the euro’s appeal. A drop towards the lower boundary of the recent one-year-long range at 1.1470 could be on the cards for euro/dollar, with moves potentially amplified by the lighter liquidity conditions.
Middle East in the spotlight, Yen suffering persists
Iran’s additional demands about reopening the Strait of Hormuz have stalled negotiations for an interim agreement. While President Trump is eager to close this chapter and focus on the midterm elections, a restart of hostilities is still on the table. In this case, oil prices could quickly climb to recent highs, and even threaten a return to the triple-digit territory.
The latter could be the final nail in the coffin for the late July yen intervention. Unsurprisingly, with dollar/yen potentially flirting with 160 again, we are witnessing a repeat of the previous BoJ interventions when the engineered dollar/yen drop was followed by a consistent rally.
Japanese officials are apparently trying to buy time, hoping that the US dollar will eventually start to weaken, while also mistakenly expecting that domestic firms will repatriate their funds and invest in Japanese bonds. All in all, the yen remains at the mercy of the markets, despite some growing expectations for a September BoJ hike.
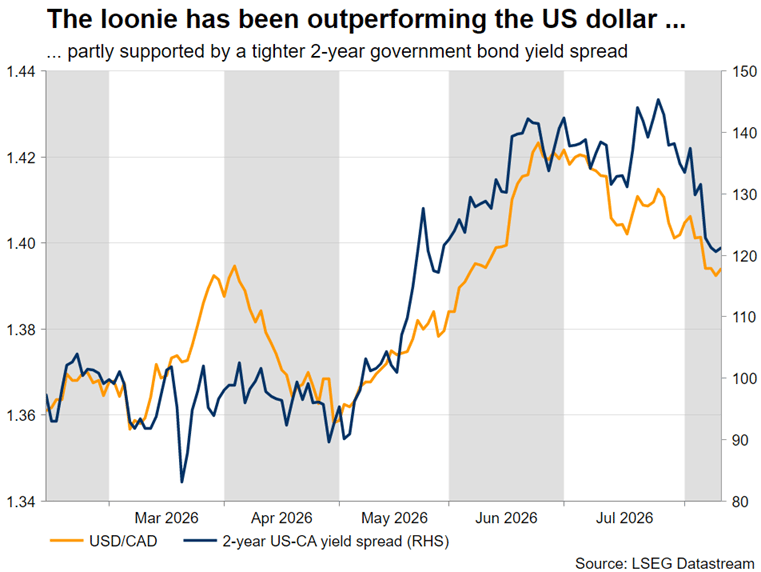
Interestingly, both the aussie and the loonie have been outperforming the US dollar since June 24. Next week, the loonie’s strength could be challenged by a plethora of data prints, especially Monday’s CPI report. Compared with the neighbouring US, inflation has been well behaved, with core inflation gradually easing to 2.1%.
However, the loonie’s biggest test will probably be the August 19 tariff deadline set by Trump to impose 50% tariffs on certain Canadian imports. If no agreement is reached between the US and Canada, the loonie could be under severe pressure, with a move towards 1.4000 being on the cards.
Gold, equities in auto-pilot mode
The softer Fed rate hike expectations have given both US equity indices and gold some valuable breathing space. While equities are drifting higher, powered by an impressive earnings season, the precious metal is posting gains for the second straight week for the first time since mid-April. A potentially aggressive dollar rally could really test the viability of the current upside move in gold, challenging the gold bugs’ renewed optimism for a retest of $4,500 ahead of the Jackson Hole Symposium.
Author

Achilleas joined Trading Point in November 2022. He holds a BSc in Business Economics from Middlesex University and a MSc in Mathematical Trading and Finance from Bayes Business School, City University.

















