US bond yields steady ahead of Fed decision, US Dollar Index rally stalls


AUD Falls on Dovish RBA Rate Hike, USD/JPY Edges Higher
Summary
US bond yields steadied with the benchmark 10-year rate settling above the key 4% threshold, at 4.05% (4.0% yesterday). The 2-year bond rate climbed to 4.55% (4.44% yesterday).
Economic data released yesterday saw the US JOLTS Job Openings jump to 10.72 million from a previous upward revised 10.25 million (from 10.05 million), and median forecasts at 9.25 million.
Analysts expect the Fed Open Market Committee (FOMC) to hike the Federal Funds Rate by 75 basis points to 4.00% at the conclusion of their meeting at 5 am Sydney time tomorrow 3 November).
The Dollar Index (DXY), a popular gauge of the Greenback’s value against a basket of 6 major currencies, eased to finish at 111.53 after soaring to 111.78 overnight.
FX volatility remained elevated with most major currency pairs trading beyond 100-point ranges. The Euro (EUR/USD) steadied to 0.9875 after climbing to an overnight peak at 0.9953 and a recorded low at 0.9853. Against the Japanese Yen, the US Dollar finished at 148.18, up from yesterday’s 147.57.
The RBA hiked its Cash Rate to 2.85% from 2.60%, considered dovish by FX traders. As a result, the Australian Dollar (AUD/USD) tumbled to close at 0.6395 after earlier soaring to a high at 0.6464.
New Zealand’s Kiwi (NZD/USD) was more subdued, easing to 0.5838 (0.5870 yesterday). Sterling (GBP/USD) settled at 1.1485 (1.1530) after plunging to an overnight low at 1.1437 in choppy trade.
Against the Asian and Emerging Market currencies however, the Greenback was mixed. The USD/THB pair (Dollar-Thai Baht) dipped to 37.75 from 38.05 while USD/CNH (Dollar-Offshore Chinese Yuan) edged higher to 7.3050 (7.2850).
Wall Street stocks eased modestly. The DOW was last at 32,603 from 32,845 yesterday while the S&P 500 dipped to 3,850 (3,890). Other global equities finished with mixed results.
Global bond yields edged up. Germany’s 10-year Bund yield climbed to 2.13% from 2.11% yesterday. The UK’s ten-year Gilt yield eased to 3.46% (3.50%). Australia’s 10-year bond rate was flat at 3.76%.
Other economic data released yesterday saw China’s Caixin Manufacturing PMI in September soar to 49.2 from 48.1, beating forecasts at 48.5.
Germany’s Import Prices plunged to -0.9% from a previous 4.3% and forecasts at 0.7%.
UK Nationwide House Price Index fell to -0.9% from 0.00%, lower than estimates at -0.4%.
UK Final Manufacturing PMI rose to 46.2 from a previous 45.8 and expectations at 45.8. Canada’s Final Manufacturing PMI slid to 48.8 from 49.8, and lower than forecasts at 49.9.
US Final Manufacturing PMI rose to 50.4 from 49.9, beating estimates at 49.9. The US ISM Manufacturing PMI dipped to 50.2 from 50.9 and estimates at 50.0.
US Construction Spending rose to 0.2%, up from -0.6%, beating estimates at -0.5%. US ISM Manufacturing Prices slid to 46.6 from a previous 51.7 and lower than forecasts at 53.0.
-
EUR/USD – The shared currency steadied to finish at 0.9875 at the close of New York. Overnight, the Euro soared to a high at 0.9953 before sliding at the finish. Trading was volatile with the overnight high traded at 0.9953. Markets were looking to the US Dollar to provide the next big move for the EUR/USD pair.
-
AUD/USD – Following the RBA’s “dovish” hike of 0.25 basis points on the Cash Rate, the Aussie Battler tumbled to finish at 0.6395 (0.6440 yesterday). RBA Governor Philip Lowe said that the “board has judged it appropriate to raise rates at a slower pace”, which was the red flag that brought on sellers. Overnight low traded for the Aussie was at 0.6377.
-
USD/JPY – The Greenback grinded higher against the Japanese currency to finish at 148.18 from 147.57 yesterday. The rebound in US bond yields lifted the USD/JPY pair. Overnight high traded was at 148.83. In another volatile session, the overnight low recorded was at 146.99. Japanese JGB treasury yields were unchanged.
-
GBP/USD – After being pounded in the last few trading sessions on developments in the UK political scene, Sterling settled to finish at 1.1485. Overnight trade was volatile with the low recorded at 1.1437. The British Pound saw a high at 1.1566 in European trade. A lower than forecast fall in the UK Nationwide House Price Index weighed on Sterling.
On the lookout
Ahead of tomorrow morning’s huge FOMC meeting outcome, today’s economic calendar is significant.
New Zealand kicked off earlier with its Q3 Employment Change, which beat estimates at 0.5%, climbing to 1.3% (previous 0.0%). New Zealand’s Unemployment Rate, however climbed to 3.3% against analyst’s estimates at 3.2% (previous 3.3%).
Following the release, the Kiwi (NZD/USD) edged higher to 0.5843 from its NY close at 0.5839.
Australia followed with its AIG Manufacturing Index which climbed to 49.6 against forecasts at 49.4, lower than a previous 50.2.
The Aussie Dollar (AUD/USD) was little changed, at 0.6392 (0.6395 open).
Australia also releases its Preliminary September Building Permits (m/m f/c -7% from 28.1%; y/y f/c -10.2% from -9.5%).
Watch this number as the forecasts vary widely from the previous data. Germany kicks off Europe with its Harmonised September Unemployment Rate (f/c 3% from 3%).
Next up is Germany’s September Trade Balance (f/c +EUR 1.4 billion from a previous +EUR 0.6 billion).
Germany also releases its October Unemployment Rate (f/c 5.5% from 5.5%), German October Global Manufacturing PMI (f/c 45.7 from 47.8).
The Eurozone follows with its Euro Area October Global Final Manufacturing PMI (f/c 46.6 from 48.4).
Watch this number too, forecasts are far from the previous number.
The US rounds up today’s data releases with its October ADP (Private Jobs) Employment Change (f/c 193K from previous 208K).
This is an important number as well, the ADP Jobs report is normally a preview of the NFP report, due this Friday.
Trading perspective
The data dump continues this week culminating in Friday’s US Payrolls report.
Traders will focus on the US ADP Private Payrolls report released tonight as a preview for the NFP. Last night’s US JOLTS (Job Openings) which bettered analysts forecasts have bid the US currency.
Ahead of Friday’s NFP report though, the Dollar’s rally stalled, which is to be expected.
Mounting inflationary pressure continue to challenge the US Federal Reserve.
Expectations at this point forecast for a rate hike in the Fed Funds to 4% from the current 3.25%.
Much will also depend on the comments from Fed Chair Jerome Powell as well as the Fed’s future (dot plot) estimates of policy.
Expect the Dollar Index (DXY) to stay steady with bouts of profit-taking to prevent any sharp rallies.
-
USD/JPY – Against the Japanese Yen, the Greenback grinded higher to finish at 148.18 from 147.57 yesterday. In choppy trade, the overnight high recorded was at 148.83. Earlier in the session, the USD/JPY pair tumbled to a low at 146.99. The climb in US bond yields enabled the Greenback to rally against its Japanese counterpart. Immediate resistance today lies at 148.50, 148.80 and 149.10. Immediate support is found at 147.85, 147.55 and 147.25. Look for more choppy trade, likely between 147.50 and 148.70 today. Prefer to buy USD dips.
-
EUR/USD – The shared currency dipped against the US Dollar, settling at 0.9875 from yesterday’s opening at 0.9925. Overnight the Euro slid to a low at 0.9853. Trade was also choppy in this currency pair, the high recorded at 0.9953. Immediate support lies at 0.9850 and 0.9820. On the topside, look for immediate resistance at 0.9910, 0.9940 and 0.9970. Look for consolidation in a likely trading range today of 0.9850-0.9950. Trade the range, there’s a good 100 pips in it.
-
AUD/USD – The Aussie Battler tumbled after the RBA delivered what many traders saw as a dovish hike of 25 basis points in the Overnight Cash Rate to 2.85%. With the US Fed Funds rate currently at 3.25%, and the likelihood of an increase to 4.0%, the widening differential between US and Australian 10-year yields will continue to weigh on the AUD/USD pair. The Aussie Dollar closed at 0.6395. Immediate support lies at 0.6370, 0.6340 and 0.6310. On the topside, immediate resistance lies at 0.6420, 0.6450 and 0.6480. Its all about the US Dollar from hereon in. The AUD/USD pair looks shaky. Likely range 0.6350-0.6450.
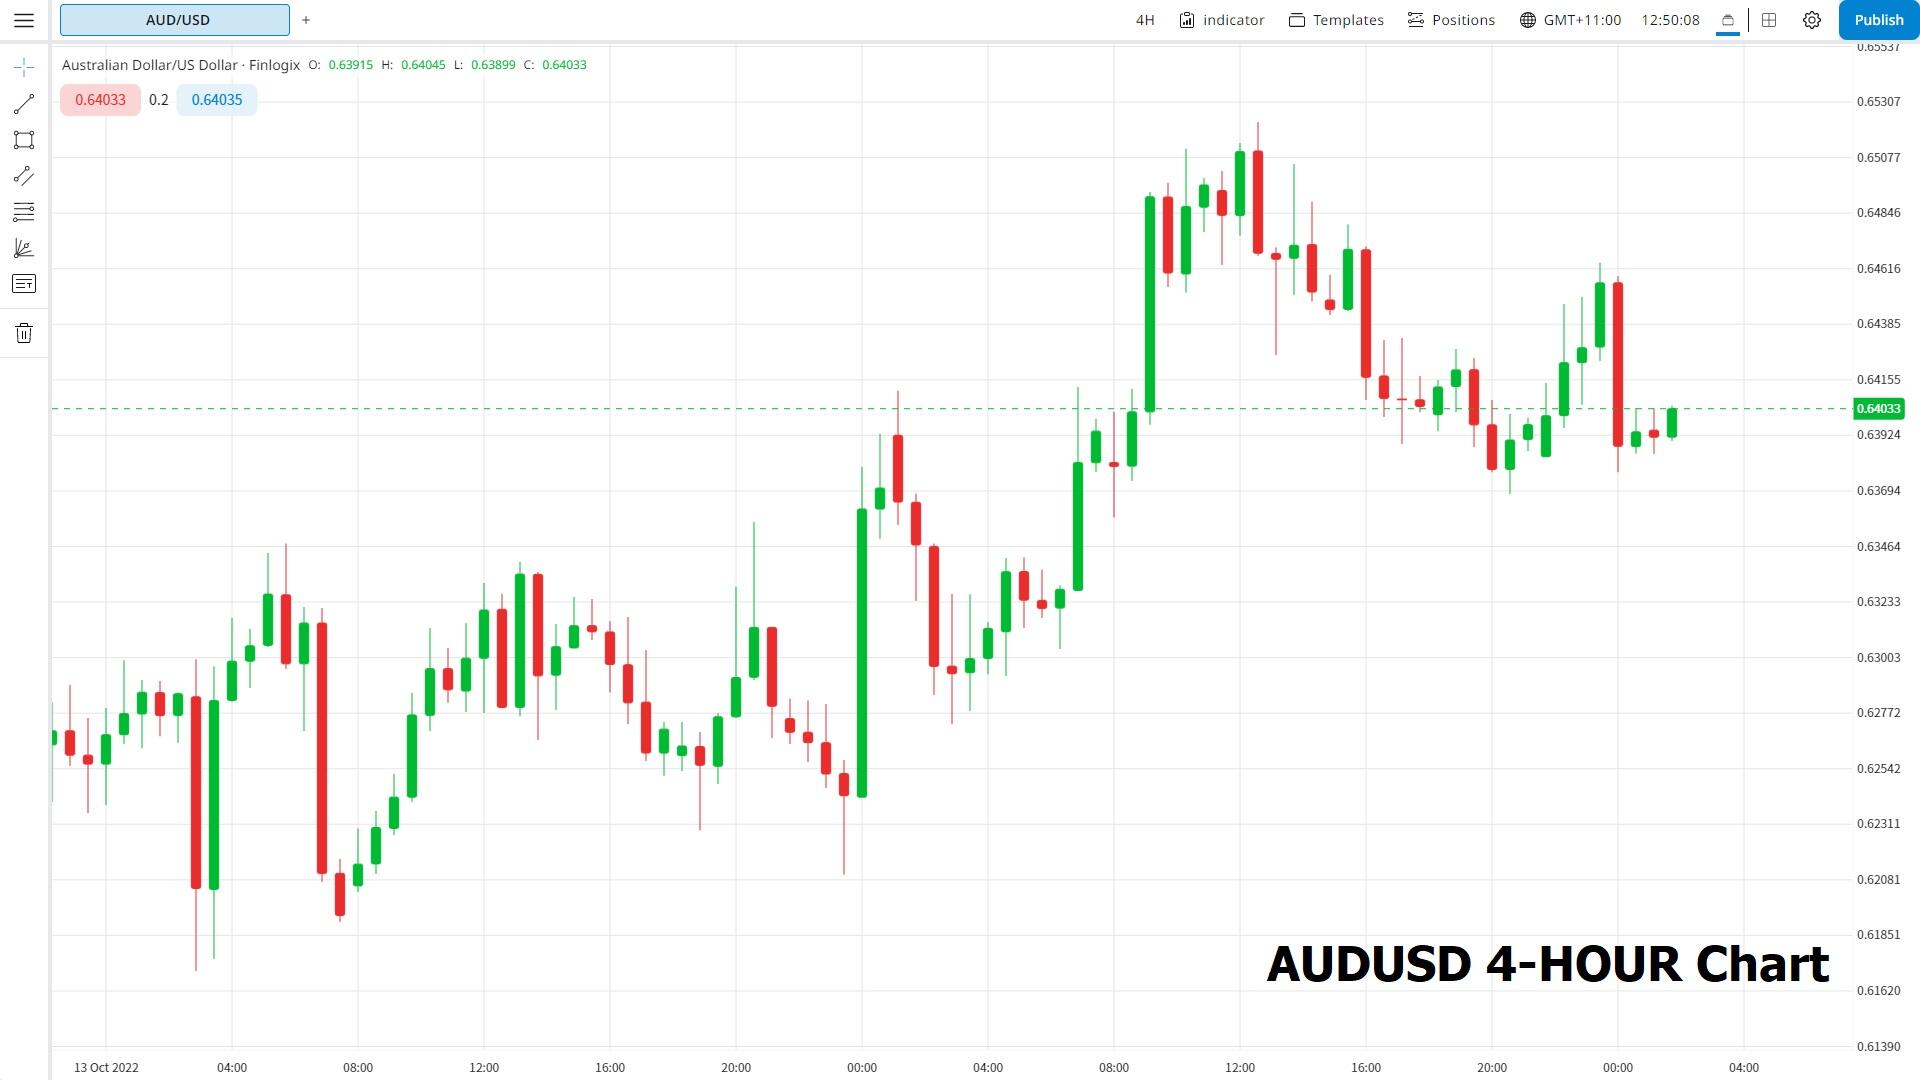
(Source: Finlogix.com)
- GBP/USD – Sterling eased to finish at 1.1485 from 1.1530 yesterday. The GBP/USD pair saw a low at 1.1437. Today, look for immediate support at 1.1450, 1.1420 and 1.1390. Immediate resistance lies at 1.1510, 1.1540 and 1.1570. The British currency has rebounded from its low 1.0960 three weeks ago to a high at 1.1630 last Friday. Look for consolidation today, likely between 1.1430-1.1550. Prefer to sell rallies, the British Pound is not quite out of the woods yet.
Have a good trading day ahead, happy Wednesday all.
Author
Michael Moran
ACY Securities
Michael has over 40 years’ FX experience, including running FX trading desks for some of the largest banks in the world.

















