UK Coronavirus infections and deaths projections trend forecast into end April 2020
US and UK Case Fatality Rate Forecast for End April 2020
The US AND France are on a similar trend trajectory of under testing, thus as I have been warning for a month now that the US has probably a huge pool of infected, circulating and doubling every 3 or 4 days. That I estimated 2 weeks ago to be about ten times the official number to total at least 4000. Where US current tally of 23,000 suggests that the actual number of infected could easily exceed 250,000, more than ten fold the recorded infected number due to the fact the US IS STILL NOT TESTING ENOUGH!
110,000 tests to date is a mere pinprick, the US should be testing that number EVERY DAY!
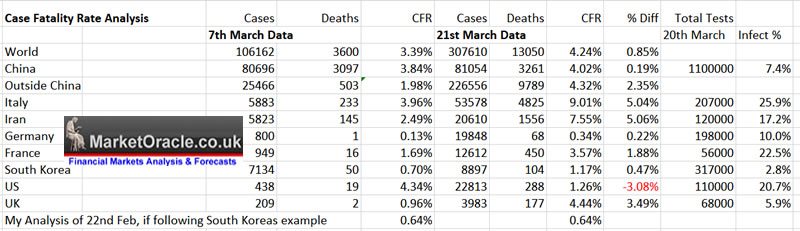
Thus the current US CFR rate of 1.26% that many are cosying upto for comfort is NOT RELIABLE! Not when we look at Italy, France and the UK amongst which the US is most likely to emulate rather than South Koreas 1.17%
So people in the United States should not be lulled into any false sense of security by today's low CFR rate as it is purely as a consequence of continuing gross negligence in testing. The only advantage the US has time, maybe 2 weeks ahead of the UK and 4 weeks ahead of Italy, so at an advantage to act now to prevent catastrophe and avoid Italy's' fate, though with over 250,000 infected roaming the streets a lot of deaths are already baked into what happens over the next 2 weeks.
Therefore this analysis resolves in the US targeting a CFR rate of 4% when the US curve starts to flatten during early May. Though this means the CFR will be higher at the April 2020, probably at about 5%.
Whilst the UK's CFR of those tested rocketed from 1% to to 4.4% and given my earlier analysis is on a steeper trend trajectory than Italy! So implies a just as bad outcome as Italy! However the UK still has 2 weeks to ACT, and this week we saw the Government panic to act. Nevertheless the UK is heading for a CFR spike that could be as bad as Italy's 9% before it starts to flatten out and moderate towards the end of April as the UK has wasted valuable time and acted LATE, which will cost lives. So it is highly probable that UK's CFR by end of April will be at about 6.6%.
UK Coronavirus Trend Forecast Into End April 2020
The UK government started the ball rolling in announcing a number of measures in attempts at slowing the parabolic curve that the pandemic was on, first of which was to close all schools as of Friday 20th March, which in my opinion was about 2 weeks later than they should have closed the schools. Still in terms of pandemic time line it is about 5 days ahead of when Italy closed all of their schools, so 'should' help resolve towards a better outcome.
The second announcement was to order all restaurants, pubs and clubs to close. Again a positive development and ahead of the curve in relation to where Italy was. However, just firmly asking the British people to stay at home has largely fallen on deaf ears as most have carried on as usual given the weekends mad rush to enjoy the sunshine by flocking to parks, countryside and seaside in their millions! Huge crowds busy mingling and infecting one another which does not bode well for what to expect in terms of infection numbers 1-2 weeks down the road.
So the key mistake that the UK has made is NOT to order a national lock down on the 20th of March. And with every day that Britain delays announcing a lock down is going to result in a steeper curve, thus Britain needs to announce a national lock down immediately as delaying it by 4 or 5 days will just put Britain precisely on the same track as Italy.
So I expect an IMMINENT UK national lock down. Which like earlier school closures than Italy should give the UK a small advantage in terms of pandemic outcomes. BUT first they have to actually announce the lock down which as of writing there is little sign of, perhaps the lock down will come Monday or Tuesday? Anyway each day delayed takes the UK one step closer to becoming Italy.
So the UK Government after following a policy of herd immunity has finally acted to subdue the inevitable surge that is already baked into what is to transpire over the next 2 weeks, so this weeks actions will impact on what to expect for April rather than for the remainder of March which is going to be pretty bad as the number of officially recorded infections are set to soar, with likely hidden infections running at least X30 the official numbers, which means there are going to be a lot of infected people out there hence the need to lock down.
The UK is literally sat at the very start of the stage where hospitals start to become quickly over run due to lack of capacity despite having had near 8 weeks to prepare, the NHS and government basically did nothing until they started to witness the catastrophic unfolding in Italy earlier this month.
Whilst lack of action in preparing the NHS won't effect the numbers infected, other than the fact that the UK is not testing enough people thus the actual number of infected will likely be more than X20 the official number, I could guess at X30 i.e. today's 5000 resolves to about 150,000 infected, which translates into about 7,500 seriously ill patients of which 2,500 would be critically ill, all heading for the NHS that perhaps has beds for only 2,000 critically ill, given that the NHS is planning to be up and running with 5,000 critically ill and 30,000 high dependency beds by 15th of April! Instead they will likely need that number long before the end of this month!
So this suggests Britains case fatality rate of 4.4% is going to rocket upwards and beyond Italy's 8.8%. In fact the UK could be about to witness a shockingly high CFR of more than 10%! WORSE THAN THAT OF ITALY! Before it starts to moderate by mid April as more beds come on stream and likely the army is deployed.
So I expect the situation in the UK to become pretty disastrous by the end of March and remain so until around Mid April with a case fatality rate in the region of 9% of reported cases before slowly moderating into the end of April.
In terms of the number infected, well the UK is pretty much on a similar trend trajectory as Italy where the existing trend trajectory is for 17,000 by the end of March, which suggests that the UK is gong to trend to more than 100,000 by the end of April, and probably exceed Italy's total by a good 20,000 given that the temperatures are colder here with less sun, so the virus can survive for longer on surfaces. Therefore my final conclusion is that the UK is targeting a trend to 123,000 officially recorded infections by the end of April 2020, which on a CFR of 6.6% resolves to 8,100 deaths, that compares against today's figure of 233 with the trend trajectories as illustrated by my following forecast graph.
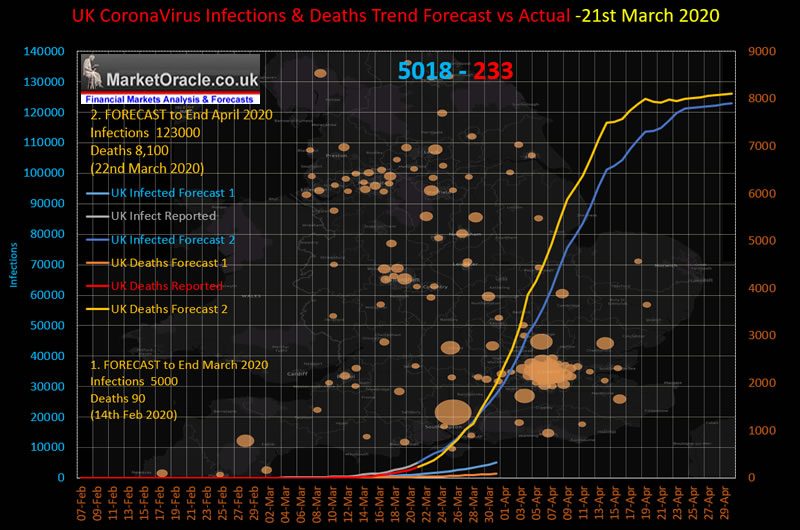
This will likely result in herd immunity amongst 3.7 million people (30X official number testing positive), so quite some distance form the 40 million that the UK was previously heading towards. Which also confirms that there will be several more pulses of infections as lock downs are replaced but are likely to be less extreme as each subsequent wave will result in greater herd immunity and thus make it harder for the virus to spread, so this first wave is likely to be by far the worst in terms of the number of deaths as more people end up in hospital sooner as there is nothing had been done to slowdown the spread of the virus and no one had any immunity in the population to slow it's spread..
Author
Nadeem Walayat
Marketoracle.co.uk
Editor of MarketOracle.co.uk, is its resident financial analyst, with over 20 years experience in trading and investing in the financial markets using both Technical and Fundamental Analysis.