Two years is a long time
Mini 2016
We got a miniature repeat of 2016 last night as the market threw everything overboard in a panic before reconsidering and taking most markets back to green. This is exactly what happened when Donald Trump won the 2016 presidential election, but this is volatility for ants compared to the chaos that evening. The rally in stocks and the dollar continued for weeks after election night 2016 because major policy changes were in store, especially with regard to fiscal. It was the dawn of the disconnect between economic growth and U.S. deficits and the birth of permanently gigantic government.
In contrast, the policy implications of these midterms are smaller. Trade and foreign policy have completely bypassed Congress now, so the policy impact of the Blue Tsunami is subtle, not massive.
Sure, popular angst about data centers will make it more difficult to permit and build. This was already happening as even Texas Republicans were already responding to voter concerns. Also, there is plenty of popular angst about many things in the U.S.: adversarial health insurance companies, polluters that externalize their costs and internalize their profits, private equity buying homes, and social media companies monetizing outrage and addiction. And yet somehow these industries all continue to do fine.
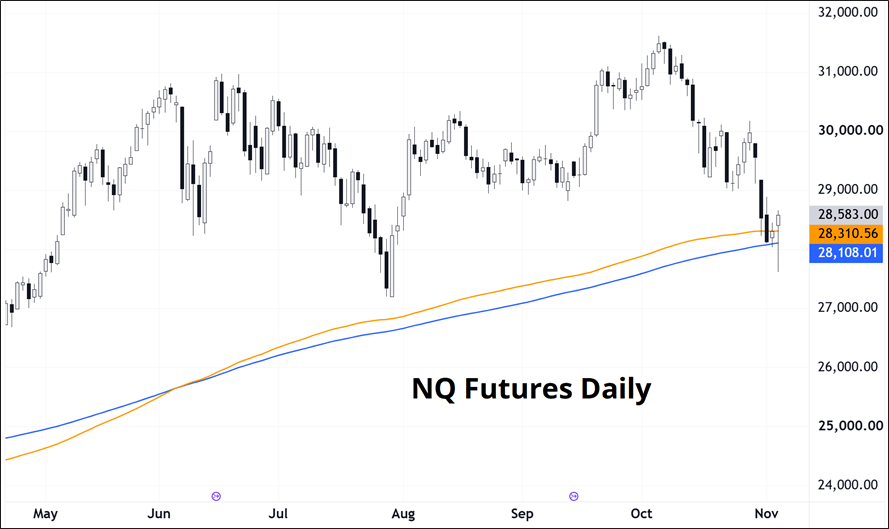
While the citizenry wishes for more corporate guardrails, those guardrails are rarely forthcoming. Net, this election is a marginal hassle for the data center buildout, but a Dem Sweep was already 75% priced in by game time—part of the move in NQ from 32000 to 28000 was a repricing of election odds and fear of the Blue Wave. Now we got the news. Not a game changer.
Trade and foreign policy are unchanged. There was no promise of any fiscal stimulus in the U.S. as the $5,000 checks were not taken seriously, even by Republicans. No tax policy changes were or are coming. And the implications of these midterms for the 2028 presidential election are too early to call.
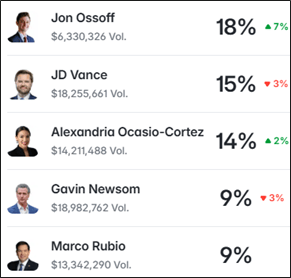
Updated gambling odds show Jon Ossoff leading overall and Ocasio-Cortez has flipped Newsom. Sometimes the market is pretty good at predicting these things, but sometimes the frontrunner is nowhere by election time. In November 2010, for example, Sarah Palin was the favorite to win the 2012 election.
Two years is a long time.The challenge now is to decide whether the election is a clearing event and final washout for the tech trade, or another reason for the buyer’s strike to continue as we now need to wrestle with the implications of:
- An electorate that is much less bullish on AI than the stock market; and
- Risk of U.S. escalation as the U.S. administration has nothing left to lose politically; or
- Iranian de-escalation because they got what they wanted from U.S. elections and now have no reason to keep pressing their luck.
It’s very hard for me to look at this chart and say I am bearish:
What about FX? The immediate reaction was to sell USD, and that is predicated on the idea that AI Capex will slow and that’s not good for U.S. growth. Again, sure. At the margin, you can make that argument. But I don’t think this is a durable theme.
My somewhat uninspiring takeaway here is that this is a vol-negative clearing event because we have eliminated another known unknown. Now, the Iran story and the U.S. economic growth story—and perhaps the still-looming energy supply issues in Europe—will vie for airtime. For now, we are through all the major central banks, most of the big elections (except ZAR and NZD) and the Fed is moving in super slow-mo and is mostly irrelevant to both the economy and financial markets. Positioning is light in most assets (USD close to flat, equity longs toasted but no massive shorts, bond shorts mostly cleaned out).
I think we are in for a low-vol world for a bit, and I am awaiting the next big theme. While we wait, it’s almost (but not quite) time to think about the Anthropic funding trade. I would think the stocks most-owned by techno-optimists (SPCX, PLTR, TSLA, NBIS) will underperform as IPO day nears. Nobody will really do these trades until the roadshow starts (November 10 maybe?). We are looking at something around 16/18NOV for the IPO and first trading day. To get ahead of the rush, ideal timing should be to short those four stocks vs. equal-weight S&P (or something similar) next Monday.
Final thoughts
- This is pretty cool: Claude: show me the blueprints. Show me the blueprints.
- As discussed yesterday, EURUSD has been moving through molasses in recent weeks due to billions of euros of gamma between 1.1150 and 1.1300. That molasses becomes a lower-viscosity syrup after 10 a.m. tomorrow as 1. the 05NOV expiries are the final big ones. If you have a strong view in EURUSD, you might get some love in the next week or so. I acknowledge that this contradicts my bigger picture view that we are in for lower financial market volatility for a week or two as the market gropes in the dark for new macro themes.
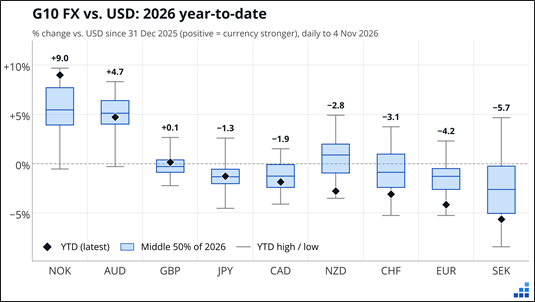
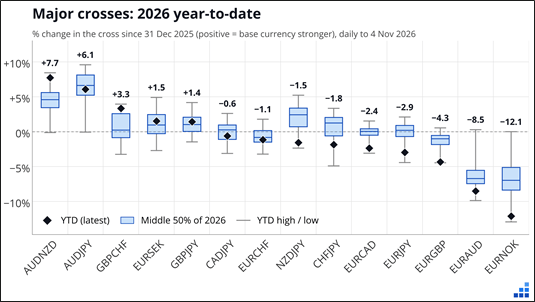
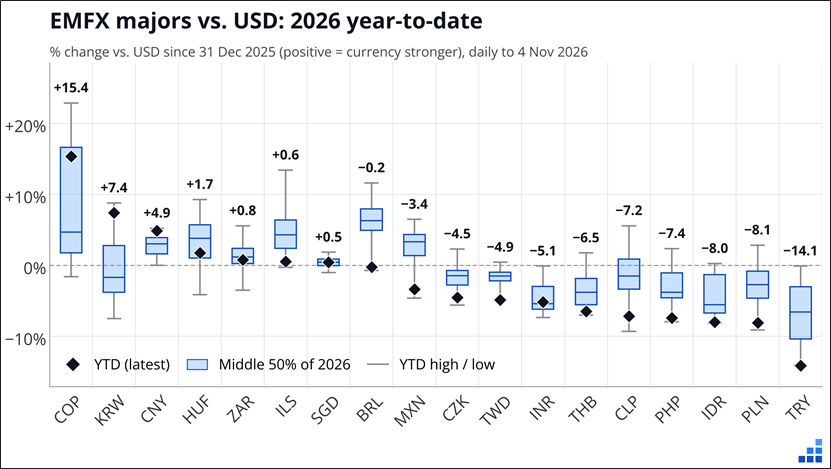
- My CADJPY short is stopped out. It was never in the money by a single pip. The JPY has been in a state of limbo throughout 2026 with the big sell JPY because of fiscal trade going nowhere but the big JPY-repatriation because of GPIF and juicy JGB yields also: going nowhere. Here is your 2026 FX YTD in three charts. NOK! Somewhat surprisingly, BRL unch.
Author

Brent Donnelly
Spectra Markets
Brent Donnelly is the President of Spectra Markets. He has been trading currencies since 1995 and writing about macro since 2004. Brent is the author of “Alpha Trader” (2021) and “The Art of Currency Trading” (Wiley, 2019).

















