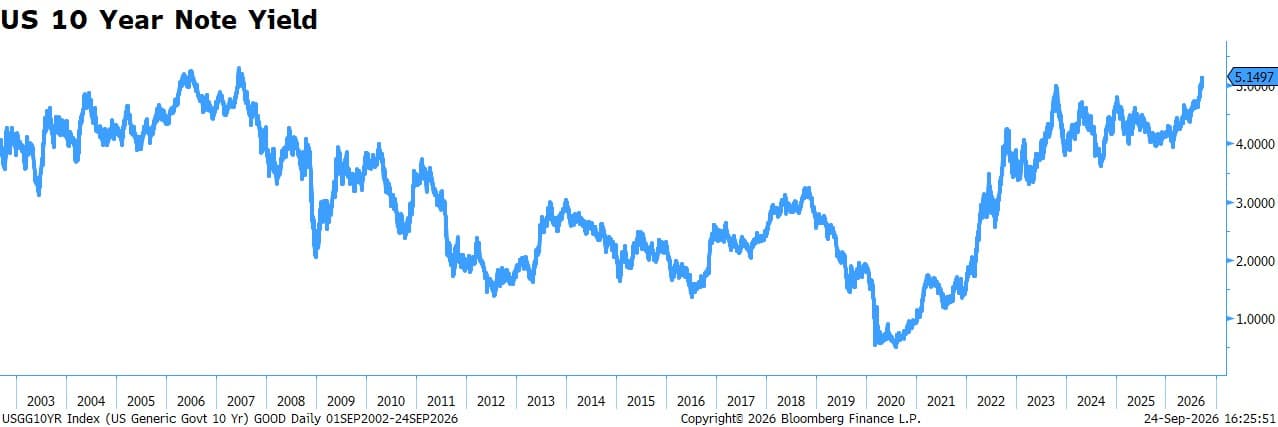
Treasury yields at 2007 highs
The combination of energy prices rising back above $100 a barrel, US PMI’s topping multi-year indexes and FOMC members taking tough tones when discussing future rate paths have all led Treasuries at both ends of the curve with higher yields. Treasury Notes (debt with a maturity between 2-10 years) account for close to 52% of all marketable Treasuries, so movements in yields are especially painful for the US fiscal outlook.
Of course, beyond recent circumstances pushing up yields, the estimated $3.7-4.7 trillion cost of the One Big Beautiful Bill over 10 years remains in the background, with seemingly no interest from the administration to rein in the bulging US deficit. This is the real backdrop that has carried US debt to its most expensive since 2007.
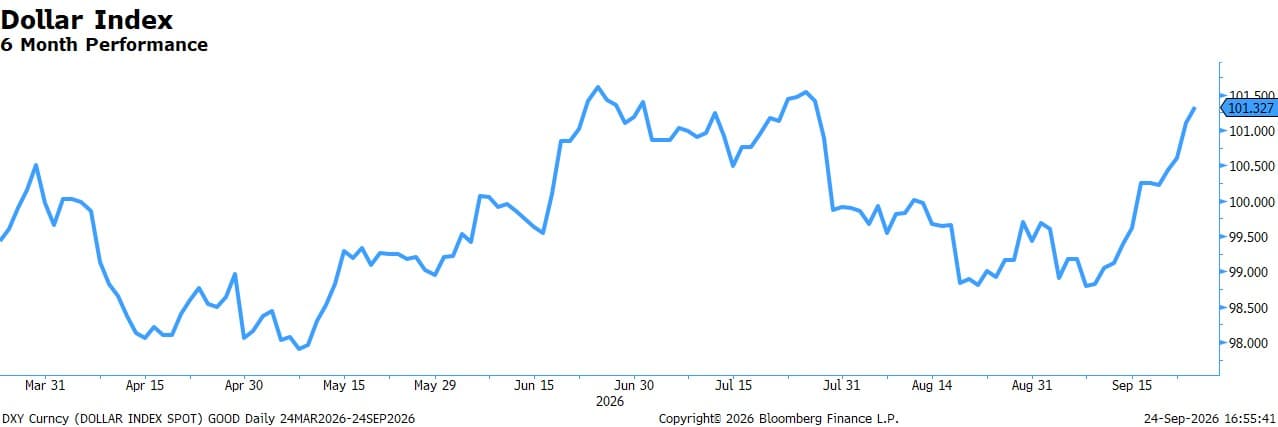
All of this, so far, has been positive for USD, which has been revived from its August slump to be pushing GBP & EUR to multi-month lows. Investors clearly don’t have the reflex they do with Gilts, where higher yields are bullish GBP to an extent before entering a “panic zone” where genuine fiscal alarm sees the Pound weaken.
However, there are some guardrails that could act to limit any further increase in yields, the first being that above a 5% yield, the domestic cost of US credit seriously starts to bite into growth. This, in the medium term, would act to soften the Fed’s stance and so the Dollar. The second factor is that much of the heavy lifting in US yields is being done by higher energy costs, which owe to the conflict in the Gulf.
Current aggregators have a Democrat sweep of both houses of congress at circa. 53% probability, although even just taking the Senate may prove enough for Democrats to block further funding needed to maintain the conflict. And so an end to the conflict sometime after the midterms seems distinctly possible, the President said as much at the UN earlier in the week.
Bessent’s buybacks are unlikely to have a serious effect with their current volumes, but a more aggressive campaign could have a more meaningful impact too. LDI demand at higher yields also acts to cap Treasuries. But the exact level where yields have reached the top is almost impossible to define, although it likely rests between the 4.5-5.5% range. For now, it’s all good news for the Greenback.
Author

David Stritch
Caxton
Working as an FX Analyst at London-based payments provider Caxton since 2022, David has deftly guided clients through the immediate post-Liz Truss volatility, the 2020 and 2024 US elections and innumerable other crises and events.















