Oil and Gold: Price review for the week ahead
This preview of weekly data examines USOIL and XAUUSD, with economic data expected later this week as the primary market drivers of the near-term outlook.
Highlights of the week: German manufacturing PMI, British manufacturing & services PMI, Trump- Xi summit.
Wednesday
- Flash German Manufacturing PMI for September is expected to decrease by 0.3 points, reaching 54. If the expectations are confirmed, it would reinforce the German manufacturing sector, which would still be growing for the majority of 2026, and, in extension, some minor support for the Euro and some manufacturing-related instruments.
- Flash British manufacturing PMI at 08:30 AM GMT. The expectations for the figure are at 51.4 compared to the previous 51.7. UK manufacturing has managed to remain above the 50 point mark since November, and if the expectations are confirmed, then it might create some short term gains for the pound.
- Flash British services PMI at 08:30 AM GMT. Market participants are expecting the publication to be at 52 points compared to the 52.5 points of August. The services sector in the UK has managed to remain above the 50-point mark for the majority of the last 3 years, showing resilience. This shows the health and strength of the service sector in the UK and could potentially create some support for the quid in the immediate aftermath of the release.
Thursday
- Chinese President Xi Jinping will visit the US from September 23–25 at the invitation of President Donald Trump. According to China’s Foreign Ministry, Xi and Trump are expected to discuss major China-US relations issues as well as broader issues concerning world peace and development. China described the reciprocal visits by the two leaders within six months as having “historic, milestone significance.”
US OIL, daily
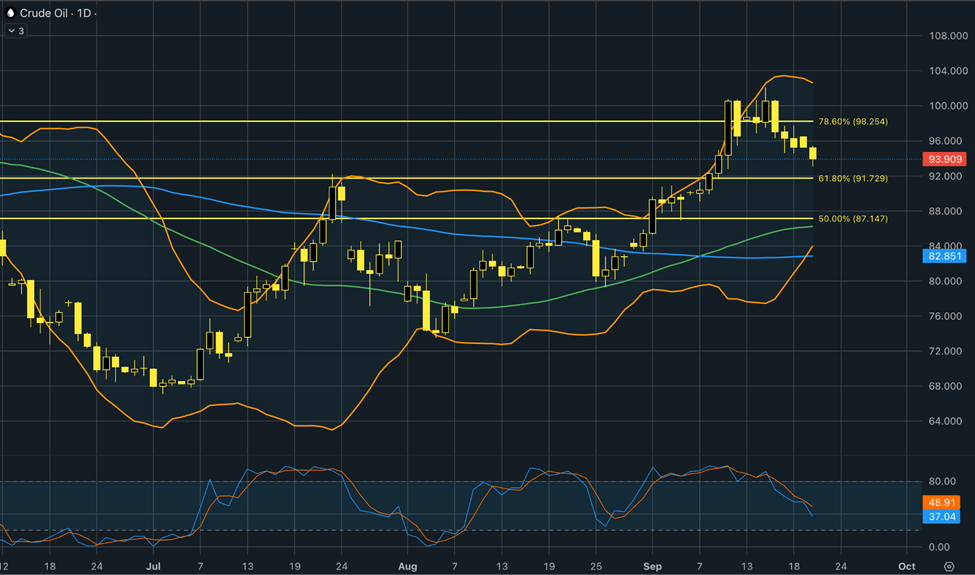
Oil fell for a fourth consecutive day as traders focused on diplomatic efforts to end the US-Iran war and evidence that crude flows through the Strait of Hormuz are recovering. Shipments through the waterway have reached a six-month high, suggesting the worst of the supply crunch may have passed. However, risks remain, with Saudi Arabia facing security threats and uncertainty over the restoration of its East-West pipeline, which was damaged earlier this month. Diplomatic developments involving the US, Iran and China could therefore remain a key driver of oil prices in the near term.
From a technical perspective, crude oil remains in a bullish medium-term structure, but the latest price action shows a clear loss of momentum. Price has pulled back to around $94 after failing to hold above the $98 Fibonacci level, while the Stochastic oscillator has fallen toward 37, confirming weakening upside momentum. The broader trend remains supported by price trading above both moving averages and the 61.8% Fibonacci level at $92. Holding above $92 would keep the broader bullish structure intact, while a break below it could expose $87. On the upside, reclaiming $98 would put the recent highs around $100–104 back into focus.
Gold-Dollar, daily
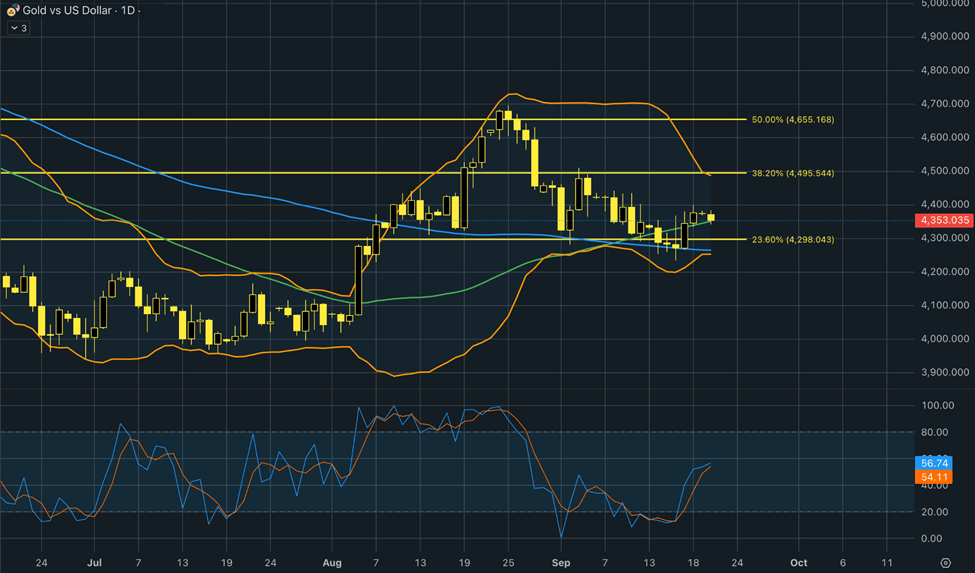
Gold declined around $4,350 as concerns over persistent inflation continued to weigh on the metal following the Fed’s first rate hike since 2023. Several Fed officials are expected to speak this week, with policymakers emphasizing that inflation remains above the 2% target and has become broader across the economy. Meanwhile, oil prices remained above $100 despite signs that flows through the Strait of Hormuz are recovering. With fewer major catalysts in the near term, gold may remain sensitive to oil prices, inflation expectations and signals from Fed officials.
From a technical point of view, gold is showing signs of recovery on the daily chart, with price around 4,350 after finding support near the 23.6% Fibonacci level at 4,300. Price has moved back above the short-term moving averages, while the Stochastic oscillator has turned higher from oversold territory, indicating improving bullish momentum. However, the broader recovery remains capped by the 38.2% Fibonacci resistance at 4,500. A sustained break above this level could open the way toward 4,655, while a move back below 4,300 would weaken the recovery and bring the 4,200 area back into focus.
Author

Antreas Themistokleous
Exness
Antreas has been trading CFDs since 2018 using a combination of fundamental and technical analysis.















