Fed policy: January hike added after hot CPI – Deutsche Bank
- Deutsche Bank now expects 25 basis point (bps) Fed hikes in December, January and March, taking rates to 4.50%-4.75%.
- The October Consumer Price Index (CPI) rose 0.4% against 0.3% expected, while core CPI rose 0.3% against 0.2% expected.
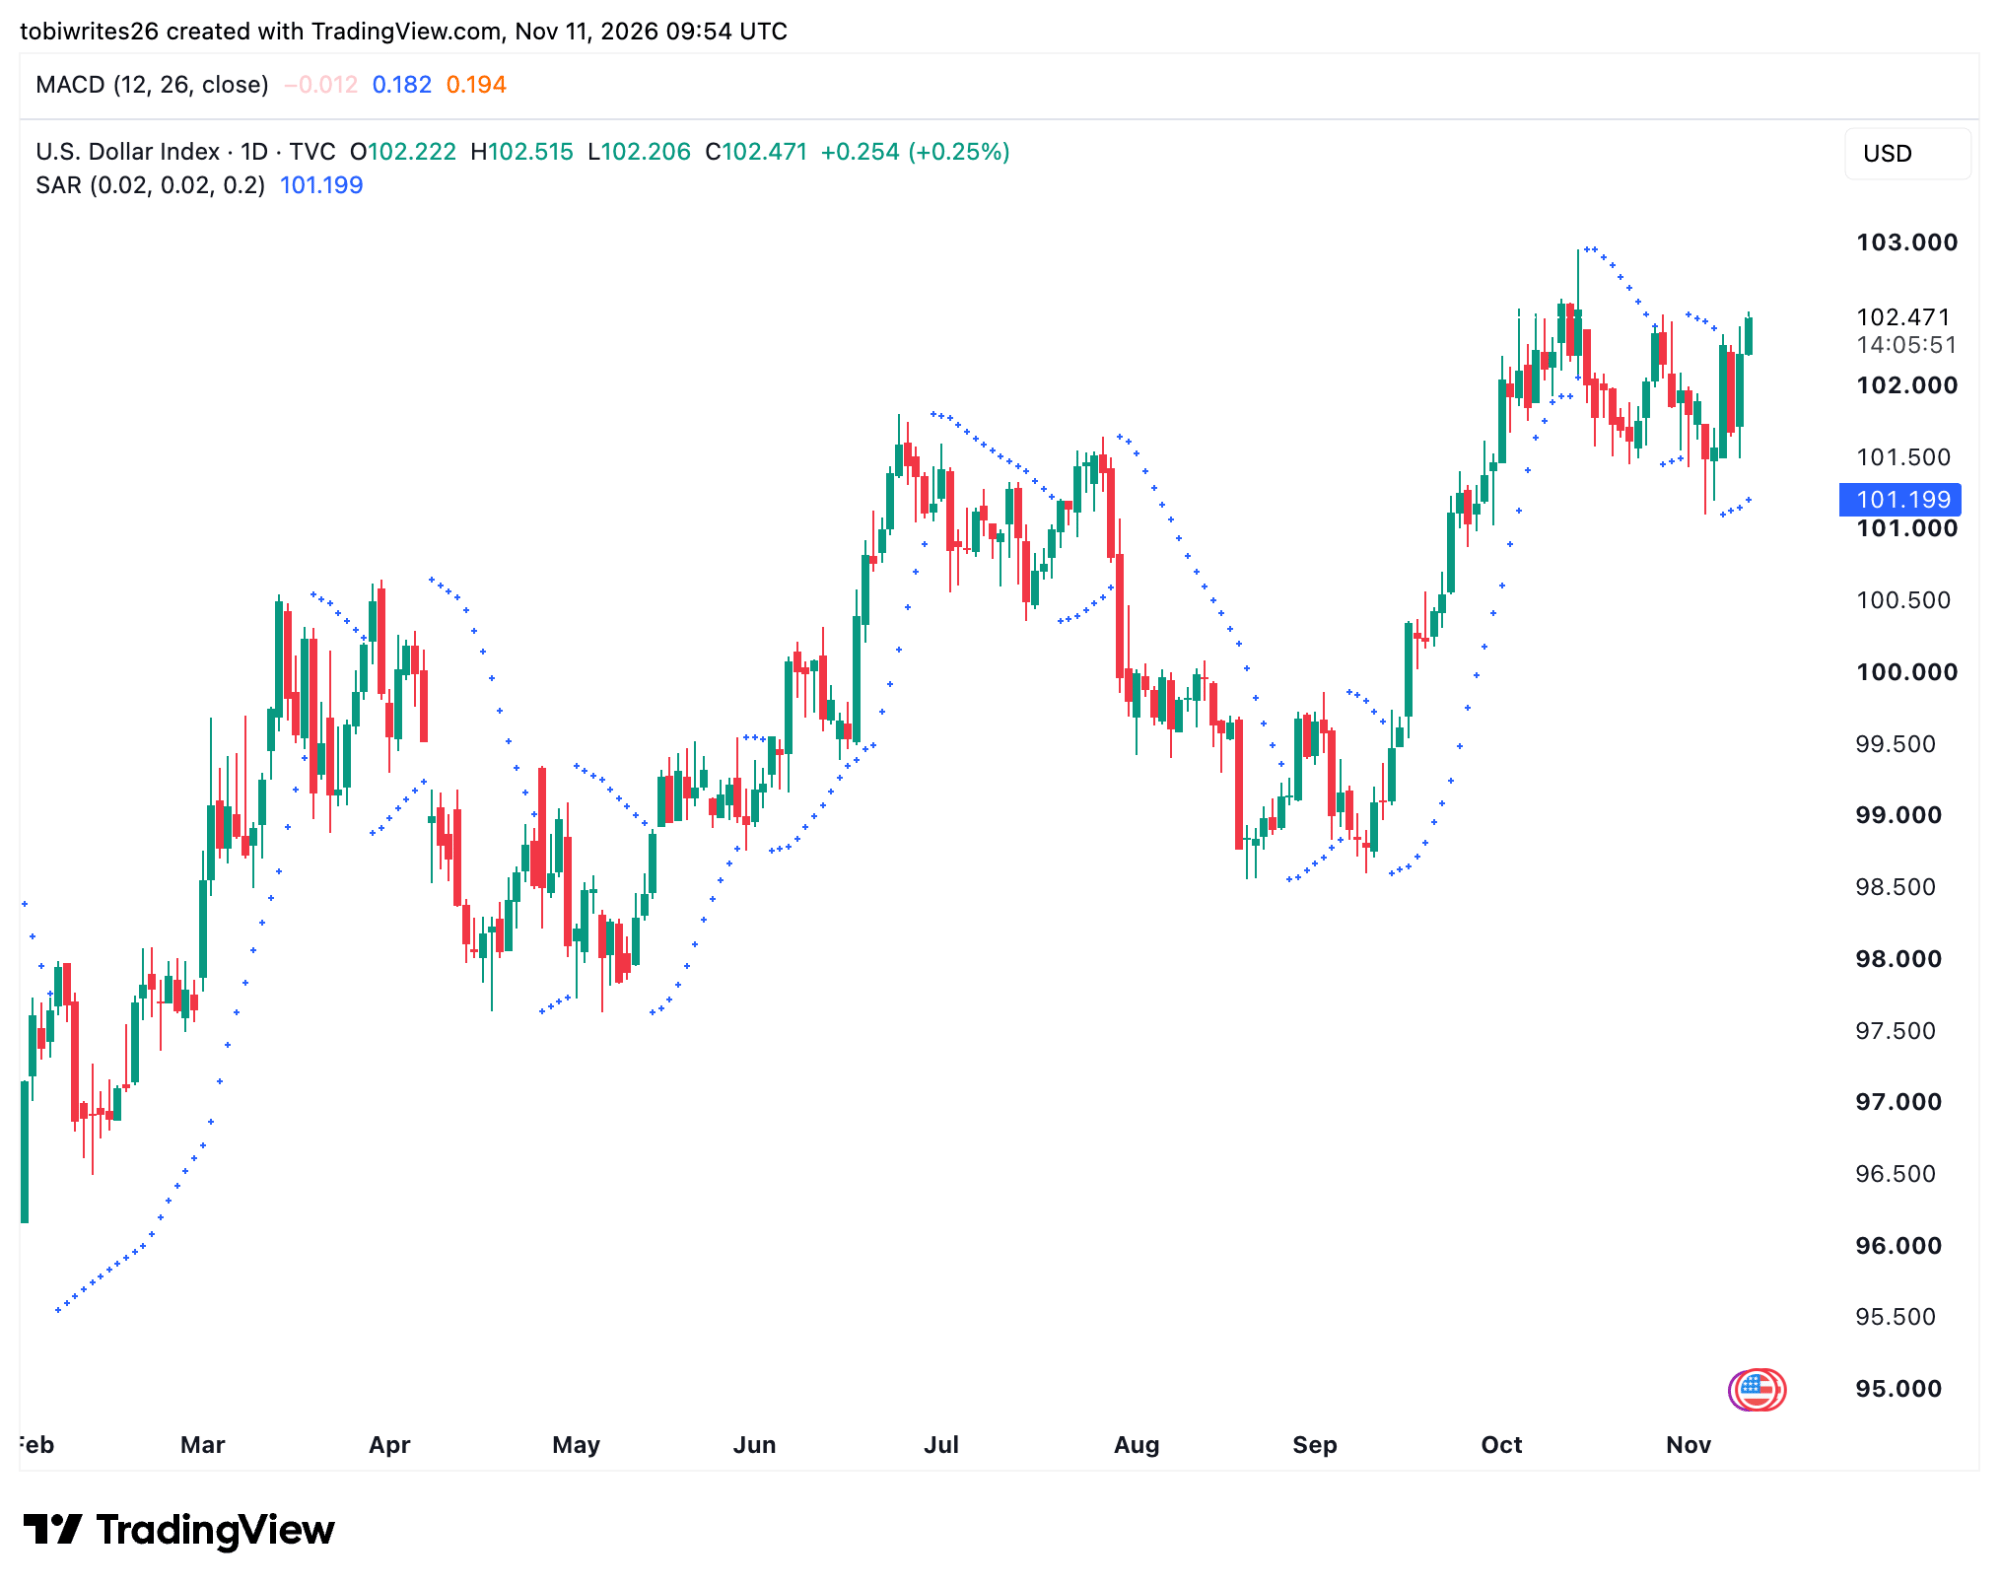
- The US Dollar Index (DXY) holds near 102.50 as markets fully price a December hike.
Economists at Deutsche Bank now expect the Federal Reserve (Fed) to raise interest rates by 25 bps at each of its next three meetings, in December, January and March, after another hot inflation print. The extra January hike would lift the federal funds rate to 4.50%-4.75% from the current 3.75%-4.00%, bringing total tightening in this cycle to 100 bps.
Why Deutsche Bank added a January hike
In a Fed Notes report dated November 10, titled "Warsh-ing their hands of accommodation," the team led by Chief US Economist Matthew Luzzetti said October's price gains were broad-based. Owners' equivalent rent rose across regions, artificial intelligence (AI) demand pushed television and smartphone prices up by a record monthly amount, and core goods excluding used cars posted their strongest gain since January 2023.
The bank also points to a tightening labor market. Payrolls averaged 83K over the past six months, above the breakeven pace, and the unemployment rate fell to 4.1%. Deutsche Bank raised its estimate of the neutral rate to 3.75%-4.00% and sees the fed funds rate settling there by the end of 2028.
A 50 bps hike in December is not the bank's base case. It notes that officials, including Dallas Fed President Lorie Logan and Cleveland Fed President Beth Hammack, have favored a gradual pace, that oil prices have eased and that market-based inflation expectations remain anchored. A deeper sell-off tied to AI valuations, which has already widened credit spreads, could make the Fed hesitate to speed up, the economists add.
CPI and Fed pricing
CPI rose 0.4% in October after a 0.6% gain in September, the US Bureau of Labor Statistics reported on Tuesday, above the 0.3% consensus. Core CPI rose 0.3% for a third straight month, against expectations of 0.2%. The BLS did not publish an annual rate because October 2025 data was missing.
Before the release, Fed Governor Christopher Waller said a 50 bps hike should be considered in December if core CPI came in around 0.3% or higher. "Hiking only 25 basis points would put our credibility at risk," Waller said at the Bank of England Watchers Conference in London on Tuesday.
Late on Tuesday, markets priced an 88.8% chance of a 25 bps hike in December and an 11.2% chance of a 50 bps move, with no chance of a hold, according to the CME FedWatch Tool, as reported by Investing.com. The Fed announces its decision on December 9 at 19:00 GMT.
US Dollar Index technical outlook
The US Dollar Index trades near 102.48 in the European session on Wednesday, up 0.25% on the day, according to TradingView data. On the daily chart, DXY holds above its 20-day Simple Moving Average (SMA) at 101.92, 50-day SMA at 101.23, and 200-day SMA at 99.85. The Relative Strength Index (RSI) is near 59, and an Average Directional Index (ADX) of 22 suggests buyers retain control without stretched momentum.
Initial resistance sits at the daily R1 pivot at 102.79, ahead of the R2 pivot at 103.62. On the downside, the daily pivot at 102.12 offers first support ahead of the 20-day SMA at 101.92. A daily close below the 50-day SMA at 101.23 would weaken the bullish structure.
Author

Tobi Opeyemi Amure
Independent Analyst
Tobi Opeyemi Amure, CFEI®, is a markets journalist who has spent seven years following the money across stocks, payments, AI, and crypto. His reporting has appeared in Investopedia, TheStreet, Benzinga, Inc., FinanceFeeds, and DailyForex.

















