Fed holds, but the Dollar may have heard something else
The Federal Reserve kept interest rates unchanged at 3.50%–3.75% on Wednesday, but the real market signal was not the hold itself. It was what Chair Kevin Warsh didn’t say about September.
Three FOMC members dissented in favour of an immediate 25bp hike, while the statement maintained a relatively hawkish tone around inflation. Economic activity was described as expanding at a “solid pace”, the labour market remains broadly stable, and inflation is still running above the Fed’s 2% objective.
On the surface, that sounds like a central bank preparing to tighten.
But Warsh stopped short of guiding markets towards a September hike. Instead, the message remained data-dependent, leaving the Fed with optionality rather than committing to another move.
That distinction matters.
Before the meeting, investors were increasingly treating September as the natural destination for a hike if the Fed stayed on hold in July. Following Warsh’s comments, those expectations were scaled back materially, leaving September much closer to a genuine coin toss.
Hawkish Fed, Dovish market reaction
This creates an interesting contradiction.
The Fed’s language remains hawkish: inflation is too high, economic growth remains solid enough to tolerate tighter policy, and three policymakers already believe rates should be higher.
Yet the market heard something slightly more dovish: the Fed is not in a rush.
That was reflected in the initial reaction. Interest-rate-sensitive two-year Treasury yields fell and the dollar weakened after the decision, suggesting traders reduced expectations for near-term tightening.
My bias here is that the dollar could remain vulnerable unless upcoming inflation data forces the market to rebuild expectations for a September hike.
The Fed has effectively handed the decision back to the data.
If inflation remains sticky, September pricing can quickly turn hawkish again. But if the next few inflation and labour-market releases soften, the market may increasingly conclude that July was not simply a delayed hike — it was the beginning of a longer pause.
DXY: 100.300 comes back into focus
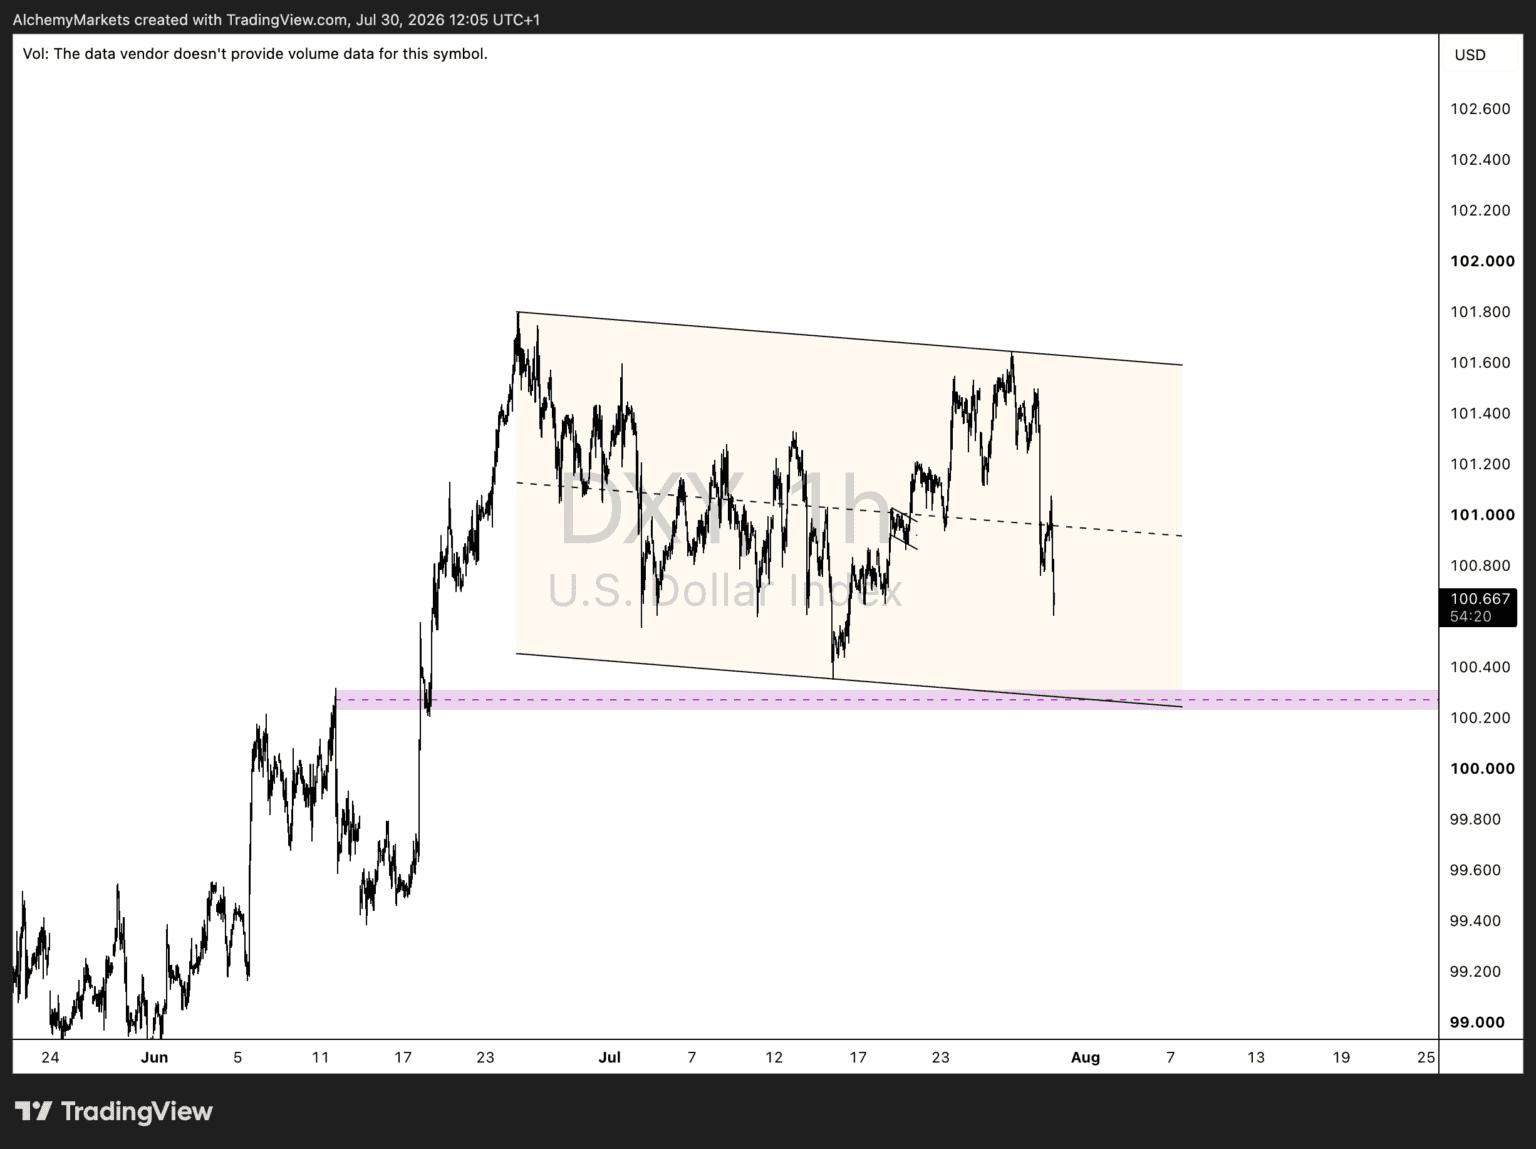
Technically, the Dollar Index now has the potential to extend its move lower following the post-Fed rejection.
The key downside area to watch is 100.300, which provides the next meaningful support zone.
As long as DXY fails to regain its recent highs and expectations for September tightening remain contained, the path of least resistance could remain lower towards this level.
A clean break below 100.300 would strengthen the bearish dollar narrative, while a recovery driven by stronger inflation data and renewed Fed hike expectations would challenge it.
For now, the interesting takeaway from the Fed is simple: the rhetoric was hawkish, but the market was expecting something even more hawkish.
And in markets, the difference between what happens and what was already expected is often what matters most.
Author

Zorrays Junaid
Alchemy Markets
Zorrays Junaid has extensive combined experience in the financial markets as a portfolio manager and trading coach. More recently, he is an Analyst with Alchemy Markets, and has contributed to DailyFX and Elliott Wave Forecast in the past.

















