Dollar Index (DXY) pushes higher on strong S&P PMI data

Soft EU PMI drags Euro lower, USD/JPY surges toward 160.00
Summary:
Solid US S&P Manufacturing and Services PMIs lifted the Dollar Index (DXY) to105.80, from 105.65, its strongest finish since late April.
A surge in Services to 55.1, which beat estimates at 53.4, strengthened the case for fewer Fed rate cuts. The solid state of the US economy kept bond yields steady, at their recent highs.
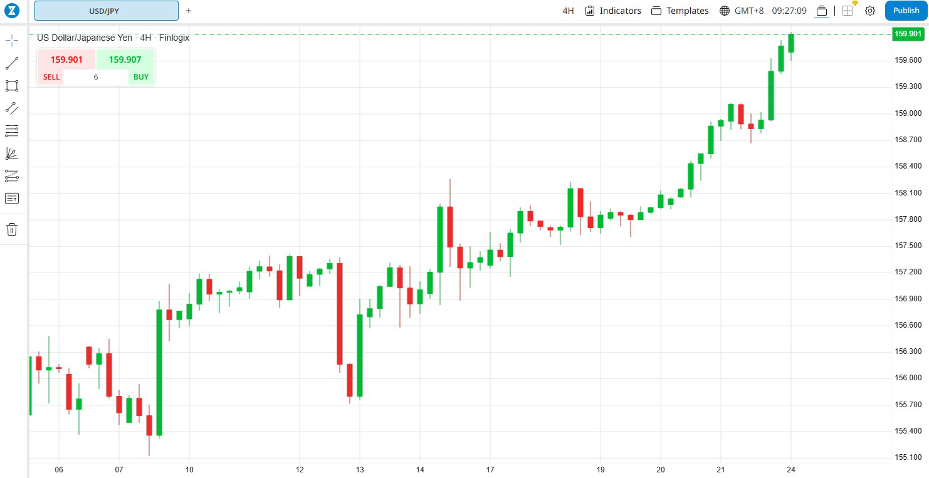
The USD/JPY pair surged to 159.75 from Friday’s opening at 158.90, closing in on intervention levels last reached on April 29. Then, Japan’s Ministry of Finance and BOJ intervened in the markets, when USD/JPY surged past 160 to a 160.32 year-to-date peak.
The Euro (EUR/USD) pushed lower to 1.0685 at the New York close, from 1.0705 Friday. The shared currency traded at an overnight low at 1.0671 before steadying.
Sterling slid to 1.2645 (1.2660) against the Greenback. The British Pound traded to an overnight low at 1.2622. With the Bank of England likely to cut rates in August, GBP/USD remained soft.
The Australian Dollar (AUD/USD) eased to 0.6640 from 0.6675 against the broadly based stronger Greenback. In contrast to the solid US PMIs, Australia’s Preliminary PMI data was soft.
Against the Asian and Emerging Market Currencies, the Greenback (USD/EMFX) was mixed. The USD/CNH pair (Dollar-Offshore Chinese Yuan) settled at 7.2900 (7.2910) while the USD/SGD (Dollar-Singapore Dollar) pair was last at 1.3545 from 1.3560.
Global bond yields were mixed. The US 10-year bond yield was flat at 4.26%. Germany’s 10-year Bund rate dipped to 2.40% from 2.43%. The UK 10-year Gilt yield closed at 4.08% (4.05%).
Wall Street stocks finished with modest gains. The DOW settled at 39,227 (39,120) while the S&P 500 was last at 5,480 (5,473). Germany’s DAX Index dipped to 18,190 from 18,240.
- USD/JPY – The Greenback surged against the Japanese Yen to an overnight and 7-week high at 159.83 before easing to 159.75. On Friday the USD/JPY pair opened at 158.90. Dollar bulls have 160 in their sight, awaiting rhetoric from Japanese officials.
- EUR/USD – The shared currency eased against the broadly based stronger US Dollar to 1.0685 from its 1.0705 opening. The Euro traded to an overnight low at 1.0671 while the overnight high recorded was 1.0721.
- AUD/USD – The Aussie Battler dipped to 0.6640 from 0.6675 Friday. Contrasting PMI data between Australia (weaker) and the US (stronger) weighed on the Australian Dollar. The overnight low traded for the Aussie Battler was 0.6632.
- GBP/USD – Following the Bank of England’s decision last week to maintain interest rates, the British currency fell under the weight of an overall stronger US Dollar. Overnight, the GBP/USD pair traded to a low at 1.26220 before rallying to 1.2645.
On the lookout:
Today’s economic calendar is light and kicked off with New Zealand’s May Trade Balance, which climbed to +NZD 0.204 billion, from +NZD 0.003 billion. Exports rose while Imports fell.
Japan follows with its BOJ Summary of Opinions (which is the Bank of Japan’s projection for inflation and economic growth). Germany starts off Europe with its German Ifo Business Climate (f/c 89.7 from 89.3 – ACY Finlogix).
The UK follows with its UK June CBI Industrial Trends Orders (f/c -26 from -33 previously – ACY Finlogix). The US rounds up today’s light economic data releases with its US June Dallas Fed Manufacturing Index (f/c -13 from -19.4 ACY Finlogix).
Trading perspective:
The Dollar Index (DXY) finished on a strong note, climbing to 105.80 from 105.65, its strongest close since late April. Solid US economic data and the growing likelihood of fewer Fed rate cuts puts a bid under the US Dollar.
With today’s light economic calendar releases, expect the recent ranges in FX to continue. Traders will watch the Dollar Index (DXY). A break above 106.00 could see 106.20. The next resistance level is found at 106.50 (strong). The immediate support level in the Dollar Index lies at 105.50. Expect more choppy trading today within the 105.50 and 106.00.
While the Dollar firmed against most of its Rivals, US bond yields were flat. An easing in US rates is highly unlikely at this stage, which will keep the Greenback bid. With little in terms of data today, traders will keep their focus on the weakening Japanese Yen. Expect more rhetoric from Japanese officials today. An appearance from the BOJ/MOF in the USD/JPY market could send the currency pair back to the low to mid 150’s. We could be in for a choppy start to the week. Happy days.
- USD/JPY – In early Asian trade, the Dollar Yen pair edges patiently higher, now currently at 159.88 (159.80 open). Immediate resistance lies at 160.00 followed by 160.30 and 160.60. Immediate support can be found at 159.40, 159.00 and 158.60. Look for a choppy start to this currency pair, likely range today: 158.50-160.20. Tin helmets on, look for another choppy trading session in this currency pair today.
- EUR/USD – the shared currency eased to1.0685 in late New York. Immediate support in the Euro can be found at 1.0650 and 1.0620. On the topside, look for immediate resistance at 1.0720 (overnight high traded was 1.0721). The next resistance level lies at 1.0750 and 1.0780. Look for consolidation in a likely trading range today of 1.0630-1.0730. Trade the range, the preference is still to sell Euro on strength.
- AUD/USD - The Aussie Battler dipped against the overall stronger US Dollar to 0.6640 (0.6675 Friday opening). Immediate support today lies at 0.6610 followed by 0.6580. On the topside, look for immediate resistance at 0.6670 followed by 0.6800 and 0.6830. Look for the Aussie to remain heavy and trade in a likely range today of 0.6600-.06700. Trade the range with the preference to sell Aussie rallies.
- GBP/USD – Sterling dipped to finish at 1.2645 from its opening at 1.2660. On the day, look for immediate support at 1.2615 followed by 1.585. The British Pound has immediate resistance at 1.2680 (overnight high traded was 1.2674). The next resistance level lies at 1.2710. Look for the GBP/USD pair to consolidate in a likely range of 1.2610-1.2710. Look to sell Sterling on strength to 1.2700.
Happy Monday and trading all. Have a good week ahead.
Author

Michael Moran
ACY Securities
Michael has over 40 years’ FX experience, including running FX trading desks for some of the largest banks in the world.