Chinese covid deaths hits risk

Rising covid cases and deaths – the first in months - in China, with the authorities telling millions to stay home, seems to be dampening the mood for risk. Seems to be viewed as pushing back the full reopening and end to zero covid by a notch or several. Hong Kong fell 2% and shares across Asia tended to move lower. European stock markets opened broadly lower, with US futures also in the red ahead of a holiday-curtailed week. Wall Street closed higher on Friday but finished the week lower with some pretty stern language from several Fed speakers trying to rein in the bulls.
Inflation peak? German industrial producer prices declined 4.2% in October from September. Year-on-year inflation still stands at a pretty lofty 34.5%, but this may add to a collection of recent data that has pointed to a levelling out in inflation...remember a peak and a plateau are two very different things and the longer the inflation persists at an elevated level the more central banks will need to do.
Zoom earnings will be parsed for signs that the worst is over for the speculative tech bubble. In the previous quarter Zoom reported declining revenue growth which it blamed in part on the stronger dollar. For the current quarter just past Zoom guided for adjusted earnings of 82 cents per share to 83 cents per share on $1.095 billion to $1.100 billion in revenue.
Disney shares jumped 6% or so in Germany after the company recalled Bog Iger as CEO, replacing his successor Bob Chapek. Odd move in many ways – Chapek's contract was renewed this summer. But the stock is down hard this year and it’s chucking billions at competing with Netflix and maybe the old hand on the tiller is what’s required.
Elsewhere, the dollar continues to rise after last week’s 3-month low; Treasury yields pretty steady with 10s around 3.810%. GBPUSD trades in consolidation move around 1.18, having touched 1.20 last week. The euro is pulling back a bit more decisively, gold also dropping off last week’s highs at $1,786 to $1,740 this morning. Bitcoin is lower, back under $16k on Monday morning as the ongoing fallout from the FTX debacles underpins weakness in the crypto market.
Today…we hear from San Francisco Fed president Mary Daly – who last week said pausing hikes is off the table. Slightly odd week with the Thanksgiving holiday on Thursday with the US shut, and equity markets close early on Friday. Ahead of this there is a deluge of US economic data on Wednesday to look forward to, with durable goods, unemployment claims and new home sales data to look at. Traders will also pay close attention to the University of Michigan consumer sentiment and inflation expectations, whilst the heavy data day is rounded out with the minutes from the last FOMC meeting, which could show more detail on policymakers’ thinking on whether to slow the pace of rate hikes.
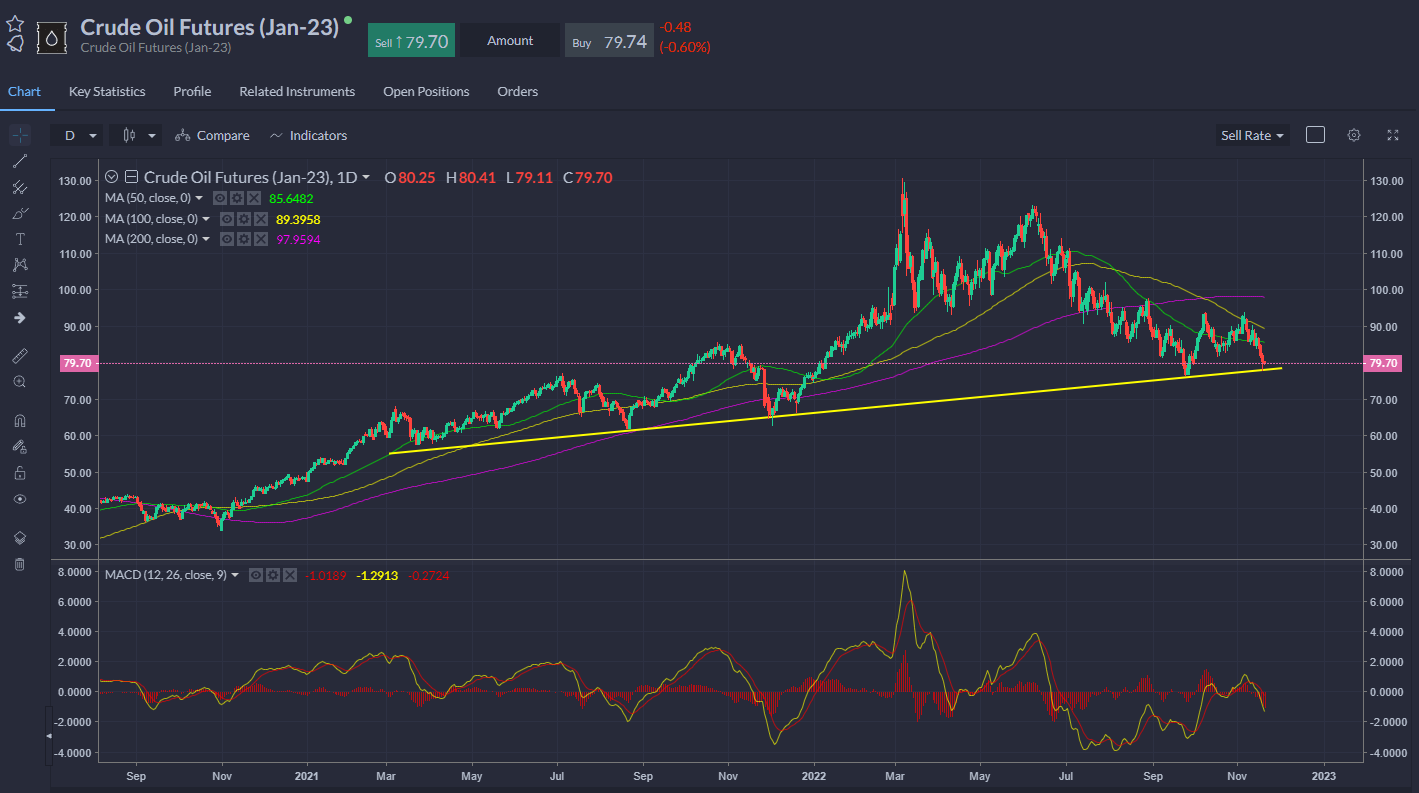
Global oil inventories drawing down but fears about Chinese demand is driving the market lower and into contango, with futures prices higher. WTI futures are up a bit from Friday’s two-month lows at $80.
Author

Neil Wilson
Markets.com
Neil is the chief market analyst for Markets.com, covering a broad range of topics across FX, equities and commodities. He joined in 2018 after two years working as senior market analyst for ETX Capital.

















