Busy week for the markets
Fundamentals to lead the FX market
We are entering a busy week, full with high-impact financial releases and central bank interest rate decisions, yet the calendar seems pretty empty today and in tomorrow’s Asian and European sessions, with fundamentals probably leading the way in the FX market. For reference purposes, the USD seems to have halted its drop for the time being and seems to be gaining.
Bearish tendencies for US equities as the week begins
We are still detecting mixed signals from US stock markets, yet in today’s premarket hours a bearish predisposition seems to prevail. Worries for the CapEx required for AI technology, as well as worries for inflationary pressures in the US economy tend to weigh on US equities. For the week, we highlight the earnings reports of Alphabet, Microsoft, Amazon and Intel, which could affects widely the market sentiment.
Oil prices correct lower
Oil prices tended to correct lower in today’s Asian session, after Friday’s rally. On a fundamental level, market hopes for an easing of the hostilities in the Gulf region tend to weigh on the commodity’s price. Yet the situation remains tense and its characteristic that the number of attacks on vessels sailing in the Straits of Hormuz reached its highest in the current month. Should we see market worries for the supply side of the international oil market intensify, we may see oil’s price rising and vice versa.
Other highlights for today
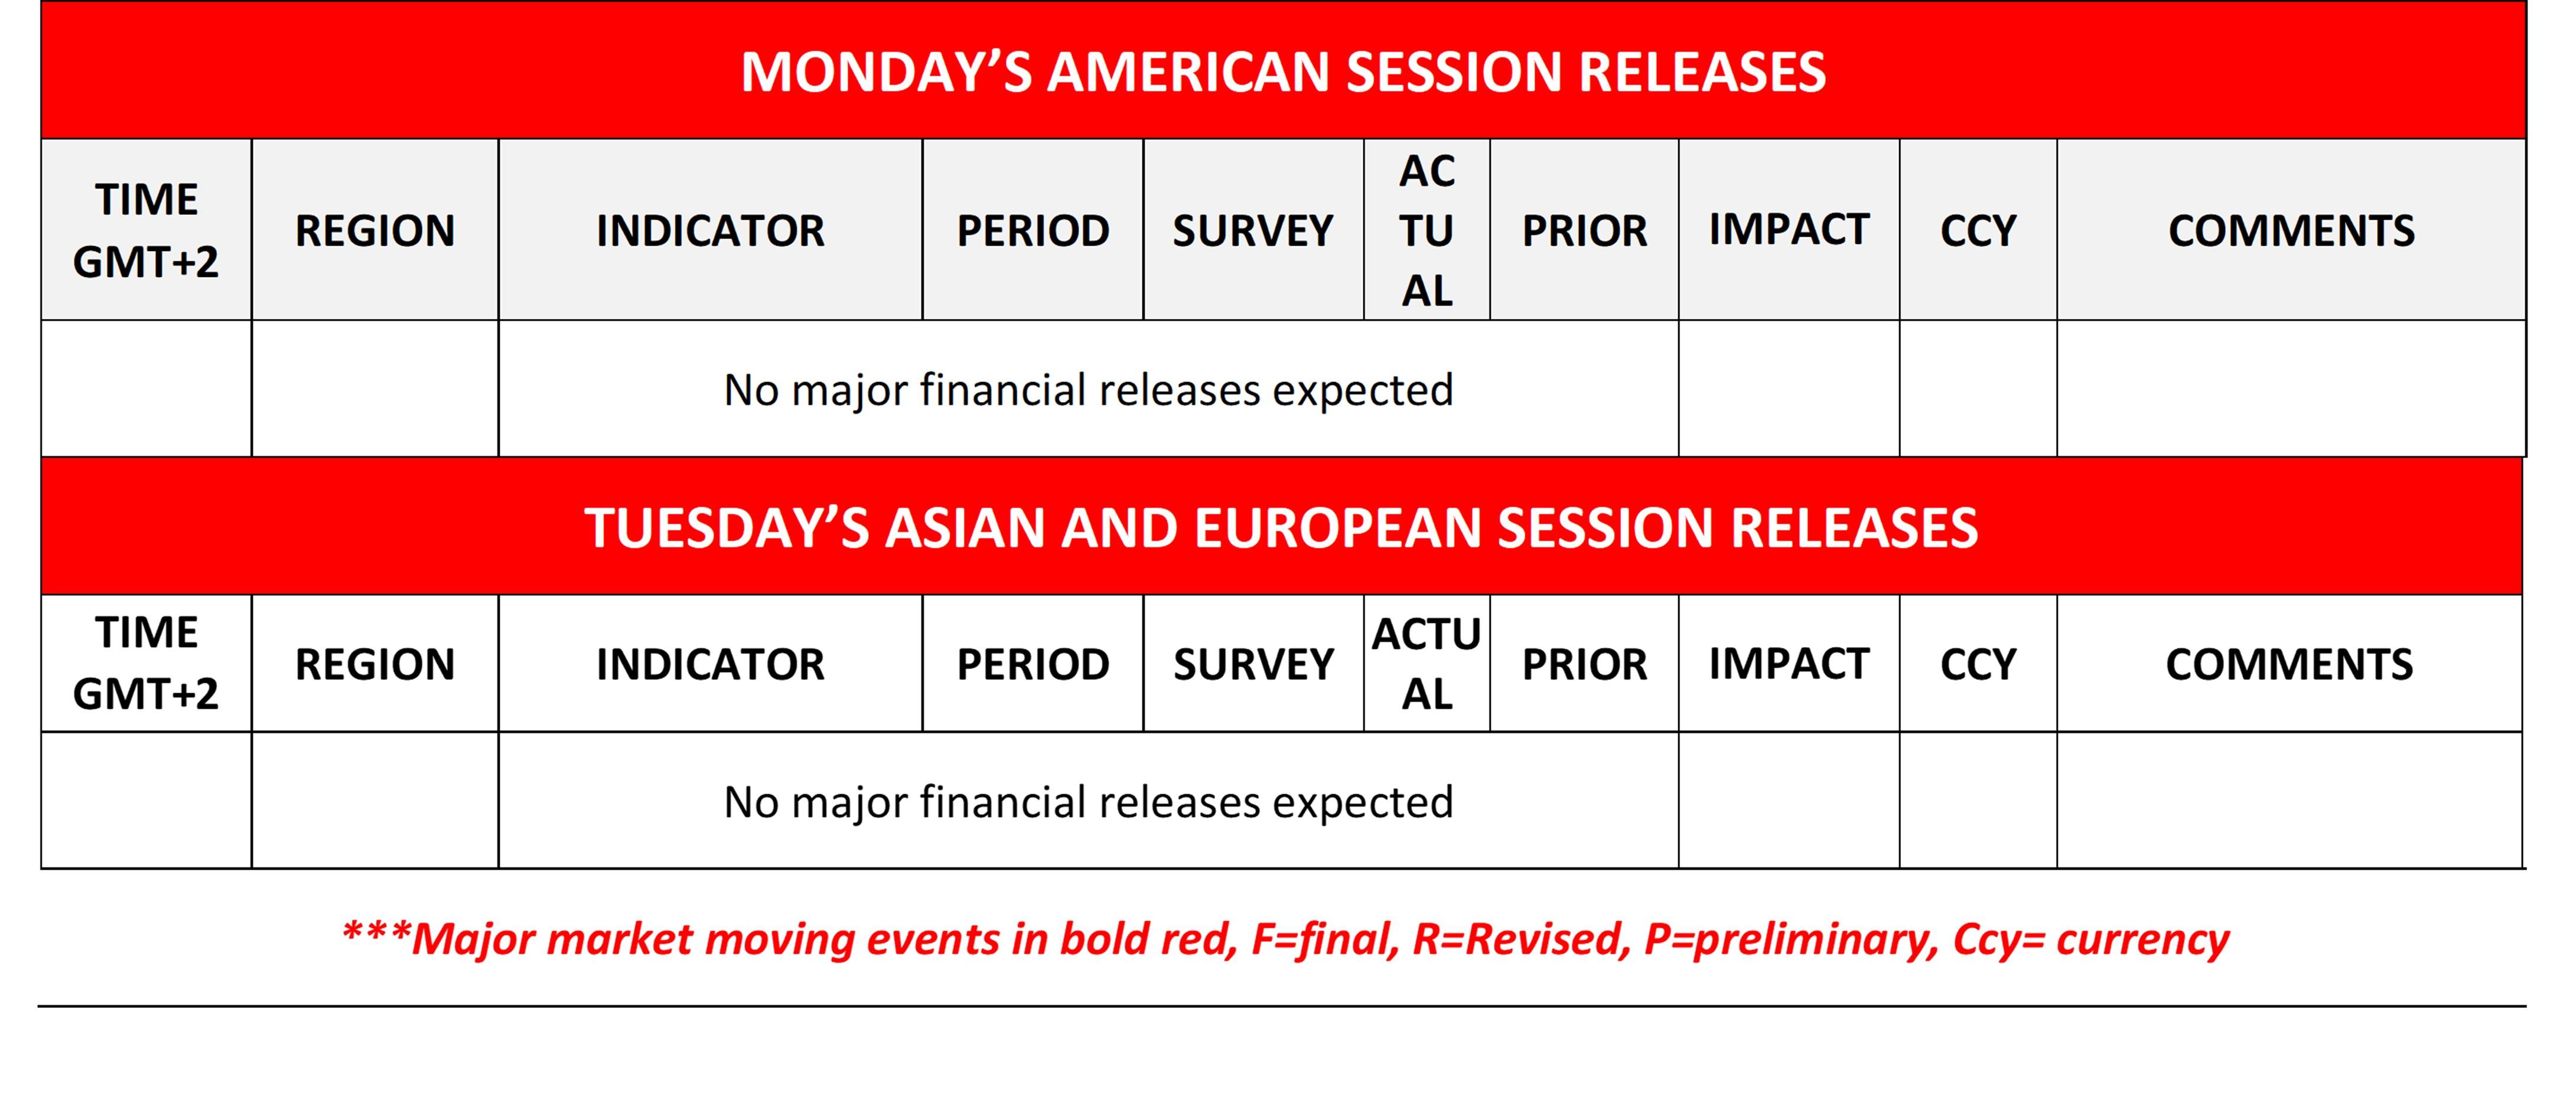
No major financial releases are expected in today’s American and tomorrow’s Asian and European session.
As for the rest of the week
In Tuesday’s American session, we get the US durable goods orders for September and consumer confidence for October. On Wednesday we get Australia’s CPI rates for Q3 and September, from New Zealand we get RBNZ’s interest rate decision, the UK Government is to deliver Autumn statement, from Canada BoC’s interest rate decision and the highlight from the US the Fed’s interest rate decision. On Thursday we get Sweden’s GDP rate for Q3, Euro Zone’s Consumer Confidence for October, the US PCE rates for September and Q3 GDP advance rates and from the Euro Zone’s ECB’s interest rate decision. On Friday we get from Japan, BoJ’s interest rate decision and October’s CPI rates and September’s industrial output, France’s Germany’s and the Euro Zone’s GDP rates for Q3, Germany’s and France’s preliminary HICP rates for October and Switzerland’s KOF indicator for October.
Charts to keep an eye out
USD/CAD bounced on the 1.3990 (S1) support line, correcting higher after last week’s tumbling. The downward trendline guiding the pair seems to have been broken, forcing us to switch our bearish outlook in favour of a sideways motion for the time being. Yet the bearish market sentiment is still present for the pair, given the low level of the RSI indicator, which may renew the bearish tendencies of the pair. Should the bears regain control over USD/CAD could break the 1.3990 (S1) support line and start aiming for the 1.3880 (S2) support level. Should the bulls take the lead, USD/JPY may aim if not break the 1.4125 (R1) resistance line.
Gold’s price dropped on Thursday and is currently testing the 3960 (S1) support line. We maintain for the time being our sideways motion bias for the precious metal’s price, yet warn of any bearish tendencies given that the RSI indicator has neared the reading of 30, signalling a strong bearish market sentiment. Should the bears be in charge, we may see XAU/USD breaching the 3960 (S1) support line and start aiming for the 3600 (S2) support base. Should the bulls take over, we may see Gold’s price breaking the 4275 (R1) resistance line, and start aiming for the 4550 (R2) resistance level.
Calendar follows
USD/CAD daily chart
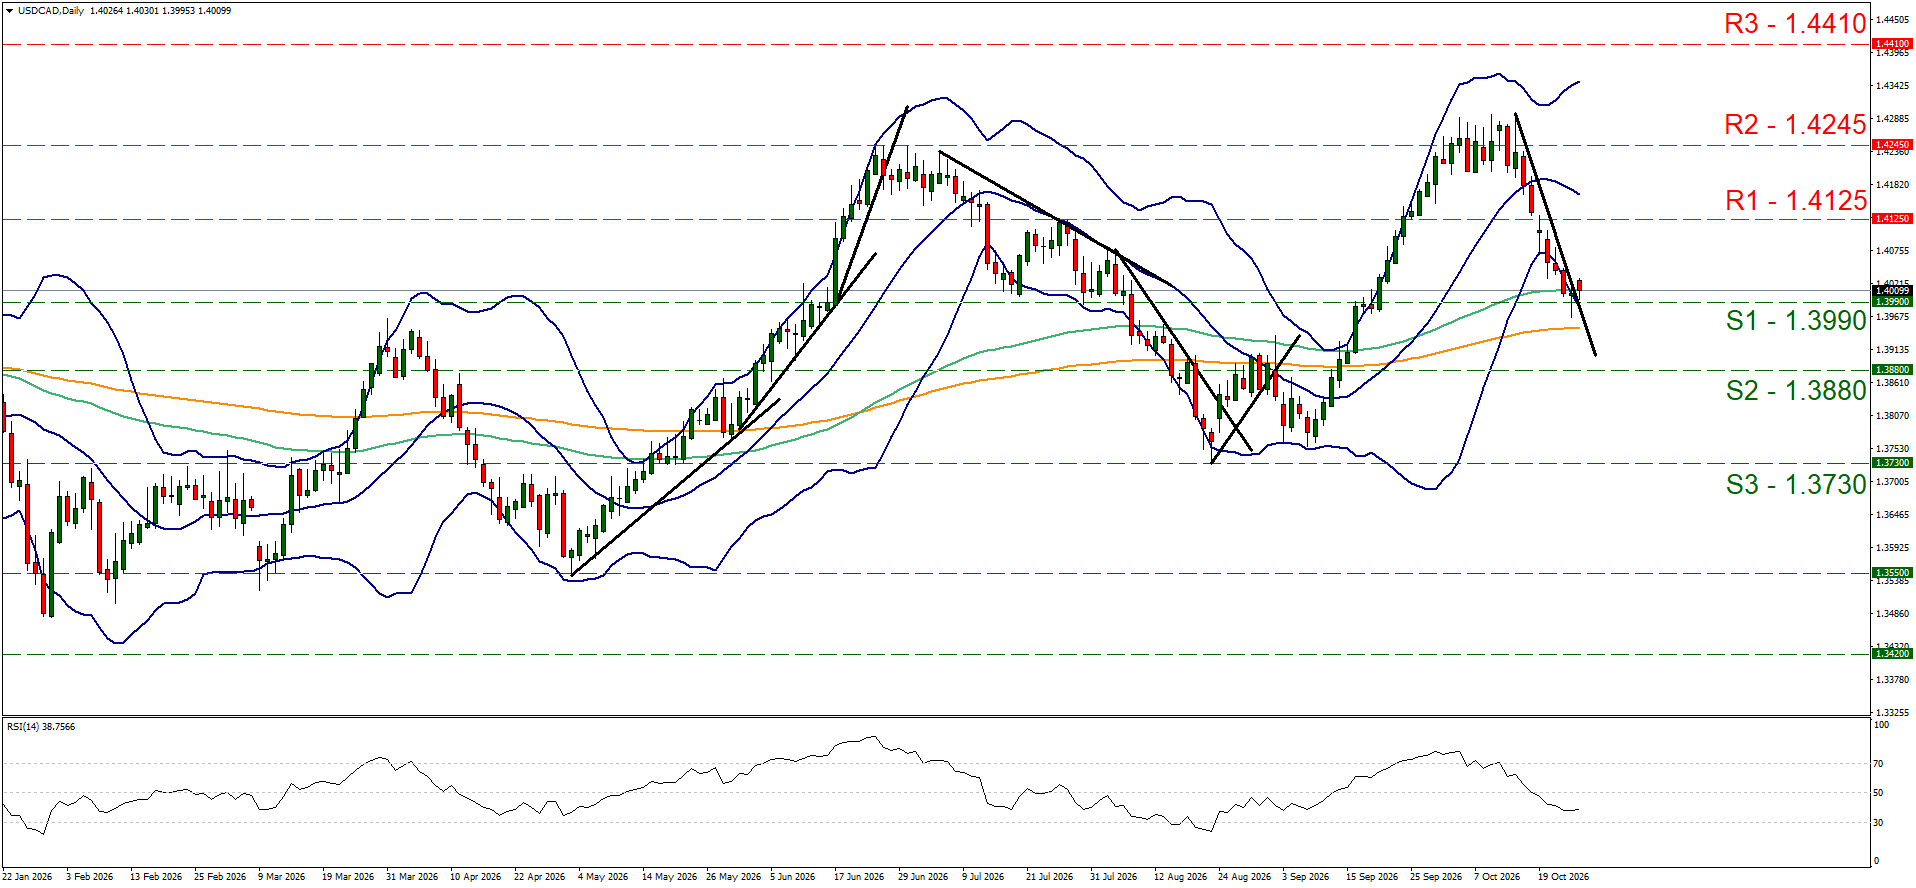
- Support: 1.3390 (S1), 1.3880 (S2), 1.3730 (S3).
- Resistance: 1.4125 (R1), 1.4245 (R2), 1.4410 (R3).
XAU/USD daily chart
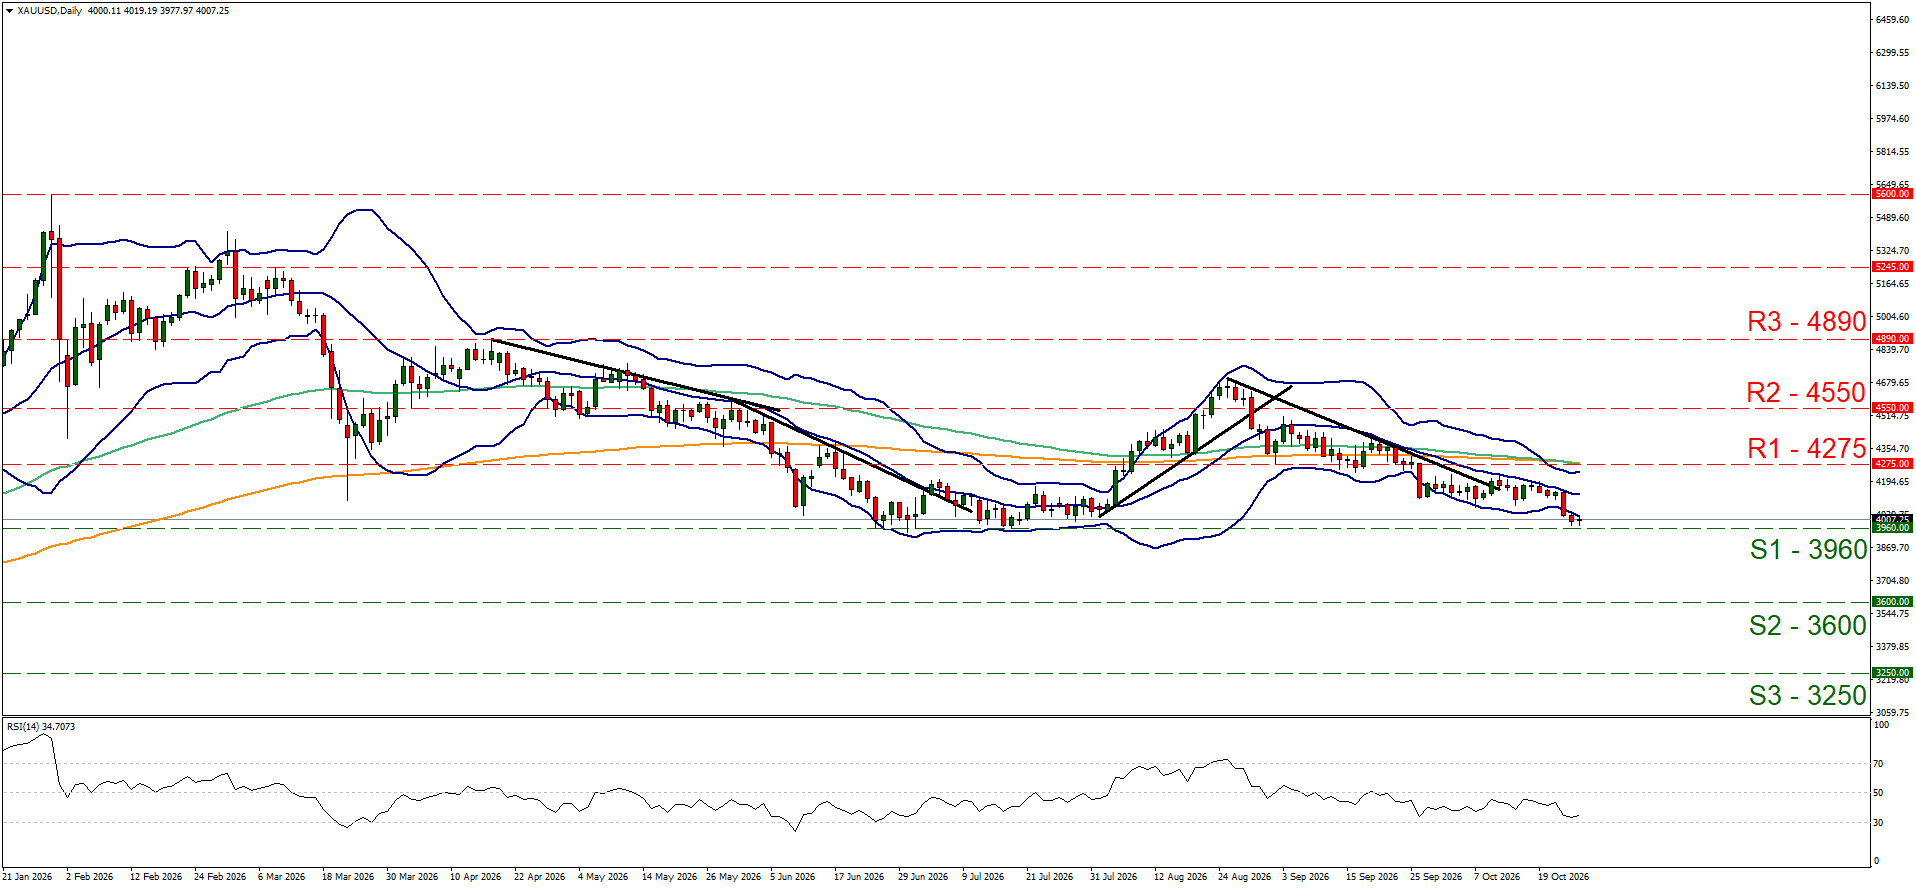
- Support: 3960 (S1), 3600 (S2), 3250 (S3).
- Resistance: 4275 (R1), 4550 (R2), 4890 (R3).
Author

Peter Iosif, ACA, MBA
IronFX
Mr. Iosif joined IronFX in 2017 as part of the sales force. His high level of competence and expertise enabled him to climb up the company ladder quickly and move to the IronFX Strategy team as a Research Analyst. Mr.

















