BoE meeting preview: FTSE 100 reaches a record high as we wait for Bailey
The Bank of England will announce its policy decision later today and release its updated economic forecasts. Th BOE is expected to remain on hold for another month, and the vote split is also expected to remain at 7-2 in favour of holding rates steady. We expect Huw Pill and Megan Greene to vote for a preemptive hike, as they remain concerned about sticky inflation pressures, however, we do not expect any other members to join them in voting for a hike today.
The BOE will also release their updated forecasts for growth and inflation. The focus will be on when the BOE anticipates UK CPI will peak, and how quickly inflation will fall back to target. Complicating the inflation outlook for the UK is the ongoing volatility in energy prices caused by the latest flare up in tensions in the Middle East. A lot has been written about the UK’s energy insecurity, which may be alleviated by the resumption of drilling for gas in the North Sea. It will be interesting to see if Andrew Bailey or anyone else speaks about this during today’s press conference.
As we lead up to today’s meeting, Brent crude oil prices have jumped another 1.4% on Thursday and are back above $89 per barrel. This is $10 higher than where Brent crude oil was trading at the last meeting. Natural gas prices are around $50 higher than they were at the June meeting.
Although inflation risks have risen in recent weeks, we believe that the argument that the BOE should hike rates preemptively to stave off an inflation threat has been neutralized by a spate of weaker economic data that suggests that the UK economy is softening. June CPI data was below the BOE’s forecast, while there are clear signs of slack in the UK labour market. This reduces the chance of a rate hike at this meeting, in our view.
The interest rate futures market is pricing in 2 rate cuts in the next year, and there is currently a 52% chance of a rate hike in September, and a 56% chance of a hike in November. We think that November is more likely, if the BOE is still considering a rate hike at that stage since by that time the committee will have a better idea about 2027 pay awards, and the Budget should have been announced, which will give the MPC a clearer idea of the new PM’s economic policy.
Overall, we expect the BOE to maintain its ‘active hold’ stance at this meeting. There is little need for a rate hike in our view, as Gilt yields and market based interest rates have risen sharply since the last BOE meeting. The 10-year UK Gilt yield is higher by 28bps in the past month, so financial conditions are already tighter than they were earlier in the year.
The market impact: FTSE 100 reaches a fresh record
The backdrop to this meeting is one of rising volatility, especially for US and Asian tech-heavy indices. The South Korean Kospi index has fallen 20% in the past 5 trading sessions, it fell a further 1.5% on Thursday. The Nasdaq 100 fell sharply on Wednesday, along with other US indices, after the Federal Reserve meeting.
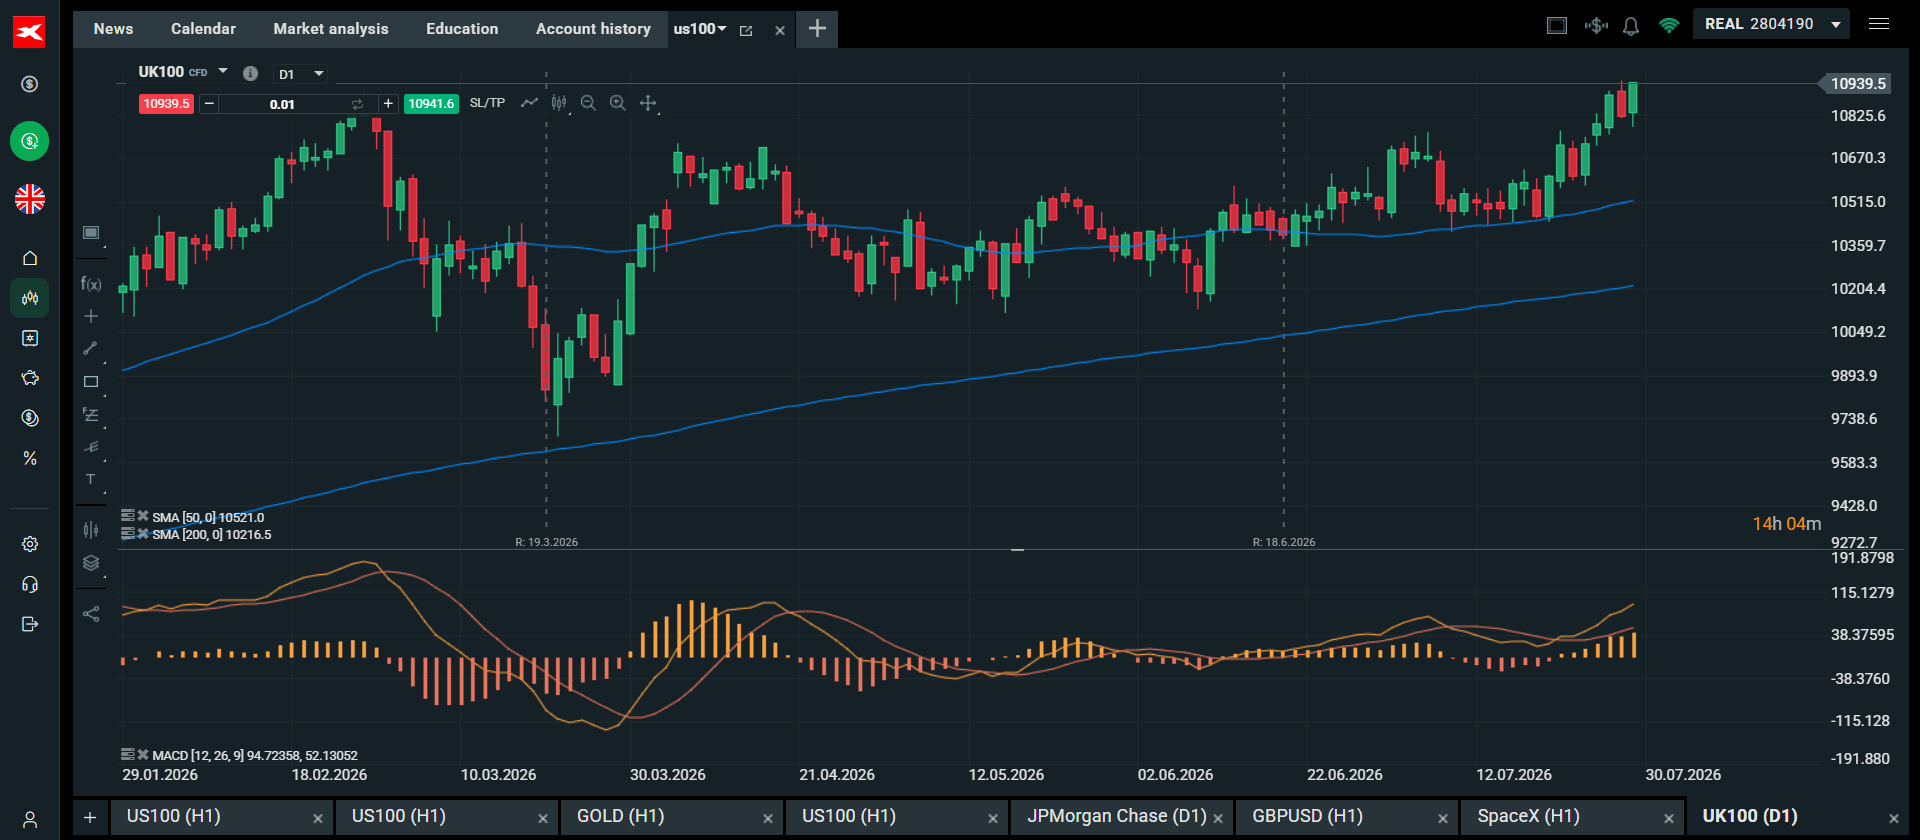
However, in contrast to the turmoil in tech-heavy spaces, the FTSE 100 has surged to a record high, and is higher by 4.5% in the past month. Its mix of energy stocks, defense names and consumer staples are attractive in the current environment. From a technical perspective, the index is above its 50 and 200-day smas, and momentum indicators also suggest that there could be further upside for the UK index as investors rotate away from global tech names.
The FTSE 100 has made a fresh record intra-day high as we lead up to the BOE meeting. If the BOE sticks to an active hold, whilst mentioning the softening in the economic data, then today’s meeting should not have much of an impact on the FTSE 100, with 11,000 now a key target.
Chart 1: FTSE 100 reaches a record high, as we lead up to the BoE meeting
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.

















