BoC seen hiking, markets look for hawkish signals
- Markets price in 80% chance of a 25bp rate hike to 2.50%.
- Higher oil prices and rising inflation expectations support a hawkish outcome.
- Resilient growth offsets trade-related risks.
- BoC decision due Wednesday at 13:45 GMT; Macklem speaks at 14:30 GMT.
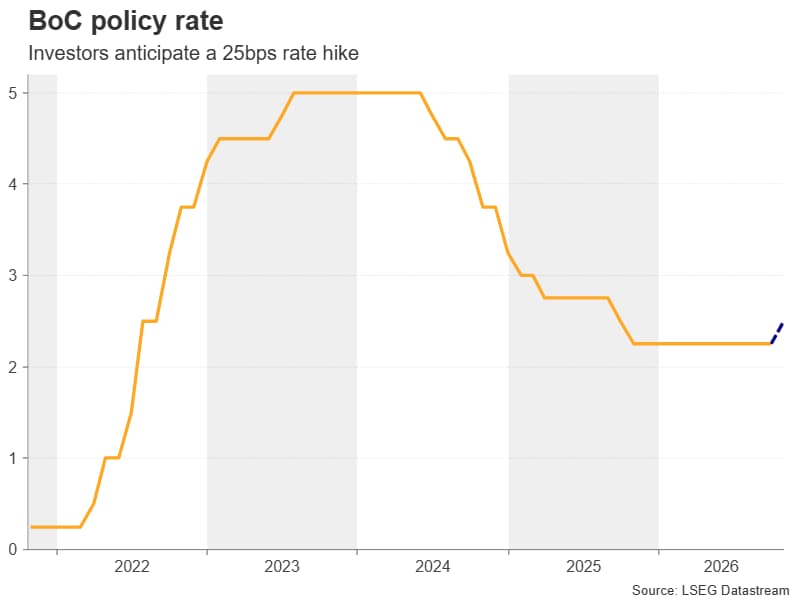
Rate hike largely priced in
The Bank of Canada is widely expected to raise its overnight rate by 25 basis points to 2.50% on Wednesday, October 28, marking its first increase in a year and bringing it into line with a growing number of central banks that have shifted towards tighter policy as policymakers confront renewed inflation risks from higher energy prices.
The policy rate currently stands at 2.25% following a series of holds after the Bank's 25bp cut in October 2025. A Reuters poll found that a majority of economists expect a hike, while overnight index swaps imply roughly a 80% probability of a move. Most economists also anticipate one additional rate increase by the end of March, marking a sharp reversal from earlier expectations that rates would remain unchanged through the end of 2026.
The repricing followed comments by BoC Governor Tiff Macklem, who signalled that inflation forecasts are likely to be revised higher in the upcoming Monetary Policy Report. The BoC's latest business and consumer surveys also revealed rising inflation expectations, reinforcing concerns that higher energy costs could spill into broader pricing pressures.
With a hike now largely priced in, investors are increasingly focused on the Bank's updated forecasts and guidance, which could determine whether markets strengthen expectations for additional tightening beyond this meeting.
Oil-driven inflation remains the key concern
The recent surge in oil prices has become a central theme for policymakers. Brent crude briefly climbed above $117 per barrel this month amid ongoing Middle East tensions, raising concerns that higher energy costs could fuel broader inflationary pressures.
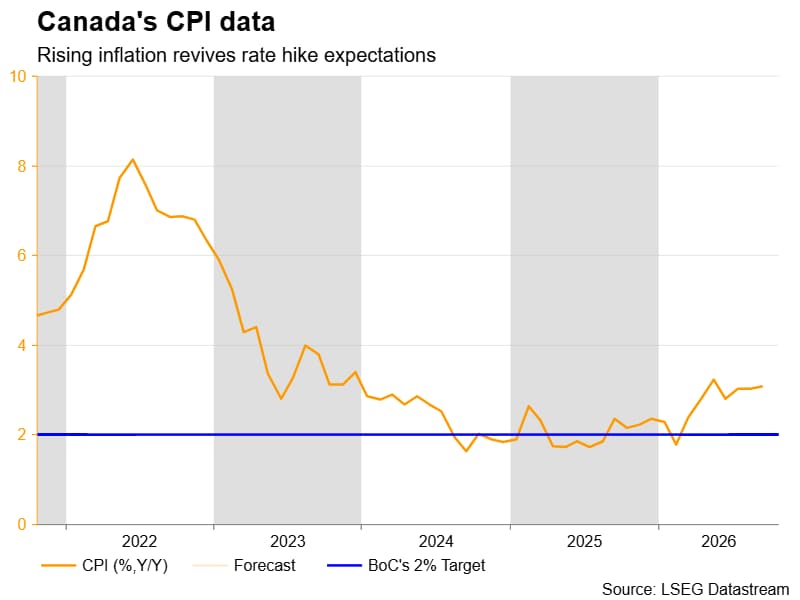
September inflation accelerated to 3.1%, moving above the upper end of the BoC's 1%-3% target range. However, much of the increase reflects higher energy prices, while underlying inflation pressures remain comparatively contained. The challenge for policymakers is whether energy-driven inflation begins to spread more broadly across the economy. Higher fuel prices increase transportation, production and operating costs, creating the risk of second-round effects on prices and wages. The BoC's latest Business Outlook Survey showed rising inflation expectations among firms, reinforcing concerns that inflation could become more persistent over time.
Taken together, higher headline inflation, elevated energy costs and rising inflation expectations have strengthened the case for tighter policy and increased the likelihood that the Bank revises both its inflation and growth forecasts higher this week.
Growth remains resilient despite trade headwinds
Despite the increasingly hawkish tone, the economy has remained more resilient than many expected. Second-quarter GDP growth surprised on the upside at 3.3%, while exports have recovered despite trade tensions with the US following the recent breakdown in trade talks. Consumer demand has also remained firm, with retail sales rising 1.2% in August and a preliminary estimate pointing to a further 0.7% increase in September.
The resilience in growth and spending suggests the economy has absorbed trade-related shocks better than anticipated. Recent data also point to roughly 2% GDP growth in the third quarter, supporting the case for a rate increase this week.
However, policymakers cannot ignore emerging signs of moderation. The BoC's surveys show businesses remain concerned about the impact of tariffs on investment and hiring plans, while Reuters poll medians suggest growth will moderate to 1.0% in 2026 before recovering to 1.7% in 2027.
The labour market has also softened. Employment fell by 68,300 in September, marking a second consecutive monthly decline, while unemployment has edged higher. Wage growth slowed to around 2.3% year-on-year from 3.3% a year earlier, suggesting labour-market pressures are far less intense than during the post-pandemic inflation surge.
USDCAD outlook hinges on guidance
The Canadian dollar has been supported by higher oil prices and rising expectations for a BoC rate increase. Recent repricing has also narrowed the US-Canada two-year yield spread, reducing part of the US dollar's rate advantage.
However, while the Fed is widely expected to leave rates unchanged this week, US inflation remains elevated and markets continue to leave room for additional tightening in the months ahead. By contrast, consensus expectations suggest the BoC may deliver only a limited number of additional hikes after this week's meeting.
As a result, a quarter-point increase is unlikely to materially narrow the US-Canada policy gap much further. Instead, traders will focus on whether policymakers signal further tightening ahead, helping prevent yield differentials from widening further in favour of the US dollar.
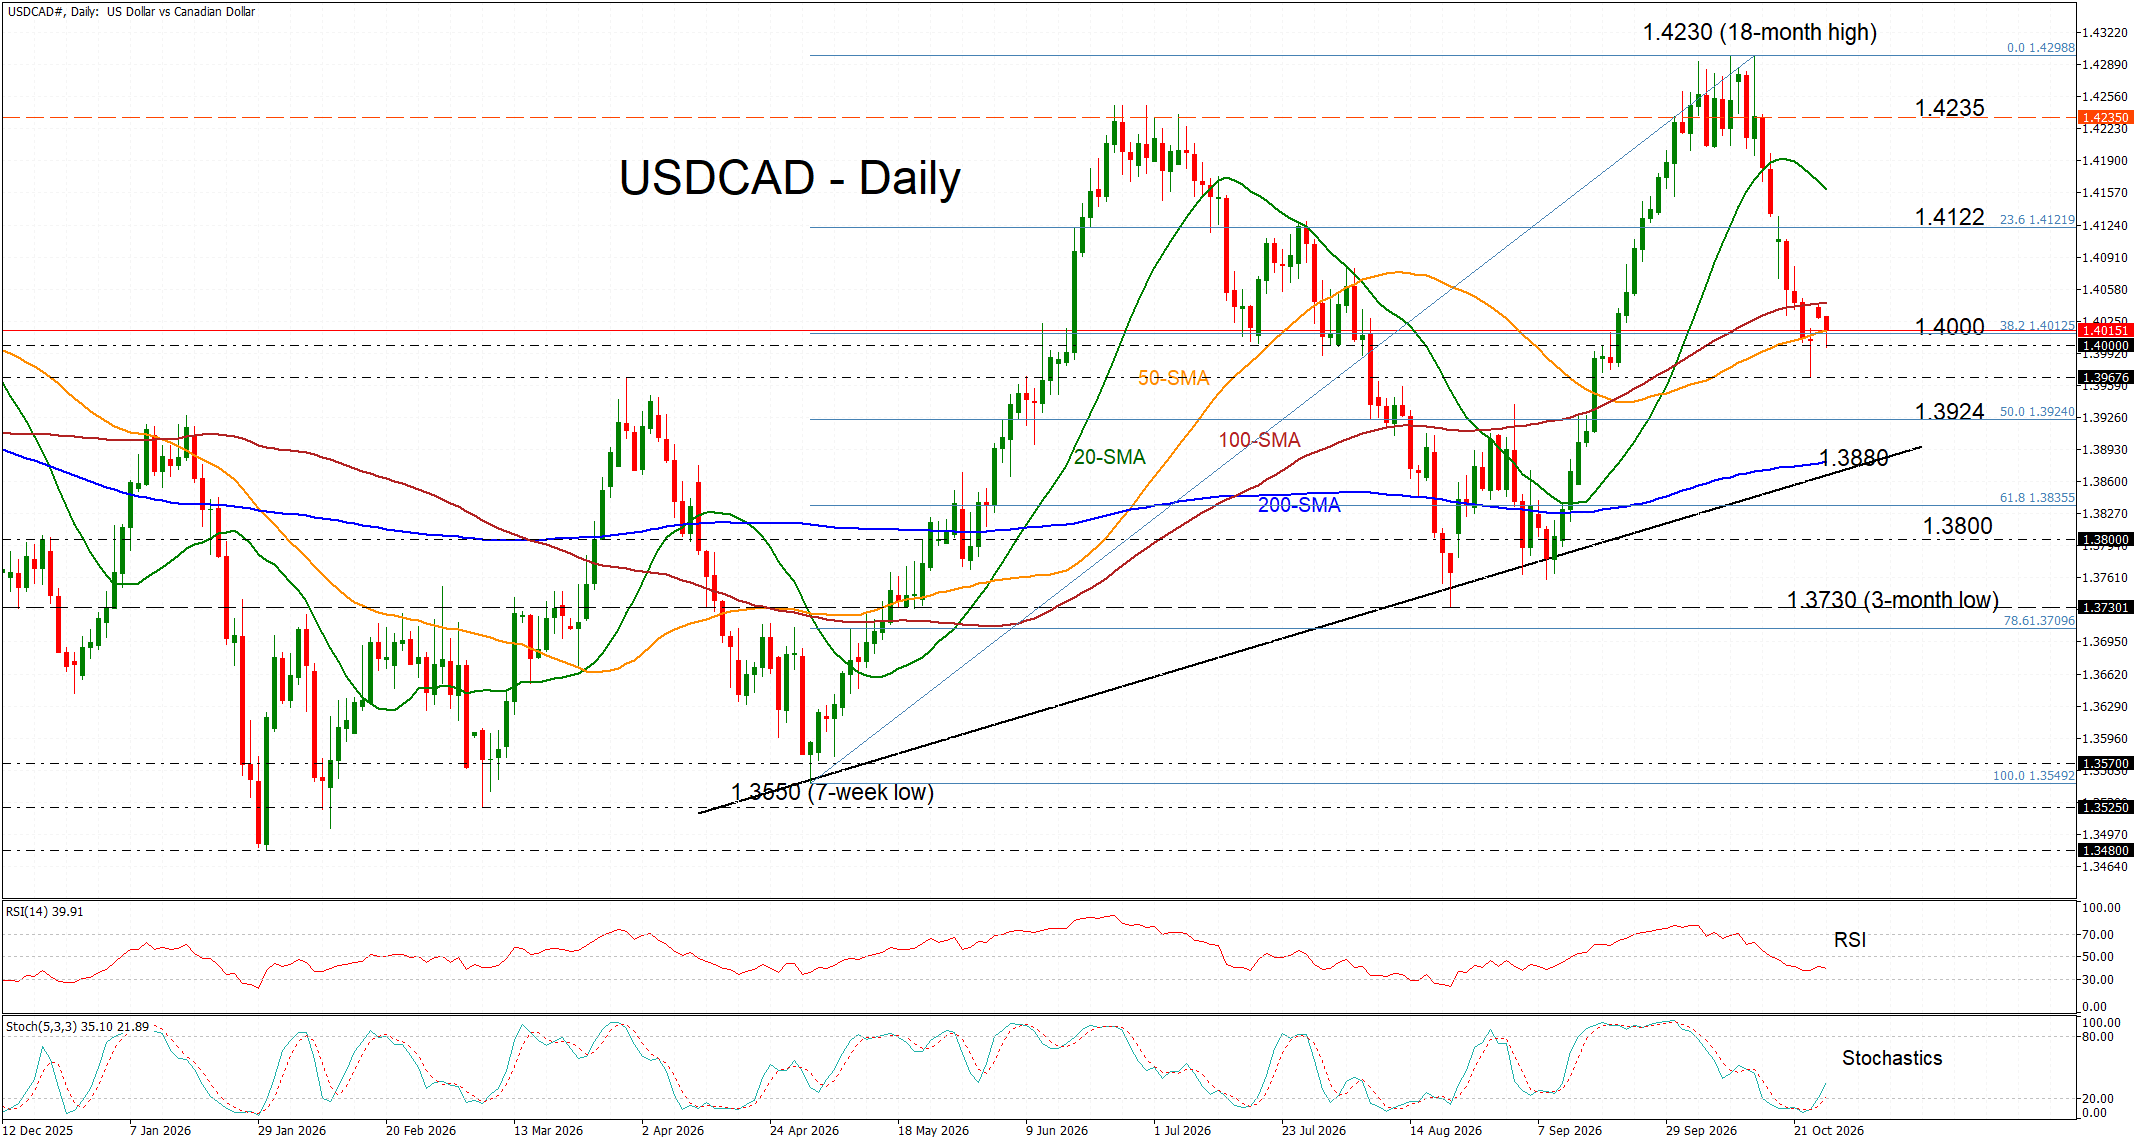
A 25bp hike accompanied by higher inflation forecasts and openness to another increase by March could reinforce the recent narrowing in yield spreads and push USDCAD below 1.4000 towards the 200-day SMA near 1.3880. Conversely, a cautious message could see markets refocus on relatively tighter US policy, allowing USDCAD to rebound towards 1.4100 and potentially the eighteen month-high near 1.4230.
Author

Nicole joined Trading Point as a Market Analyst in January 2025. She holds a BA in English Literature from Kingston University, London, and an MA in Applied Linguistics (Research Methodology) from the University of Southampton with distinction.

















