Bank of England some way off a rate hike despite energy price spike
The Bank of England is poised to keep rates on hold on 30 July despite a rise in energy prices. Expect new forecasts to show inflation peaking around 3% later this year. We think oil and natural gas prices would need to spike a fair bit further for the Bank to hike rates in September.
Higher energy prices won't fully show up in the new forecasts
The rise in energy prices poses a fresh dilemma for the Bank of England, but we still don’t think the bar for a rate hike has been met. We’re expecting another 7-2 vote to keep rates on hold this Thursday.
The Bank’s updated forecasts are likely to show inflation fairly close to 3% in the second half of this year and into early next. And crucially, that’s well below the 4% threshold that the Bank has previously argued is statistically more likely to trigger second-round effects and a longer-lasting bout of price pressure.
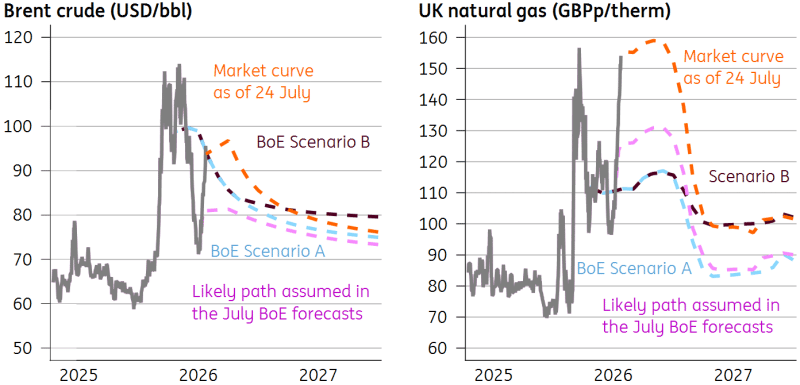
That doesn’t necessarily mean much; those new forecasts almost certainly won’t fully account for the latest rise in energy costs. The Bank typically uses average oil and gas prices over a three‑week observation window, likely beginning in early July. Compared with the Bank's middle 'scenario B' from April, gas prices were only modestly higher in 2026 and lower thereafter, while oil prices were lower across the curve over that time.
Suffice to say those inflation forecasts would be higher if they were based on energy prices today. They would probably show inflation peaking somewhere between 3.5-4%.
How energy prices compare to the BoE's April scenarios
The data supports a 'hold'
Does that mean we’ll see a hawkish shift this Thursday? It would surprise nobody if Catherine Mann, a long-time hawk, joined Huw Pill and Megan Greene in voting for a hike this week. It’s also not totally out of the question that Claire Lombardelli, who previously railed against rate cuts before the Iran War, joined her – though this would be a much bigger surprise.
But even then, there still appears to be a fairly clear dividing line between the hawks and doves. Just as we saw in the debate about rate cuts earlier this year, there are five officials, including Governor Andrew Bailey, who appear much less convinced that the economy is as susceptible to the sort of inflation wave we saw four years ago. And crucially, the recent data appears to back them up.
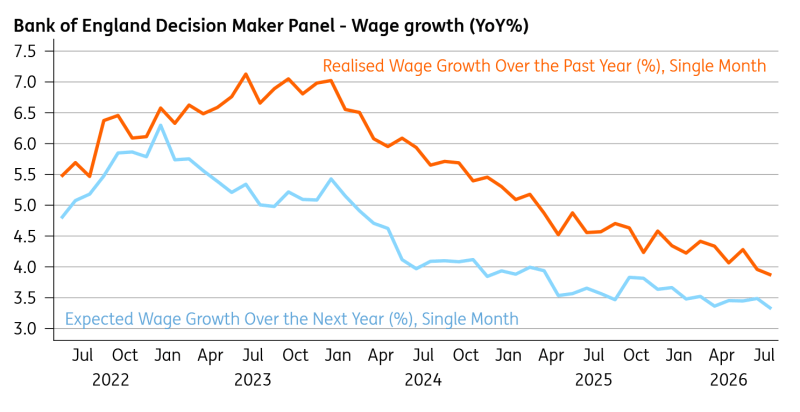
The jobs market remains fragile, best characterised by ‘low hire, low fire’. Private-sector wage growth is below 3%, even if the Bank would argue this has been depressed a bit by so-called ‘compositional effects’ in the data.
Wage growth expectations have fallen since the Iran war
We expect a prolonged hold
Then there’s inflation, which is looking pretty well-behaved. Food inflation is remarkably benign, as it is across much of Europe. And though it will take time, this is an obvious place for higher energy prices to show up if second-round effects take hold. Core services inflation has also been easing. There’s also scant evidence in the surveys that firms are embarking on either bigger price rises or more substantial wage increases.
On that basis, we think energy prices would need to go a fair bit higher to convince more than the four hawks to vote for a hike. Oil prices back to US$120/bbl (from $90 today) – and Dutch TTF natural gas prices up around €80/MWh (from €58) – would take inflation above 4% and would likely trigger some modest tightening.
Though it’s not difficult to see how that could happen if the Strait of Hormuz stays blocked throughout August, our base case is that the Bank stays on hold through 2026. We currently project two rate cuts from the spring of 2027, though this is contingent on there being no material fiscal stimulus at the Autumn Budget.
Author

James Smith
ING Economic and Financial Analysis
James is a Developed Market economist, with primary responsibility for coverage of the UK economy and the Bank of England. As part of the wider team in London, he also spends time looking at the US economy, the Fed, Brexit and Trump's policies.