Australian Dollar Price Forecast: Blame the RBA
- AUD/USD has breached below 0.7000, hitting fresh two-week lows.
- The US Dollar alternates gains with losses amid US elections uncertainty.
- The RBA hiked its OCR by 25 basis points to 4.85%, as expected.
The Australian Dollar (AUD) has traded on the back foot on Tuesday, prompting AUD/USD to add to Monday’s decline and reach new two-week lows near 0.6960.
The pair’s re-emergence of the downside pressure has come amid marginal gains in the US Dollar (USD), although the bulk of the reason should be found in the bulls’ disappointment after the RBA hiked its policy rate to 4.85% early on Tuesday, failing to signal, in a convincing fashion, that more hikes might be coming soon.
Looking at the broader picture, AUD/USD remains below its key 200-day SMA near 0.7060, with a sustained recovery above that level needed to improve the near-term outlook. In the meantime, persistently high inflation in Oz should help limit the scope for a deeper correction.
Australia holds up, but cracks are showing
Australia’s economy continues to compare favourably with many of its G10 peers, supported by domestic demand and positive economic growth. Persistent inflation also supports the RBA’s cautious, data-dependent policy stance.
However, business activity seems to have lost some momentum after preliminary data showed the Purchasing Managers’ Index (PMI) for Manufacturing improving marginally to 49.5 in September and easing to 47.8 when it comes to Services, from 49.6 and 51.9, respectively.
Trade data provided another positive, albeit humble, signal after August’s trade surplus came in at just A$0.495 billion, adding to the A$1.351 billion surplus registered in the previous month (revised from A$1.923 billion).
Growth figures were less encouraging, however. Indeed, the Gross Domestic Product (GDP) expanded by 0.4% QoQ in the second quarter of 2026, up from 0.3%, while annual growth came in at 2.1%, down from the previous 2.5% yearly expansion.
The labour market, however, disappointed investors in September after the Unemployment Rate held steady at 4.7% (August’s print was revised higher to 4.7% from 4.6%), while the Employment Change shrunk by 39.3K, reversing August’s 29.3K increase (revised from 39.5K).
Inflation seems to have regained some impulse after the latest data showed the most-watched Trimmed Mean CPI came in at 3.7% over the last twelve months in Q3, while the headline CPI held steady at 3.9% from a year earlier.
The Melbourne Institute’s Consumer Inflation Expectations measure reinforced that trend after ticking higher to 5.3% in October.
The figures leave the RBA’s inflation task incomplete. Policymakers expect inflation to return to target only in early 2028, keeping the emphasis on patience rather than an imminent policy pivot.
China offers the Aussie a helping hand
China is providing stability for the Australian economy, but not the growth impulse that has underpinned the Australian Dollar during previous expansions.
The Chinese economy grew 4.5% YoY in the July-September period. Industrial Production grew by 5.5% YoY and 5.3% YDT, regaining the momentum. The latest trade data showed a surplus of $133.53 billion in September, as both imports and exports posted strong gains. Reinforcing this picture, consumer spending remained solid after Retail Sales expanded by 1.1% over the last twelve months.
In addition, business surveys presented a promising picture: the National Bureau of Statistics reported that the Manufacturing PMI improved to 50.1 in September (from 49.8), while the Services PMI improved to 50.2 (from 49.0). In the same direction, private measures like RatingDog remained in expansionary territory, with Manufacturing at 52.1 (from 51.5) and Services at 51.6 (from 51.4).
Disinflationary pressures seem to have taken a breather in September, with the CPI gaining 0.9% from a year earlier, up from 0.8%, while prices rose by 0.2% on a monthly basis. Producer Prices rose more than initially estimated by 5.0% over the previous twelve months, up from the 3.8% increase recorded in the previous month.
As widely anticipated, the People’s Bank of China (PBoC) kept its Loan Prime Rates (LPR) unchanged at 3.00% for the one-year tenor and 3.50% for the five-year tenor.
Taken together, the latest Chinese data offer some encouragement for Australia and the Aussie, although the recovery has yet to develop the kind of momentum that could provide the currency with a more lasting boost.
RBA delivers a divided hike but keeps its next move open
The RBA raised its cash rate by 25 basis points to 4.85% in a 6-3 decision after sharply lifting its inflation forecasts. Headline CPI is now expected to peak at 4.5% and stay above 3% until late 2027. Trimmed-mean inflation is forecast at 3.6% in the final quarter of 2026, easing only gradually thereafter.
The Bank said price pressures were no longer confined to a few areas. Domestic capacity constraints, rents, services and durable goods are all contributing, while higher fuel costs are beginning to feed through to other prices. The AI investment boom is adding further pressure to technology-related goods and global demand. Michele Bullock said the hike was needed, although she stressed that the economy was not showing signs of cracking and that Australia was not facing a wage-price spiral.
Bullock left the next move open. Another increase may be required, but the Board wants to see how the latest hike works through the economy before deciding. For now, the RBA is accepting some weaker growth and a higher unemployment rate as the price of preventing today’s inflation from becoming tomorrow’s problem.
AUD/USD struggles to find its next catalyst
Baseline outlook
A further sidelined mood should not be ruled out in the short-term horizon. In the meantime, and looking at the broader picture, the pair should face a steady chance of further declines while below the 200-day SMA around 0.7060.
The resumption of the bullish bias will likely require a strong catalyst, namely a sustained improvement in risk appetite trends or renewed and persistent weakness in the Greenback.
Upside scenario
A sustained improvement in risk appetite could help AUD/USD regain the 200-day SMA near 0.7060. Beyond that, the weekly top at 0.7140 (September 21) would emerge as the next hurdle, ahead of the 2026 peak around 0.7280 (May 6).
Downside scenario
In case bears regain control of sentiment surrounding the Aussie, there should be initial support at the October valley of 0.6894 (October 15). A breach below this level would increase the likelihood of a retest of the June bottom near 0.6860 (June 30).
Bears hold control, but the trade is running out of steam
AUD bearish positioning was broadly unchanged in the week ending October 27, according to the Commodity Futures Trading Commission (CFTC) data. That said, speculative net shorts increased to around 128.3K contracts, while the weekly decline eased sharply to just over -1K contracts. In addition, the four-week change improved to nearly -65.1K contracts, suggesting that the broader bearish momentum is beginning to moderate, although it remains firmly negative.
Furthermore, open interest fell to around 325K contracts. That said, with net shorts deepening only marginally as participation declined, the latest move looks more like a continued adjustment of existing positions rather than a fresh wave of aggressive short-building.
Speculative exposure became more negative at -39.5%, while its percentile fell to 21. The Net Position Percentile remained around 0.0, confirming that the absolute net-short position is still at an extreme historical level. However, the lower exposure percentile suggests that short positioning relative to open interest is not historically stretched.
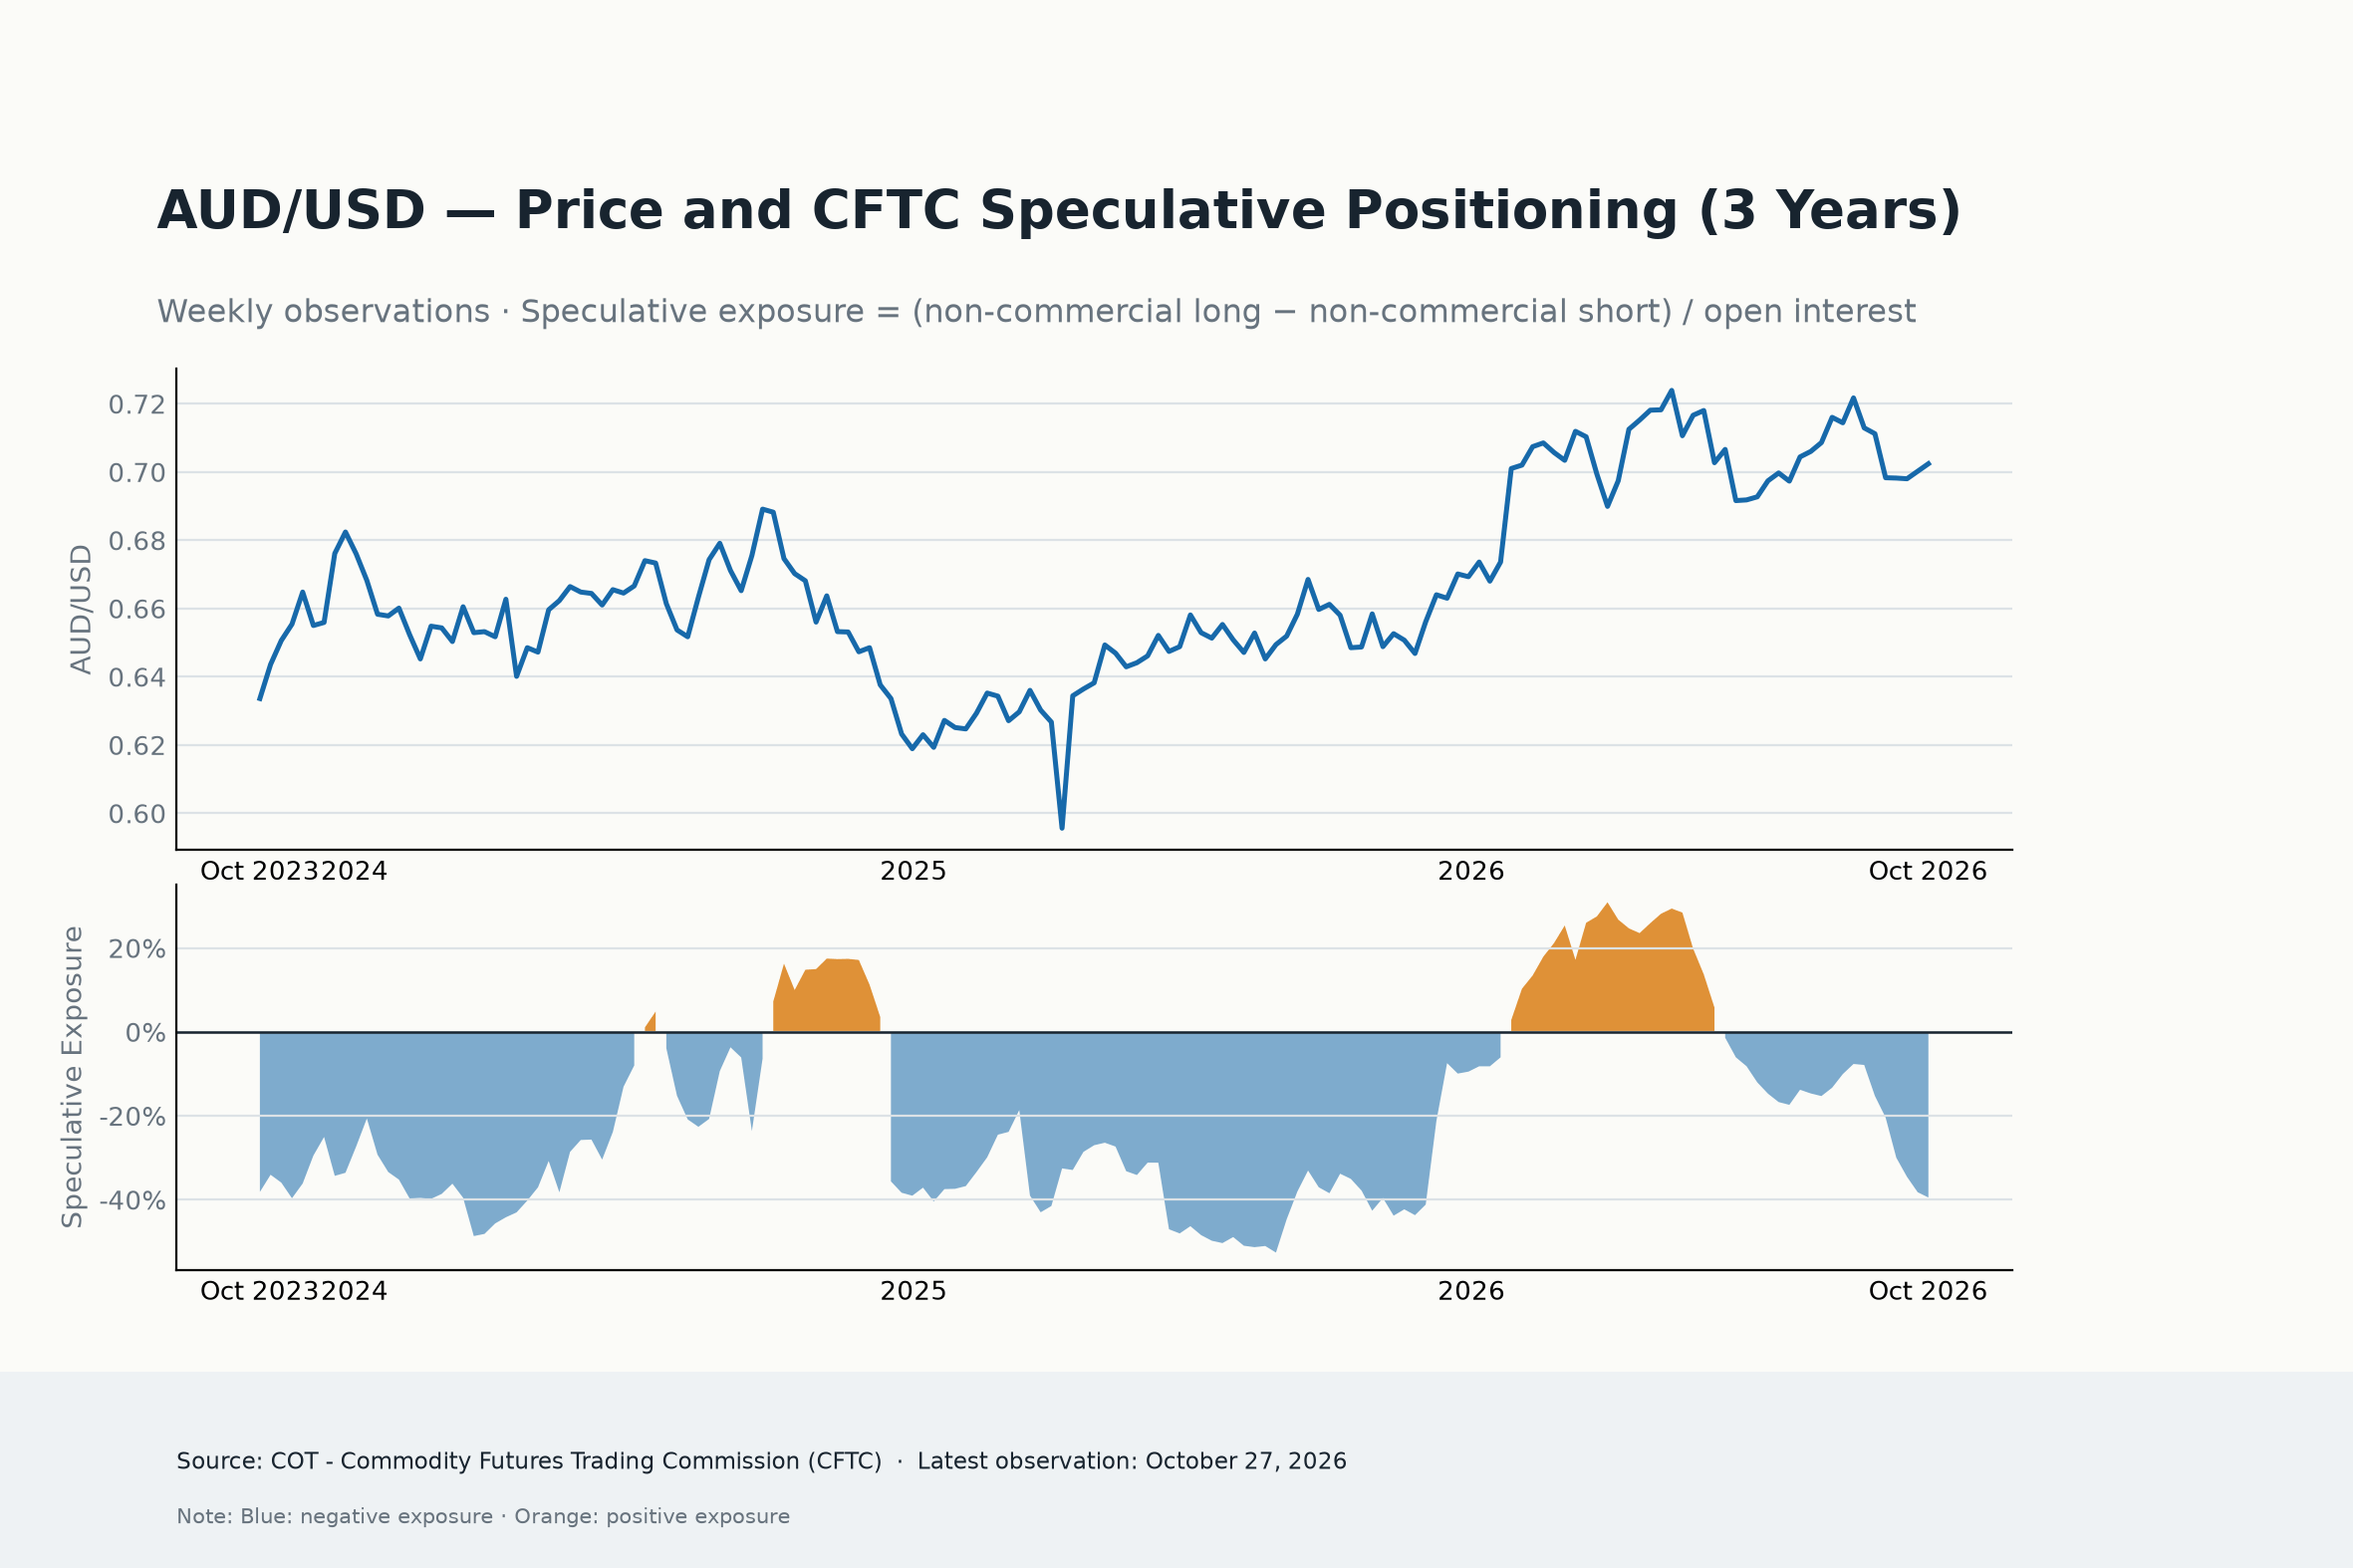
Overall, AUD positioning remains decisively bearish, although the signal has become less forceful. The record-level net-short position continues to weigh on the currency, yet the slower weekly deterioration, falling open interest and improved four-week change suggest that the bearish trend may be losing momentum and that a squeeze risk is increasing.
US elections and jobs data will take centre stage
US Dollar dynamics, global risk sentiment, and geopolitical developments remain the main near-term drivers of AUD/USD.
Next on tap on the domestic calendar will be the release of Household Spending figures, although all the attention is expected to remain on the US and the results of the Midterm elections, ahead of the release of key data from the labour market.
Beyond that, the main risks are expected to emerge from China, a persistently cautious Fed, a deterioration in investor risk appetite or a change in the RBA’s current policy stance.
Any of these developments could quickly alter the outlook for the Australian currency.
Technical analysis
In the daily chart, AUD/USD trades at 0.6971, keeping a bearish near-term tone as it holds beneath the 100-day simple moving average (SMA) at 0.7031 and the 200-day SMA at 0.7058, with the 55-day SMA further above at 0.7067. This stacked overhead structure suggests rallies remain capped for now, while the Relative Strength Index at 42 stays below the midline, hinting at still-soft momentum as the Average Directional Index near 22 points to only modest trend strength.
On the topside, initial resistance appears at the 0.7031 100-day SMA, followed by the 200-day SMA at 0.7058 and the 55-day SMA at 0.7067, with a higher horizontal barrier at 0.7079 before the broader caps at 0.7278, 0.7283 and 0.7661. On the downside, first notable support is aligned at the 0.6833 horizontal level, ahead of deeper cushions at 0.6660 and 0.6593, with 0.6414 and 0.6373 marking more distant downside levels should selling pressure intensify.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
All in all
The AUD remains caught between a RBA that is still wrestling with stubborn inflation and an external environment that offers little room for complacency. Australia's relatively resilient economy and encouraging signs from China provide some support, although the Greenback and broader risk sentiment are likely to have the final say on the currency's near-term direction.
What makes the current picture particularly interesting is the positioning backdrop. Speculative shorts remain historically stretched, yet the Aussie's recent recovery has received some confirmation from options markets, even if bullish conviction remains far from convincing. That leaves sellers increasingly exposed to a short-covering rebound, rather than pointing to a decisive change in trend.
The next meaningful catalyst may be at the RBA meeting on November 3. Another rate rise would boost the bank's hawkish credentials and perhaps provide some support to the Aussie.
However, the near-term outlook remains cautiously neutral with a slight downside bias as the broader recovery struggles to gain traction. A more convincing rebound is likely to need a friendlier US Dollar and improvement in global risk appetite.
RBA FAQs
The Reserve Bank of Australia (RBA) sets interest rates and manages monetary policy for Australia. Decisions are made by a board of governors at 11 meetings a year and ad hoc emergency meetings as required. The RBA’s primary mandate is to maintain price stability, which means an inflation rate of 2-3%, but also “..to contribute to the stability of the currency, full employment, and the economic prosperity and welfare of the Australian people.” Its main tool for achieving this is by raising or lowering interest rates. Relatively high interest rates will strengthen the Australian Dollar (AUD) and vice versa. Other RBA tools include quantitative easing and tightening.
While inflation had always traditionally been thought of as a negative factor for currencies since it lowers the value of money in general, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Moderately higher inflation now tends to lead central banks to put up their interest rates, which in turn has the effect of attracting more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in the case of Australia is the Aussie Dollar.
Macroeconomic data gauges the health of an economy and can have an impact on the value of its currency. Investors prefer to invest their capital in economies that are safe and growing rather than precarious and shrinking. Greater capital inflows increase the aggregate demand and value of the domestic currency. Classic indicators, such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can influence AUD. A strong economy may encourage the Reserve Bank of Australia to put up interest rates, also supporting AUD.
Quantitative Easing (QE) is a tool used in extreme situations when lowering interest rates is not enough to restore the flow of credit in the economy. QE is the process by which the Reserve Bank of Australia (RBA) prints Australian Dollars (AUD) for the purpose of buying assets – usually government or corporate bonds – from financial institutions, thereby providing them with much-needed liquidity. QE usually results in a weaker AUD.
Quantitative tightening (QT) is the reverse of QE. It is undertaken after QE when an economic recovery is underway and inflation starts rising. Whilst in QE the Reserve Bank of Australia (RBA) purchases government and corporate bonds from financial institutions to provide them with liquidity, in QT the RBA stops buying more assets, and stops reinvesting the principal maturing on the bonds it already holds. It would be positive (or bullish) for the Australian Dollar.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.

















