|

Asia week ahead: BoK rate decision, data from China, Taiwan, Japan
Asia Research Highlights of the week

China’s October domestic activity data disappoints across the board

Asia Outlook 2027: Growth broadens, capital gets selective

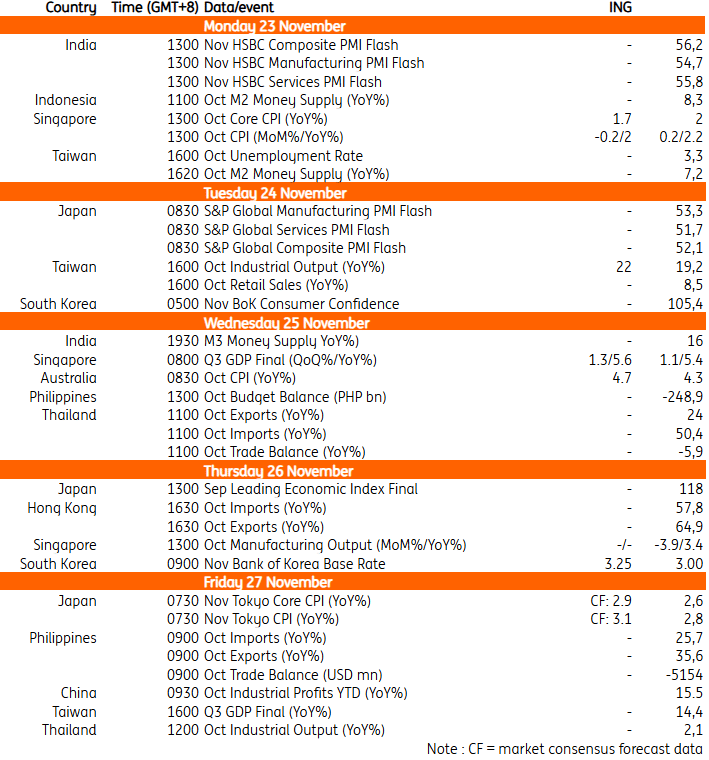
Korea: BOK expected to hike rates by 25bp

The Bank of Korea is expected to raise its policy rate by 25bp to 3.25% on Wednesday, marking the third hike of the current tightening cycle. Inflation remains above target, with both headline and core CPI holding at 2.8% year-on-year in October, while robust semiconductor exports continue to underpin growth. At the same time, a moderation in household credit growth suggests earlier rate hikes are beginning to tighten financial conditions.

China: Industrial profits recovery remains uneven

China will release October industrial profits on Friday. While profits have generally recovered over 2026, the rebound remains uneven. Gains have been concentrated in AI- and electronics-related industries and upstream commodity producers, while automakers, construction-linked sectors, and many consumer-facing manufacturers continue to face significant pressure. Soft domestic demand is likely to keep these sectors under pressure in the October data.

Taiwan: Technology supports industrial production growth

Taiwan will release October industrial production data. We expect output growth to accelerate to 22.0% YoY, driven primarily by continued strength in the technology sector. Outside of tech, however, activity is likely to remain more subdued. A strong reading would reinforce expectations for solid economic growth in the fourth quarter.

Japan: Tokyo inflation expected to strengthen

Japan will release November Tokyo CPI data on Thursday. Consensus forecasts headline inflation to accelerate to 3.1% YoY from 2.8% in October, while core inflation is expected to rise to 2.9% YoY from 2.6%. A broadly in-line reading would suggest underlying price pressures remain firm and reinforce our expectations for a Bank of Japan rate hike in December.

Key events in Asia next week
Chart

Read the original analysis here

Author

ING Global Economics Team

ING Global Economics Team

ING Economic and Financial Analysis

From Trump to trade, FX to Brexit, ING’s global economists have it covered. Go to ING.com/THINK to stay a step ahead.


More from ING Global Economics Team
Share:

Editor's Picks

AUD/USD bears retain control near YTD low, 0.6650 tested

AUD/USD sits at fresh YTD lows near 0.6550 in Friday's Asian session and looks vulnerable to further downside. The US Dollar holds near April 2025 highs amid renewed US-Iran tensions and aggressive Fed rate-hike bets. Moreover, Thursday’s dismal Aussie jobs data, the RBA’s dovish tilt and PBOC's status-quo continue to weigh on the Aussie, validating the negative outlook for the currency pair.

USD/JPY drops below 159.50 after Japan’s National CPI

USD/JPY has turned south below mid-159.00s in the Asian session on Friday, as the Japanese Yen gains ground following the country's National CPI, which reaffirmed the December BoJ rate hike. Further, a broader risk-off market environment lifts the Yen's safe-haven appeal. However, hawkish Fed outlook and renewed US-Iran tensions keep the US Dollar supported, which could limit the pair's downside.


Gold: The $3,500 zone holds the downside… for now

Gold further extends its deep pullback, coming close to the key $3,500 mark per troy ounce as Friday’s European session draws to a close. Furthermore, the yellow metal has traded with losses since Monday, always tracking rising bets for extra tightening by the Fed and the lack of any progress from the Middle East conflict.

Bitcoin slips below $60,000 as selling pressure accelerates

Bitcoin price slips below $60,000 on Friday, reaching a level not seen since early July. Momentum indicators suggest firm selling pressure despite reaching oversold levels.

Week ahead – Flash PMIs and PCE inflation in focus ahead of Thanksgiving

US flash PMIs and PCE inflation data could shape Fed rate expectations. Eurozone and UK PMIs will offer an early look at business activity. Australia’s CPI data could influence expectations for the RBA’s next move.

Gold's 14-month low looks mild next to Silver's fall from $121 to $44
Gold has lost a third of its value since January as traders bet on more Federal Reserve rate increases. Silver has lost nearly two-thirds, because the buyers still holding Gold up have no equivalent in the Silver market. Gold is trading below $3,700 for the first time since September 2025, a little more than a third under the record near $5,600 it set in late January.















