A delicate balance
An interesting setup is unfolding at the moment: US longer-term yields keep pushing higher, to multi-decade highs, but the major US indices are unfazed. The US 10-year yield reached 5.35% yesterday, as the S&P500 traded just shy of an all-time high. Even the equal-weighted version rose, suggesting that the rally was not driven solely by technology stocks. Meanwhile, the Nasdaq advanced to a fresh record high, despite the latest warning from SoftBank’s Masayoshi Son—who is a firm tech believer! He warned that superintelligence in the wrong hands could become ‘super dangerous’, joining other leaders who, in recent weeks, have called for slowing the development of their most powerful models.
Alas, AI companies are stuck with debt and liabilities, and cannot slow down much. And the data show that AI demand remains robust. Hon Hai Precision—a supplier to Nvidia and Apple—announced better-than-expected quarterly revenue yesterday. The news offered further confirmation that the AI buildout is growing fast enough to help shield related companies and industries from rising yields. How high yields must rise to challenge growth remains to be seen. For now, US technology stocks seem unworried.
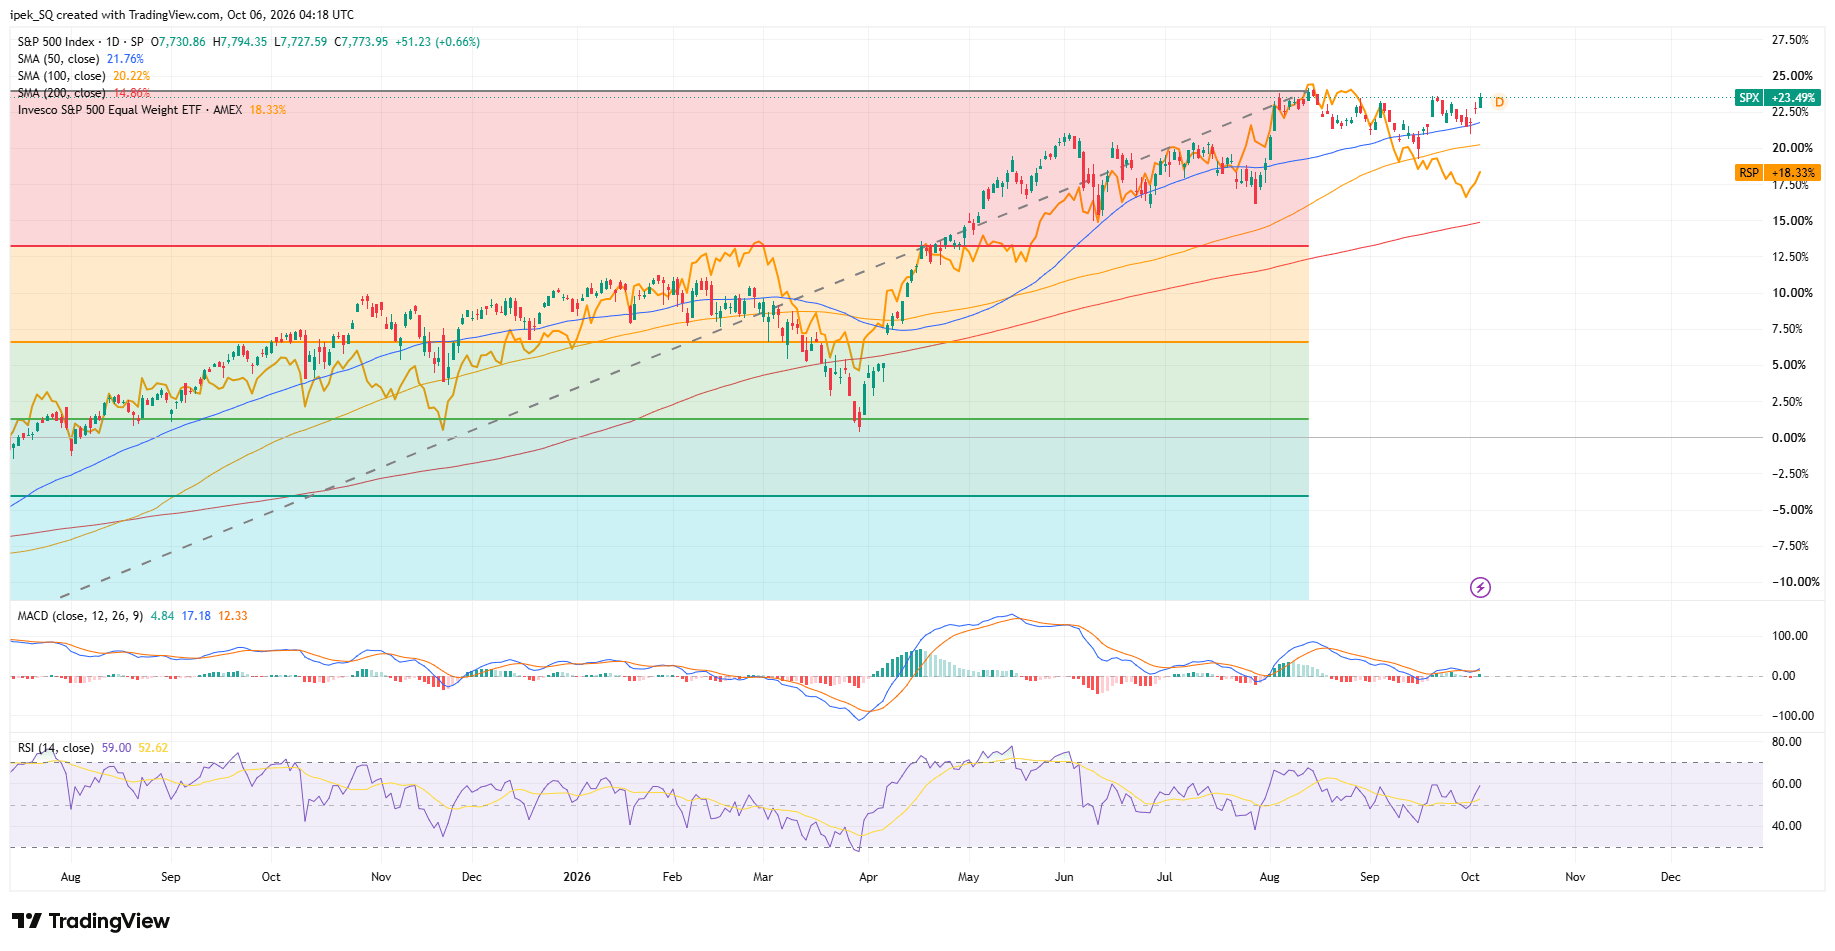
They could perhaps absorb another 50–100bp rise in yields, but of course, the higher borrowing costs move, the greater the pressure on their profitability outlook. For now, the growth outlook remains the major driver, but there will surely be a tipping point when investors say, ‘OK—we’re moving into bonds.’ Especially if the rise in bond yields is mainly driven by real yields, while long-term inflation expectations remain relatively well anchored.
Read the full article here.
Author

Ipek Ozkardeskaya
ipekScope
Ipek Ozkardeskaya began her financial career in 2010 in the structured products desk of the Swiss Banque Cantonale Vaudoise. She worked in HSBC Private Bank in Geneva in relation to high and ultra-high-net-worth clients.

















