WTI Oil Price Forecast: Momentum turns flat as Bollinger Bands expand
- WTI Oil edges lower as weaker demand forecasts from OPEC and the IEA weigh on sentiment.
- Persistent disruption in the Strait of Hormuz keeps supply risks elevated and limits the downside.
- WTI trades below the 20-day SMA, while RSI and MACD point to limited directional momentum.
West Texas Intermediate (WTI) Oil trades modestly lower on Thursday as traders weigh weaker demand forecasts from OPEC and the International Energy Agency (IEA) against supply disruptions in the Middle East. At the time of writing, WTI trades around $80.50 per barrel, down 1.35% on the day.
There are still no signs that the Strait of Hormuz will reopen soon, with both the United States and Iran claiming control of the waterway. Commercial shipping remains well below pre-war levels, keeping a geopolitical risk premium embedded in energy prices and limiting WTI’s decline.
OPEC now expects global Oil demand to grow by 580,000 bpd in 2026, down from its previous forecast of 780,000 bpd. The IEA is considerably more bearish, forecasting demand to fall by 1.6 million bpd over the same period.
Meanwhile, the technical picture points to neutral momentum despite heightened price volatility.
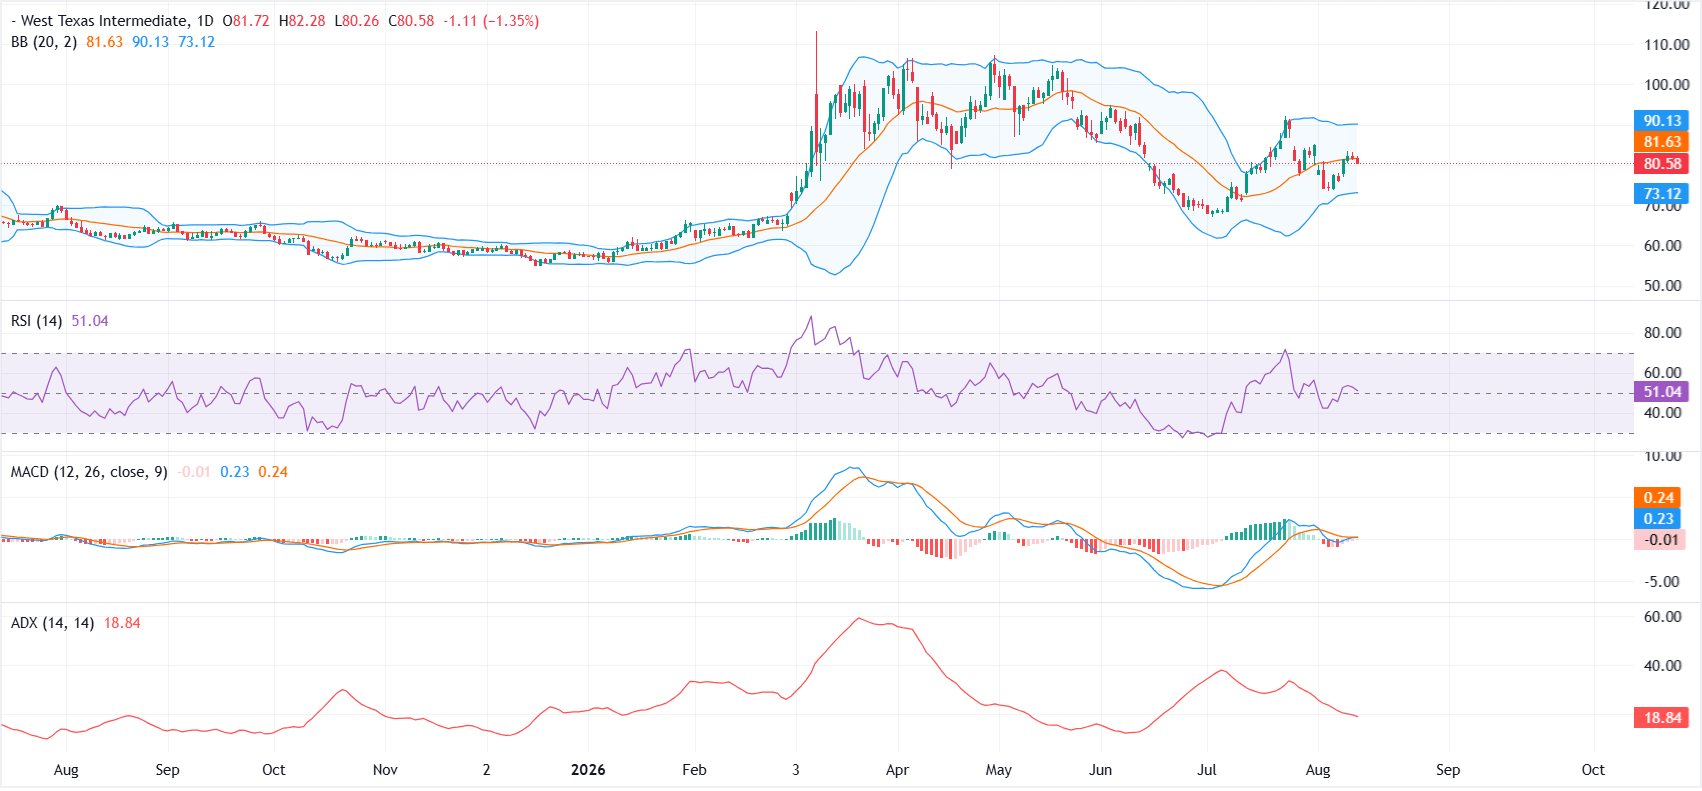
On the daily chart, WTI Oil retains a modest bearish bias as it trades below the 20-day Bollinger Band Simple Moving Average (SMA) at $81.63. The widening Bollinger Bands point to rising volatility, with the upper band at $90.13 and the lower band at $73.12.
The Relative Strength Index (RSI) hovers near the neutral 50 mark, while the Moving Average Convergence Divergence (MACD) indicator flattens around the zero line. Both indicators suggest that directional momentum is limited despite increased price swings.
On the upside, immediate resistance is located at the 20-day SMA at $81.63. A sustained break above this level could expose the upper Bollinger Band at $90.13. On the downside, the lower band at $73.12 offers the next notable support if the decline extends.
(The technical analysis of this story was written with the help of an AI tool. Know more.*)
WTI Oil FAQs
WTI Oil is a type of Crude Oil sold on international markets. The WTI stands for West Texas Intermediate, one of three major types including Brent and Dubai Crude. WTI is also referred to as “light” and “sweet” because of its relatively low gravity and sulfur content respectively. It is considered a high quality Oil that is easily refined. It is sourced in the United States and distributed via the Cushing hub, which is considered “The Pipeline Crossroads of the World”. It is a benchmark for the Oil market and WTI price is frequently quoted in the media.
Like all assets, supply and demand are the key drivers of WTI Oil price. As such, global growth can be a driver of increased demand and vice versa for weak global growth. Political instability, wars, and sanctions can disrupt supply and impact prices. The decisions of OPEC, a group of major Oil-producing countries, is another key driver of price. The value of the US Dollar influences the price of WTI Crude Oil, since Oil is predominantly traded in US Dollars, thus a weaker US Dollar can make Oil more affordable and vice versa.
The weekly Oil inventory reports published by the American Petroleum Institute (API) and the Energy Information Agency (EIA) impact the price of WTI Oil. Changes in inventories reflect fluctuating supply and demand. If the data shows a drop in inventories it can indicate increased demand, pushing up Oil price. Higher inventories can reflect increased supply, pushing down prices. API’s report is published every Tuesday and EIA’s the day after. Their results are usually similar, falling within 1% of each other 75% of the time. The EIA data is considered more reliable, since it is a government agency.
OPEC (Organization of the Petroleum Exporting Countries) is a group of 12 Oil-producing nations who collectively decide production quotas for member countries at twice-yearly meetings. Their decisions often impact WTI Oil prices. When OPEC decides to lower quotas, it can tighten supply, pushing up Oil prices. When OPEC increases production, it has the opposite effect. OPEC+ refers to an expanded group that includes ten extra non-OPEC members, the most notable of which is Russia.
Author

Vishal Chaturvedi
FXStreet
I am a macro-focused research analyst with over four years of experience covering forex and commodities market. I enjoy breaking down complex economic trends and turning them into clear, actionable insights that help traders stay ahead of the curve.
















