What is giving the Japanese Yen room to appreciate across Asia-Pacific currencies?
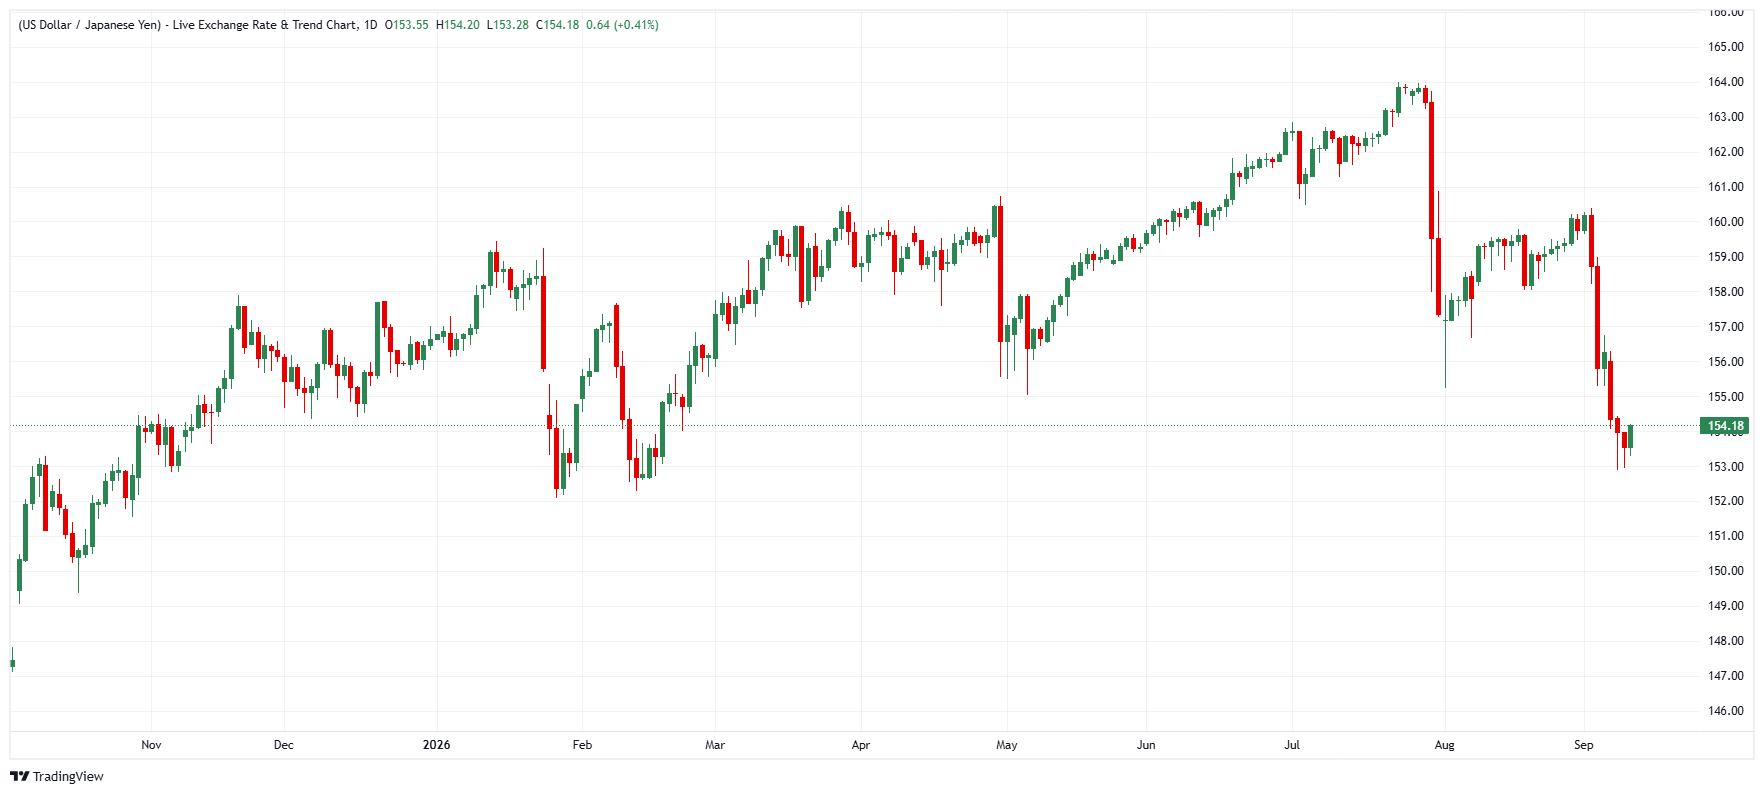
The Japanese Yen (JPY) continues to play a central role in reshaping broader macro dynamics, with its recent appreciation easing trade-weighted exchange rate pressures across Asia-Pacific (APAC) currencies and creating room for nominal appreciation in regional peers. While US Treasury Secretary Scott Bessent's comments regarding "asymmetric information" on Bank of Japan (BoJ) policy decisions have effectively deterred speculative positioning for a weaker Yen, institutional analysts caution that near-term upside may be constrained. With financial markets already fully pricing in a BoJ rate hike next week, further currency gains hinge on concrete policy delivery from Japanese central bankers and the absence of renewed global energy shocks.
Yen appreciation relieves regional FX pressure and opens space for APAC gains
According to Geoff Yu at BNY, the Yen's trade-weighted importance across Asia has allowed its recent strength to function as a relief valve for neighboring economies. By offsetting US Dollar legs and lowering effective exchange-rate headwinds, a firmer Japanese Yen provides scope for regional currencies to strengthen, provided current-account support holds and crude oil prices remain contained.
"JPY’s move and U.S. tolerance for clear dollar weakness has created space for the rest of the region to appreciate their own currencies in nominal terms: a stronger JPY offsets any gains on the dollar leg, and strong current U.S. inflation also prevents excessive dollar weakness in real terms... Stay structurally constructive on JPY, KRW and CNY while current-account support holds, but monitor energy prices closely: a renewed oil shock would weaken regional FX and raise the risk of further reserve-asset liquidation."
High BoJ expectations and US verbal signals limit near-term JPY upside
Taking a tactical perspective, Michael Pfister at Commerzbank observes that while unusual statements from US Treasury officials have successfully cautioned traders against shorting the Japanese Yen, high market expectations create a high bar for further USD/JPY downside. With a September BoJ rate hike fully discounted by interest rate markets, policymakers must follow through with concrete rate increases to sustain the Yen's upward momentum.
"The US Treasury Secretary recently claimed to have “asymmetric information” regarding the Bank of Japan’s next moves... An interest rate hike next week is now fully priced in, with tightening of 90 basis points expected by the middle of next year... However, given the high expectations surrounding the BoJ, the potential for a stronger yen is likely to be limited for the time being, at least until the first interest rate rises actually materialise."
Based on the combined assessments of both institutions, the Japanese Yen's recovery has provided vital breathing room for broader APAC currencies while capping USD/JPY upside. BNY projects that strong current-account fundamentals will keep regional FX well-supported unless a renewed energy shock intervenes, while Commerzbank maintains that for USD/JPY to extend its decline, the BoJ must follow through on high market expectations with tangible rate hikes rather than relying solely on official verbal deterrence.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
Author

FXStreet Insights Team
FXStreet
The FXStreet Insights Team is a group of journalists that handpicks selected market observations published by renowned experts. The content includes notes by commercial as well as additional insights by internal and external analysts.

















