Wake Up Wall Street (SPY) (QQQ): All eyes on CPI as earnings season beckons

Here is what you need to know on Monday, July 11:
Friday's employment report is out of the way and was a largely positive experience despite some haggling from bears. Bulls cleared the first hurdle comfortably despite some reservations from the growing bearish contingent. Seems like grasping at straws, in my view, as jobs are jobs. From that perspective, the economy looks healthy.
Onto this week's CPI report – the next hurdle to be cleared. This one will likely be a tougher ask. We feel it will be another shocker and may open some discussion as to the possibility of the Fed taking out the big bat and swinging for a 100-basis-point hike. Currently, after the jobs report, 75 basis points is a near certainty. The last time out the Fed blinked and panicked into a 75-basis-point hike. However, the risk-reward remains favored to more short squeezes across the board as equity positioning looks underweight and investors are still looking to get short.
Record Shorts, heading into next week's CPI/Econ releases. pic.twitter.com/NWHUdJXvxc
— Macro Charts (@MacroCharts) July 9, 2022
Goldman Trader: "The Top Incoming Question From Clients Is When Do I Re-short... Here Is My Reply" https://t.co/21viVMQ0zq
— zerohedge (@zerohedge) July 11, 2022
However, we do have some worries again emanating from China with more covid cases and lockdowns. That has sent futures markets lower on Monday as European markets remain nervous that the Nordstream pipeline's planned maintenance shutdown may not see it reopened. European energy prices have soared this past week as word has spread of gas flows to Europe dropping sharply in June. This may be just a warning during summer, a less than critical month. Europe is on the hook to Russia, but equally it is a two-way relationship. Russia gets well-compensated for selling gas to the EU.
All this talk though has seen the euro collapse to near parity, and the lure of the round number is surely going to work its magnetism now. The dollar index is at 108 now as the Yen too remains pressured. Sterling also exhibits weakness as the UK political scene goes from bad to worse. Gold is $1,763, while Bitcoin continues to cling to $20,000. Oil once again heads back to $100 as global growth fears continue to see all commodities lose ground. As the old saying goes, the best cure for high commodity prices are high commodity prices.
European markets are lower: Eurostoxx -0.4%, FTSE -0.3% and Dax -1%.
US futures are also lower: S&P -0.7%, Nasdaq -0.8% and Dow -0.6%.
Wall Street top news (SPX) (QQQ)
BlackRock (BLK) says overweight equities, underweight bonds. 60/40 won't work anymore. Expects real economic pain, persistent inflation.
US weighs resumption of arms sales to Saudi Arabia, presumably in return for increased oil flows.
Twitter (TWTR) is down as Elon pulls the plug.
Wynn Resorts (WYNN) is down on Macau closing.
Alibaba (BABA) fined by China.
Tencent (TCEHY) fined for failing to comply with anti-monoply rules.
NIO says it formed independent board to invesigate claims by Grizzly Research that it exaggerated revenue.
Camtek (CAMT) up on strong revenues.
Dutch Bros (BROS) down on Baird note.
Occidental Petroleum (OXY) downgraded by Goldman.
Vail Resorts (CFN) CFO stepping down.
Moderna (MRNA) new booster outperformd versus new variants.
Upgrades and downgrades
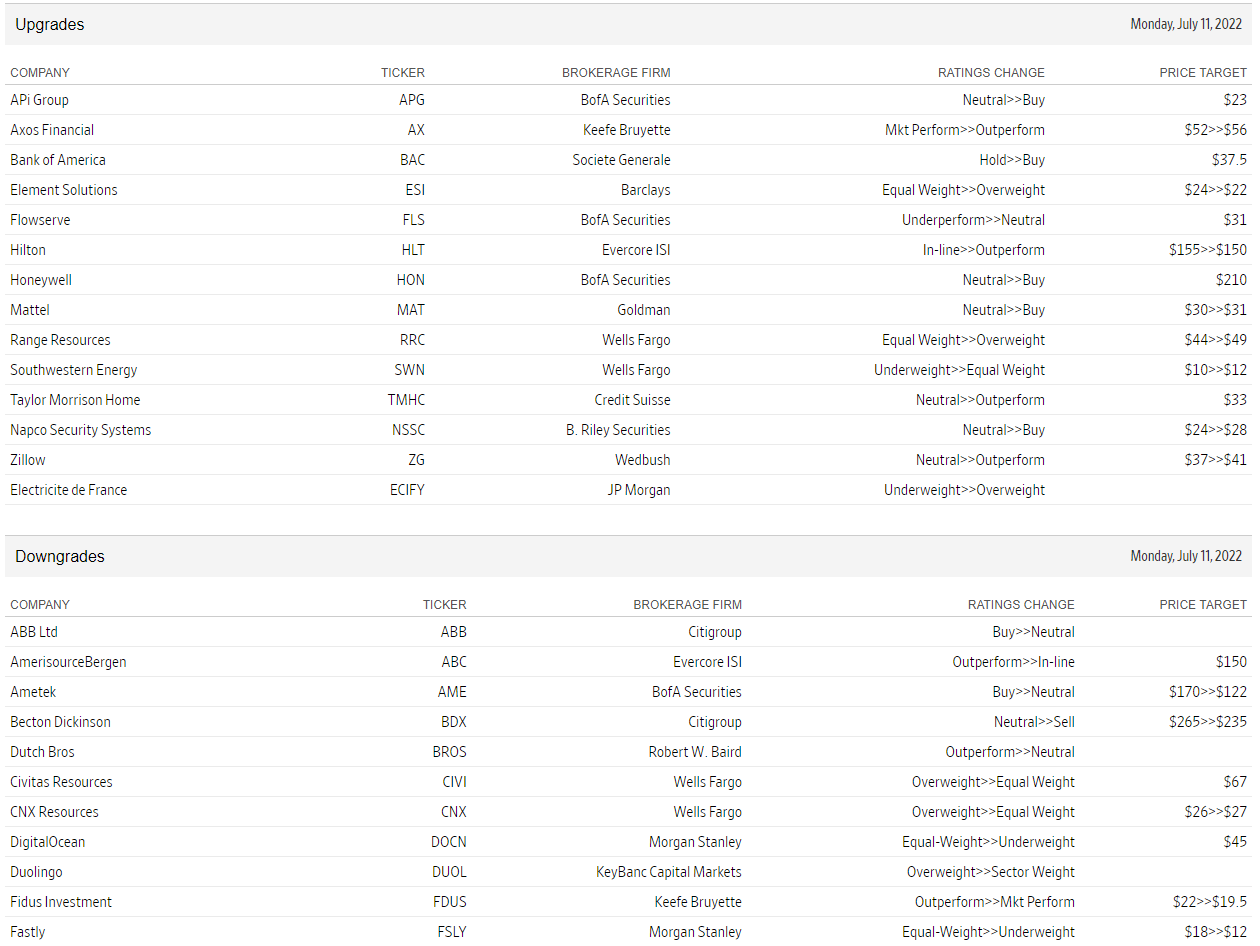
source: WSJ.com
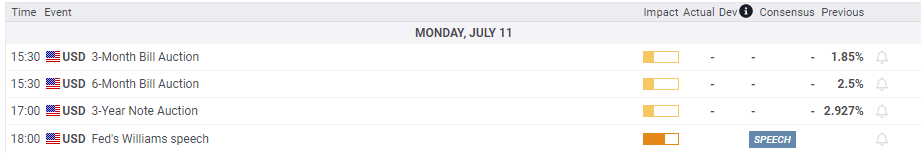
Economic releases
The author is short Tesla and Twitter.
Like this article? Help us with some feedback by answering this survey:
Author

Ivan Brian
FXStreet
Ivan Brian started his career with AIB Bank in corporate finance and then worked for seven years at Baxter. He started as a macro analyst before becoming Head of Research and then CFO.

















