US 10-year yield revisits 2007 heights as curve flirts with inversion
- US 10-year yield hits 5.274%, its highest since June 2007.
- Curve flattens as investors price additional Fed tightening.
- GDP, Core PCE and NFP headline this week’s catalysts.
US Treasury yields climb as energy prices remain high, amid US President Donald Trump's rejection of a peace agreement with Tehran. Also, investors pricing in further tightening by the Federal Reserve to tackle high inflation above the central bank’s 2% goal is another reason for investors demanding a higher premium on US debt.
Energy risks and Fed tightening bets keep pressure on US debt
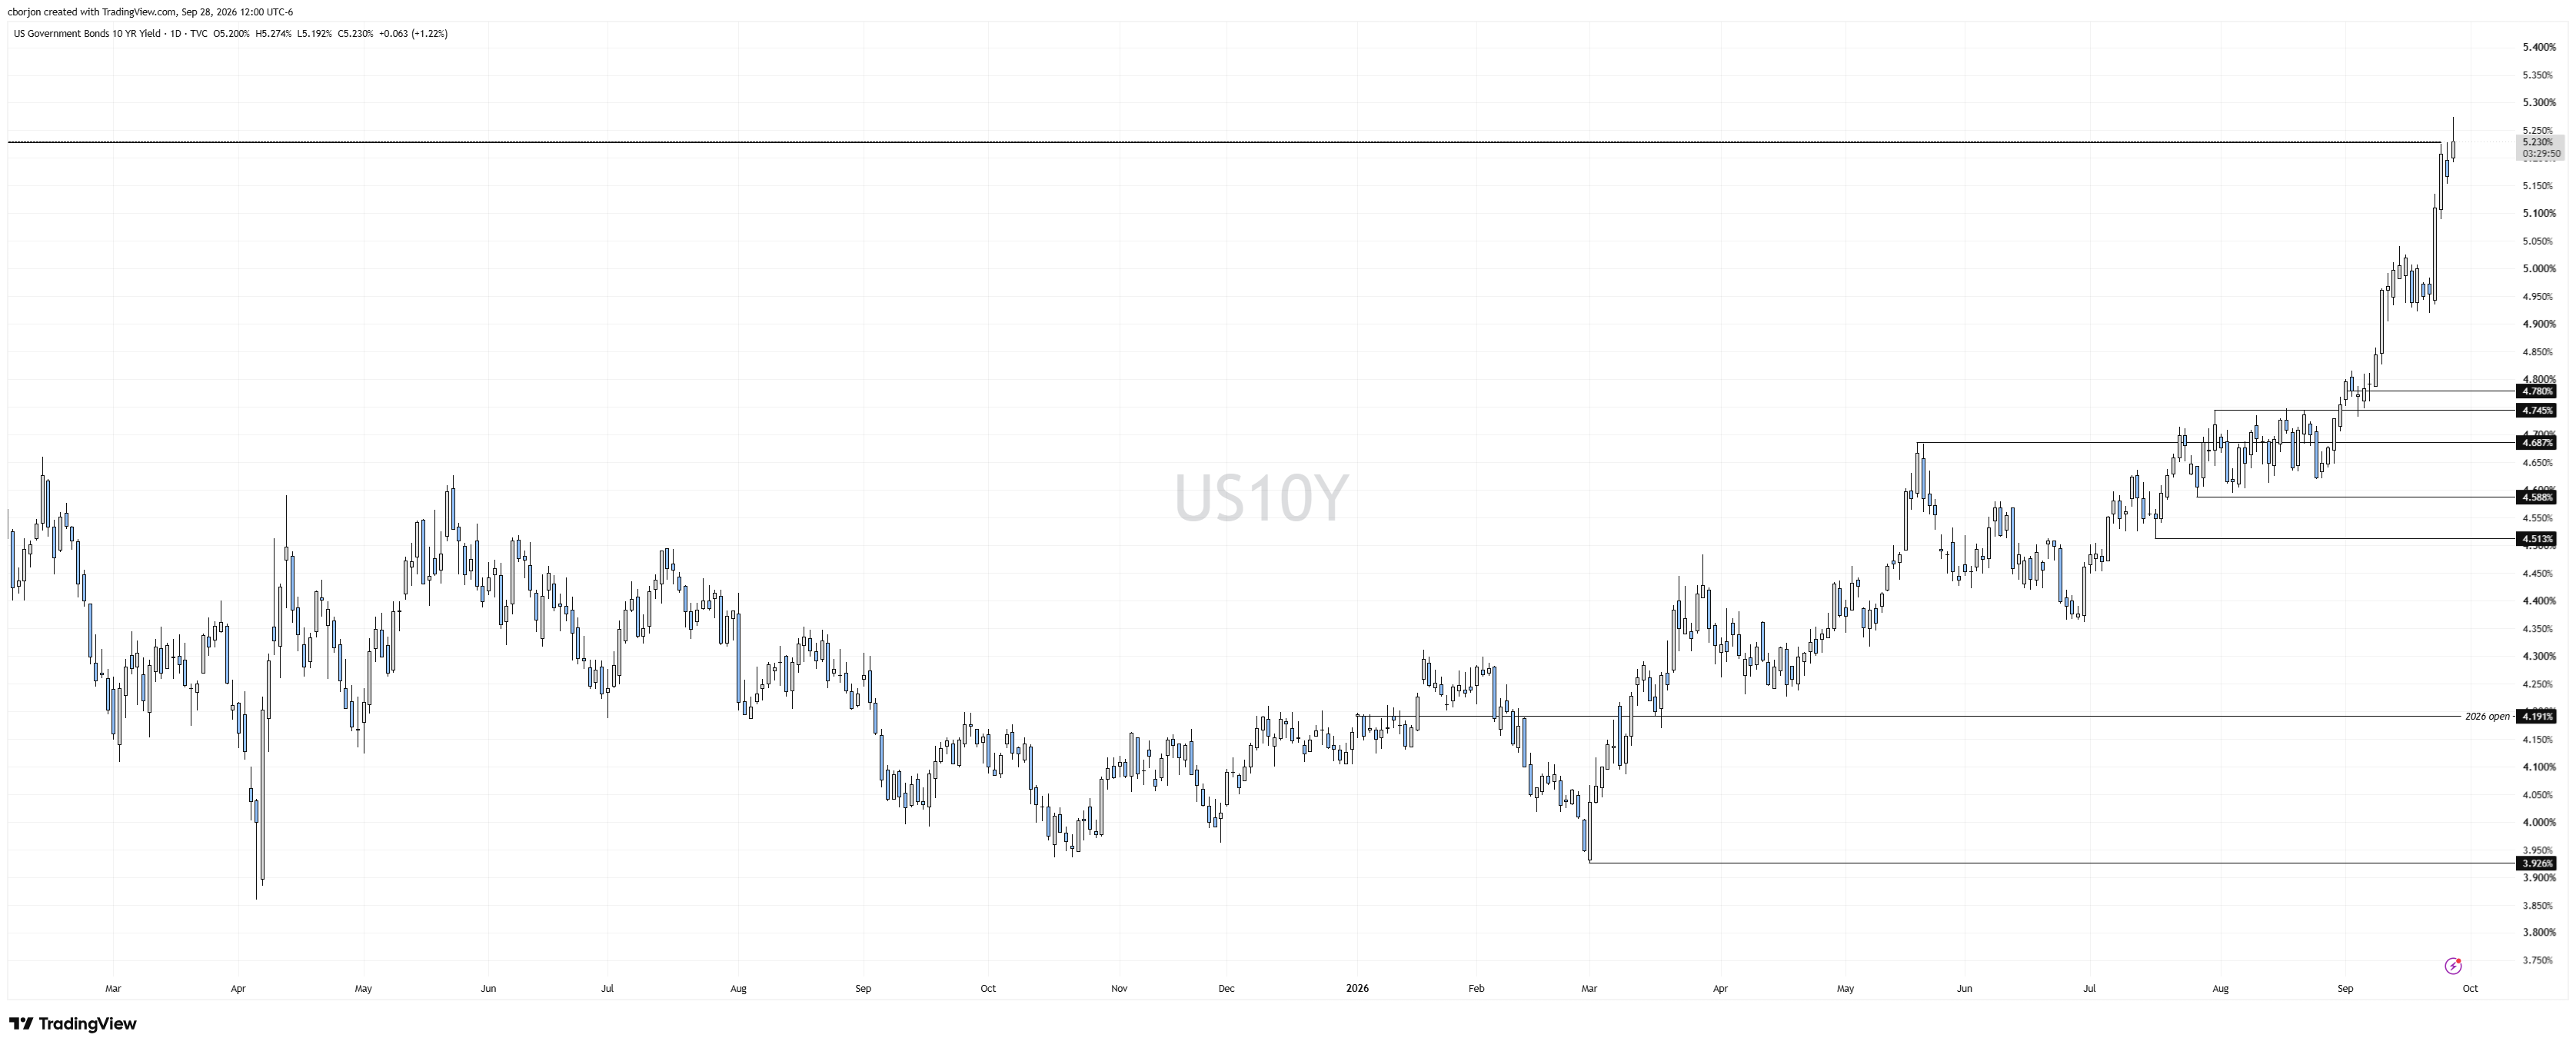
The US 10-year Treasury note yield rose to its highest level since June 2007 at 5.274%, before trimming some of its gains to 5.247%, up over eight basis points.
In the meantime, contradictory US-Iran news headlines keep the financial markets volatile. News that Iran agreed to halt its uranium enrichment program, reported by Al Hadath, was followed by Al Arabiya reporting that the chances of an agreement between the two countries are extremely slim, according to a US source involved in negotiations with Tehran.
Fed speaking is keeping US Treasury yields higher as well. Governor Lisa Cook was hawkish, expecting continued inflationary pressures in the coming months from AI and hostilities in the Middle East.
Consequently, traders still see a 65% chance of a 25-basis-point rate hike by the Federal Reserve at the October meeting. Although it seems like a coin flip, the December meeting is almost certain, with odds of 94%, according to Prime Terminal data.
Meanwhile, the US 30-year bond yield is up almost 7 basis points to 5.559%.
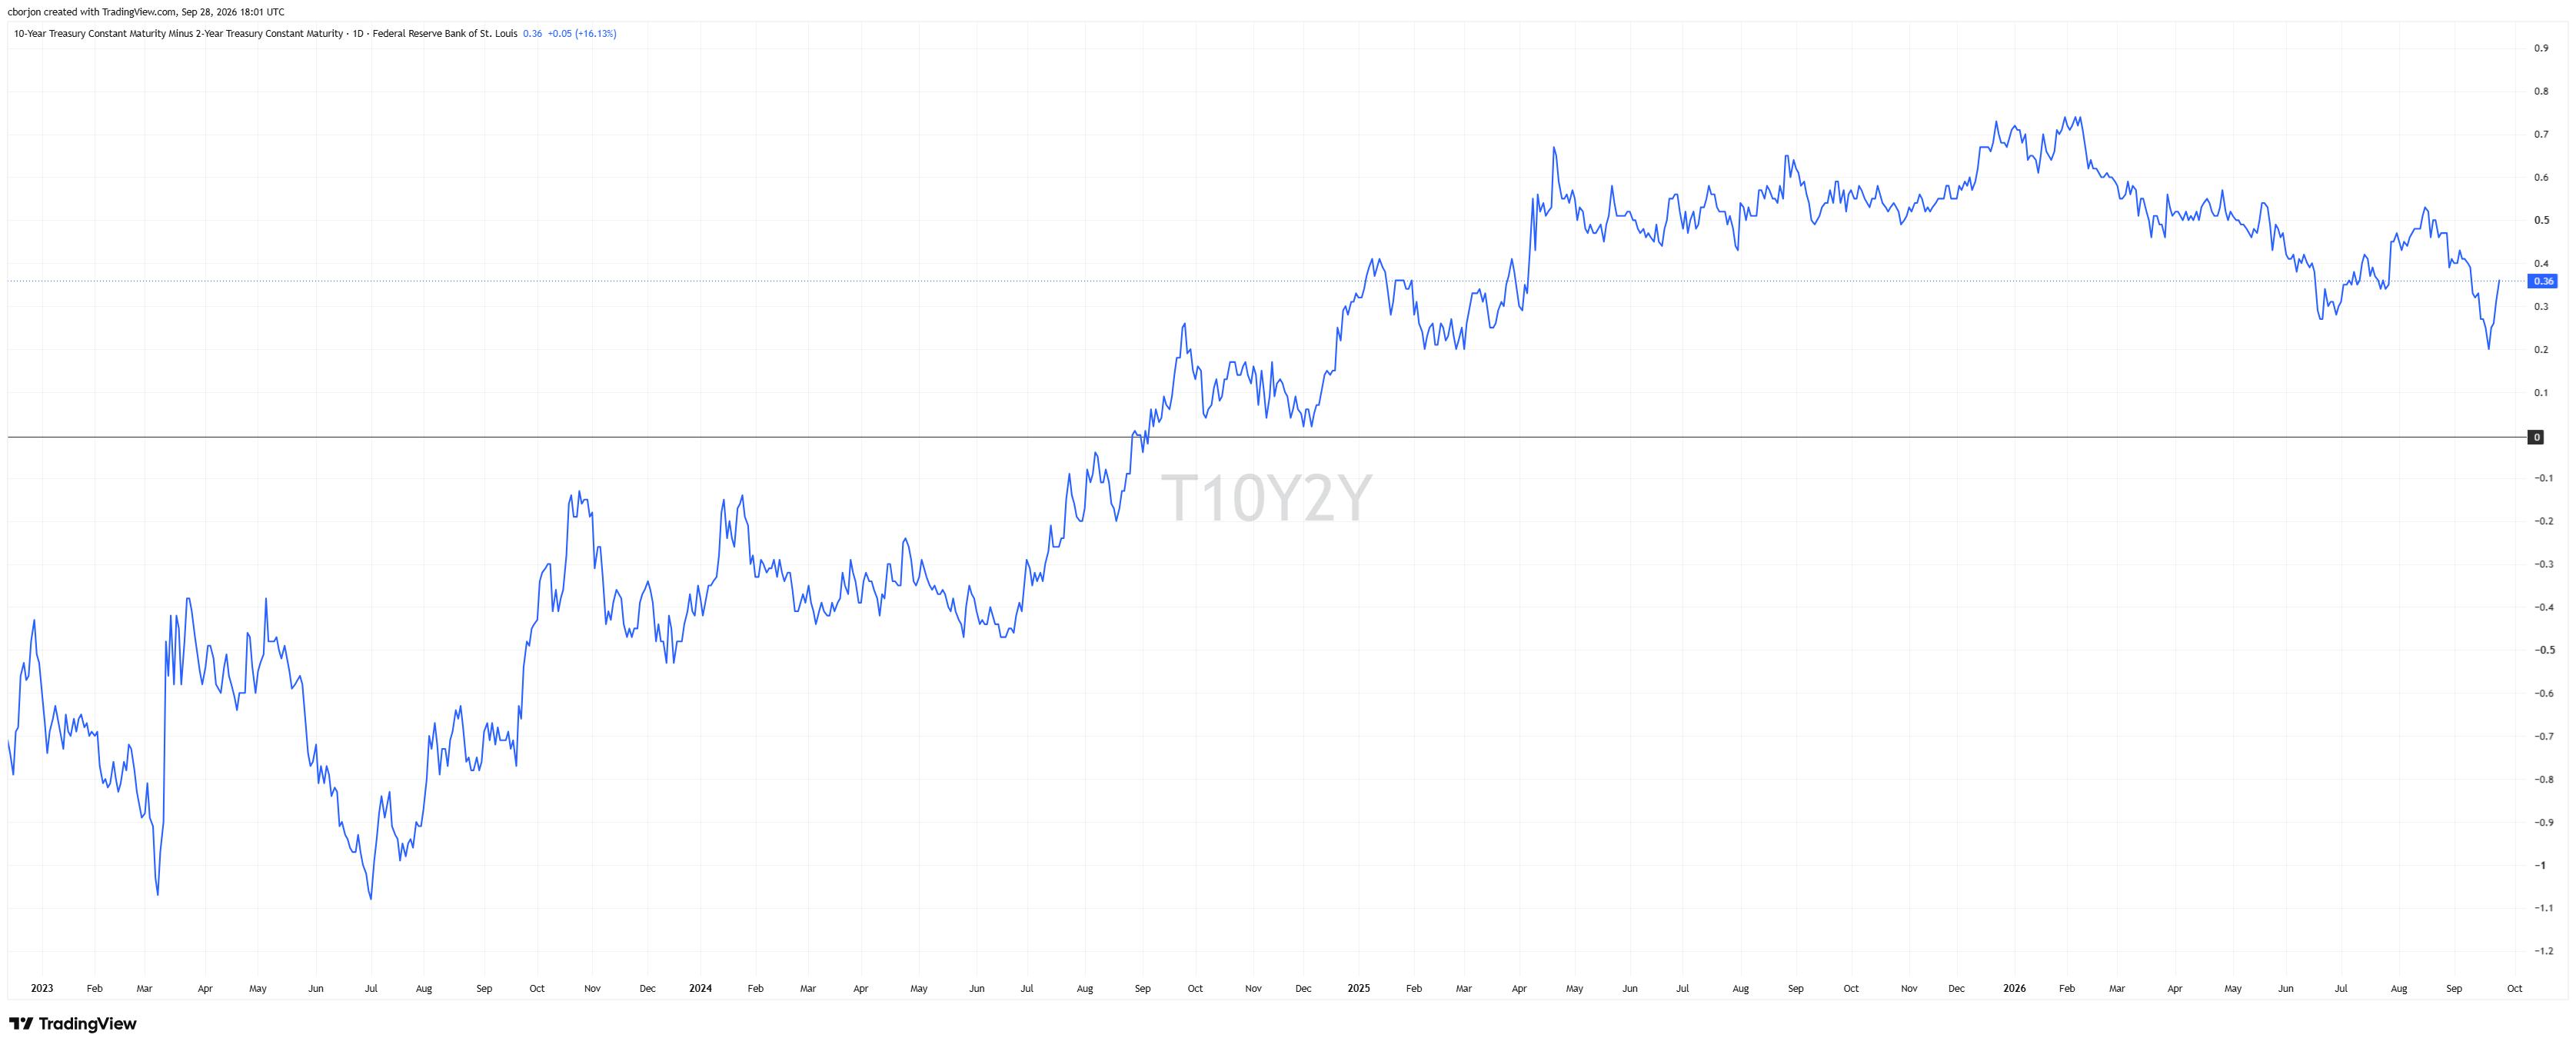
Worth noting that the yield differential between the US 10-year and the US 2-year narrowed to as low as 17 basis points, an indication that a possible yield curve inversion looms, as it flattens on expectations of further tightening.
Ahead, the US economic docket will feature GDP data, the Fed’s preferred inflation gauge, the Core Personal Consumption Expenditures (PCE) Price Index and September’s US Nonfarm Payrolls on Friday.
US 10-year Treasury yield
Interest rates FAQs
Interest rates are charged by financial institutions on loans to borrowers and are paid as interest to savers and depositors. They are influenced by base lending rates, which are set by central banks in response to changes in the economy. Central banks normally have a mandate to ensure price stability, which in most cases means targeting a core inflation rate of around 2%. If inflation falls below target the central bank may cut base lending rates, with a view to stimulating lending and boosting the economy. If inflation rises substantially above 2% it normally results in the central bank raising base lending rates in an attempt to lower inflation.
Higher interest rates generally help strengthen a country’s currency as they make it a more attractive place for global investors to park their money.
Higher interest rates overall weigh on the price of Gold because they increase the opportunity cost of holding Gold instead of investing in an interest-bearing asset or placing cash in the bank. If interest rates are high that usually pushes up the price of the US Dollar (USD), and since Gold is priced in Dollars, this has the effect of lowering the price of Gold.
The Fed funds rate is the overnight rate at which US banks lend to each other. It is the oft-quoted headline rate set by the Federal Reserve at its FOMC meetings. It is set as a range, for example 4.75%-5.00%, though the upper limit (in that case 5.00%) is the quoted figure. Market expectations for future Fed funds rate are tracked by the CME FedWatch tool, which shapes how many financial markets behave in anticipation of future Federal Reserve monetary policy decisions.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.
















