The New Zealand Dollar dips to a new low and bounces as Crude Oil gets cheaper
- NZD/USD dips under 0.5700 to an 11-week low and bounces as Crude Oil eases.
- RBNZ cash rate at 2.75%, 1.125 points under the Fed's midpoint.
- China's Xi in Washington from September 23 to 25, White House talks Thursday.
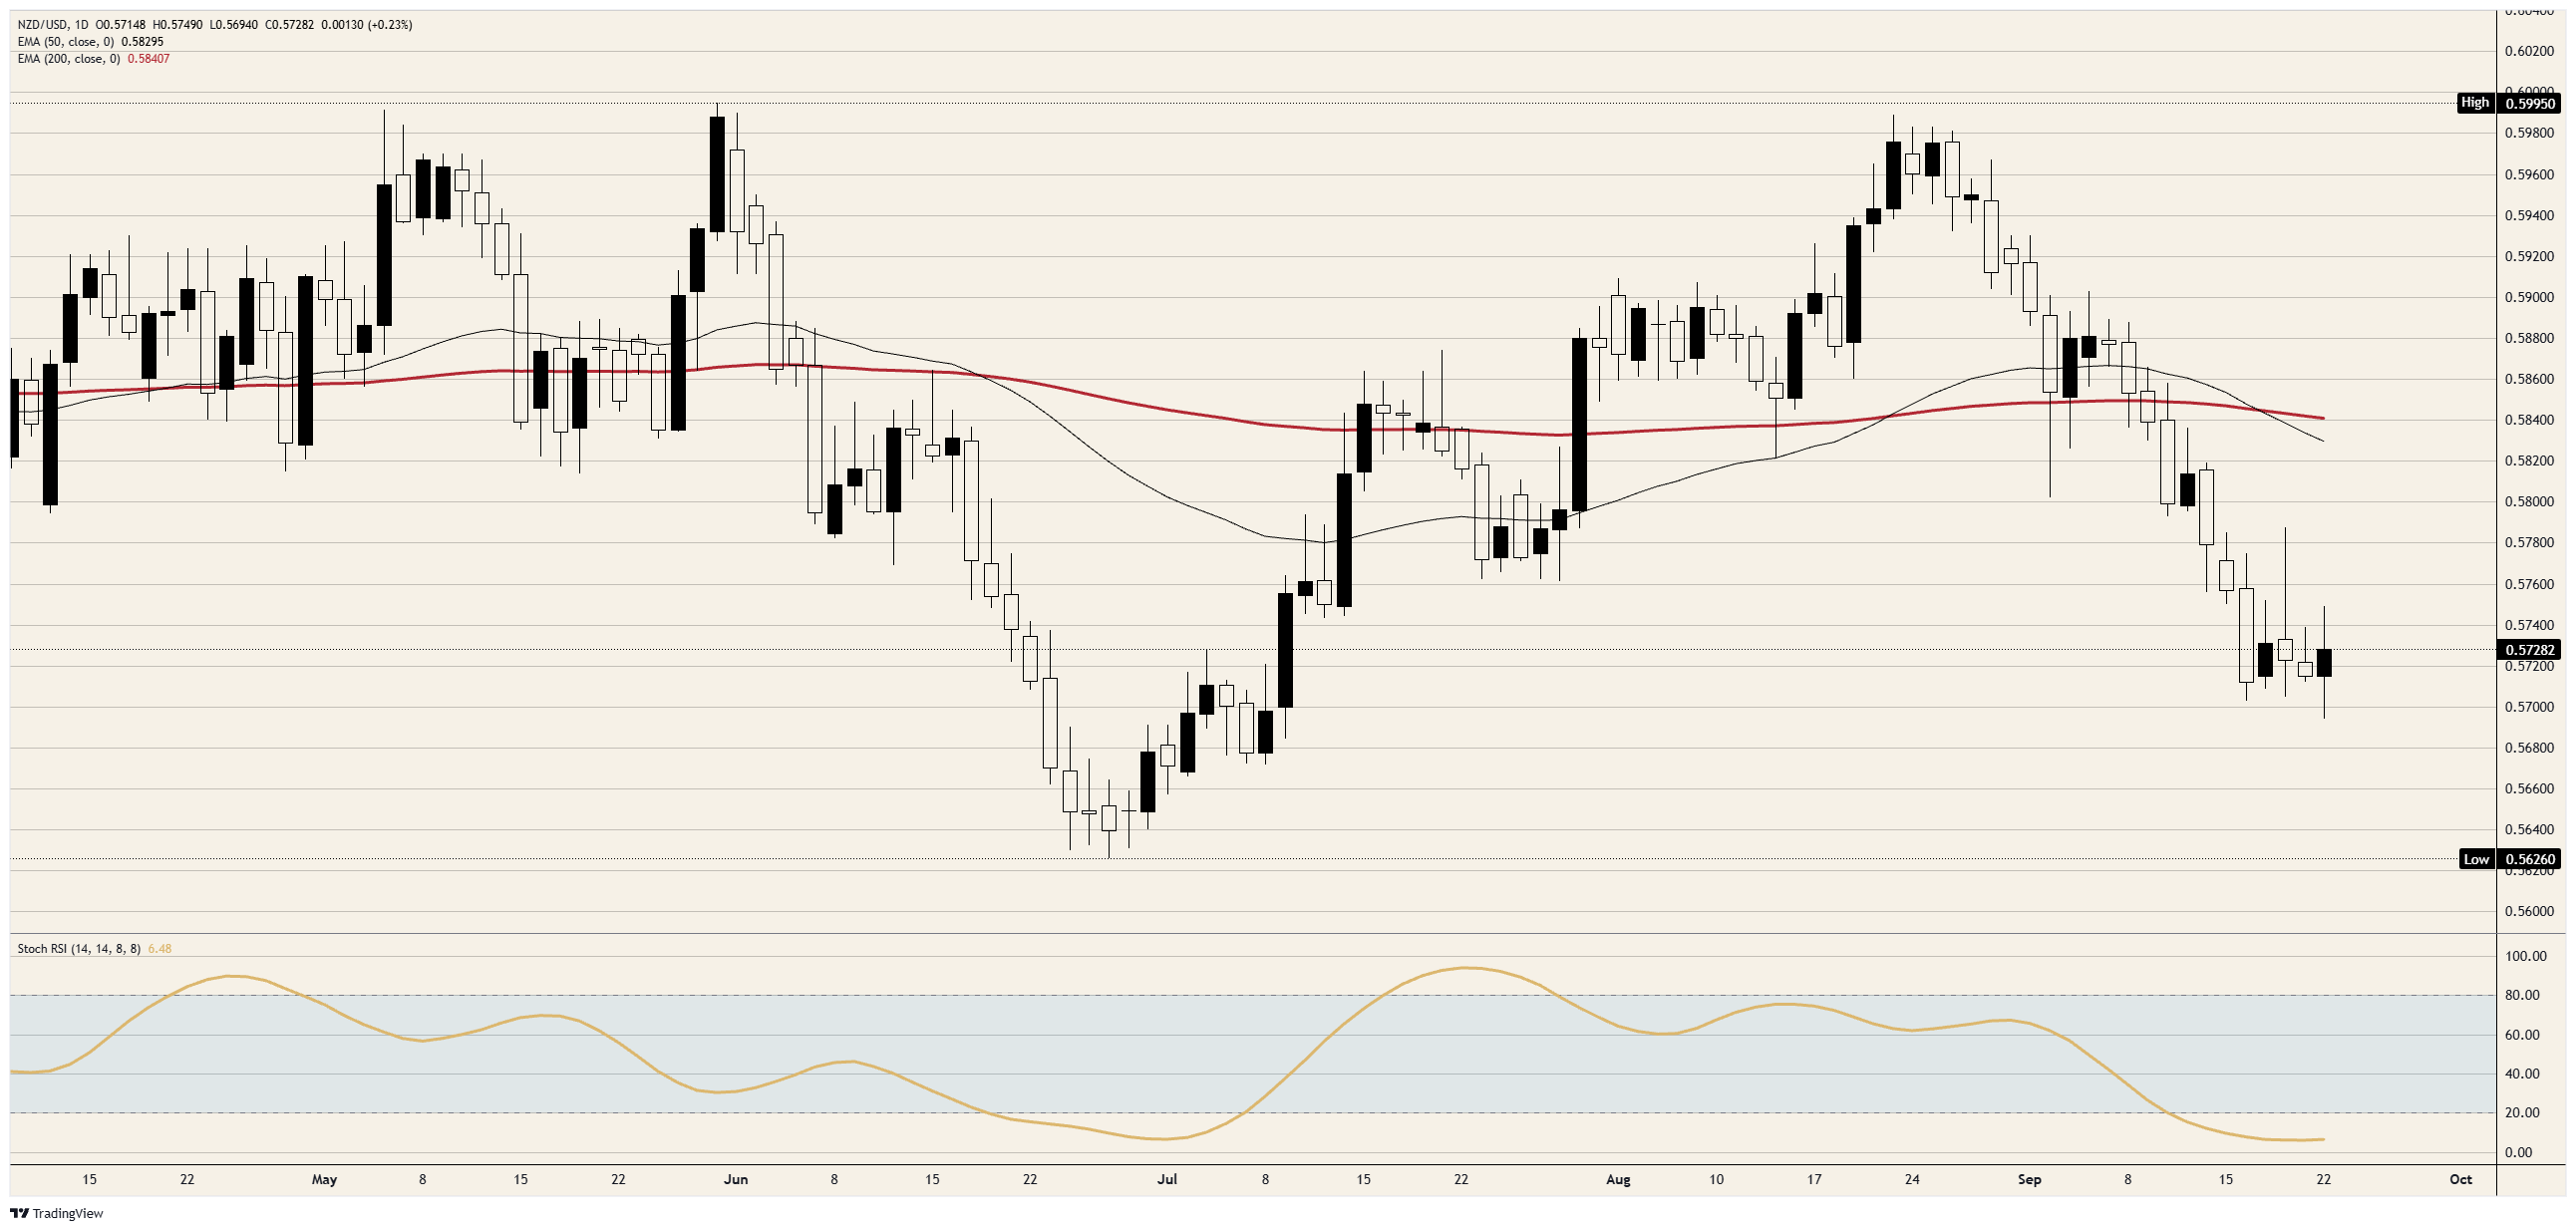
Four weeks of selling have taken NZD/USD from just under 0.6000 to its lowest since early July. On Tuesday the pair dipped under 0.5700, then climbed back into the 0.5700 to 0.5800 range it has traded in since September 16, and it's trading in the lower half of that range. The bounce came as Crude Oil got cheaper, and every rally since September 18 has stopped below that day's high near 0.5800.
New Zealand grew faster than forecast and the Kiwi fell anyway
New Zealand's economy grew 0.2% in the second quarter, Statistics New Zealand reported on September 17, beating a 0.1% forecast and the no-growth forecast of the Reserve Bank of New Zealand (RBNZ). Annual growth came in at 2.6% against 2.2% expected, and the RBNZ expects inflation to stay above 3% for the rest of 2026, which is the reason it gives for its increases. A beat like that should keep another rate increase in view, and the pair barely moved, because the Fed had raised its own rate the day before.
New Zealand's Official Cash Rate (OCR), the RBNZ's name for its main interest rate, is 2.75% and has been since September 2. RBNZ Governor Breman said then that another increase is likely but the timing is highly uncertain, and that the rate is still accommodative, which means low enough to help the economy rather than slow it. The bank's own rate track points to a pause on October 28 and a move in December. The Fed's midpoint is 3.875%, so a Kiwi deposit earns 1.125 points less than a Dollar one, and a quarter-point in December would still leave it short by nearly a point.
A cheaper barrel helps a country that buys all of its fuel abroad
Brent traded under $100 when the pair turned up on Tuesday, and Crude Oil slipped again once Iran put a conditional offer to reopen Hormuz on the table. New Zealand imports its petrol and diesel, and fuel pushed its inflation to 4.1% in the second quarter. A lower price shrinks the country's import bill, which means fewer New Zealand Dollars sold to buy the Dollars that pay for it.
Chinese President Xi arrives in Washington on Wednesday and meets President Trump at the White House on Thursday, the first state visit by a Chinese leader since 2015. China is New Zealand's biggest export market, so a deal that eases US tariffs on Chinese goods supports demand for New Zealand's dairy and meat, and traders buy the Kiwi as a stand-in for that trade. A summit has a fixed date and an unknown result, and Tuesday's bounce only makes sense if it goes well.
Nothing from New Zealand before Friday, so the pair trades US data
There's no major New Zealand data before Friday, which leaves the pair to the US calendar. Friday's durable goods report at 12:30 GMT is forecast to show orders down 0.4% after a 1.1% rise. The part that tracks business investment, orders for non-defence capital goods excluding aircraft, is forecast up 0.5% after no change, so the headline and the part that matters for rates are forecast to move in opposite directions.
Firms spending more is the kind of US strength that keeps a second Fed increase on the table for October 28, the same day the RBNZ decides. The US manufacturing survey due Wednesday is forecast at 53.5 from 53.9. A Fed increase and an RBNZ pause on the same day would widen the gap to 1.375 points.
Australia's August jobs report on Thursday at 01:30 GMT, forecast to show 20K jobs added, matters as well, because the Australian and New Zealand Dollars tend to move together and the Reserve Bank of Australia meets on September 29 with another increase under discussion. A strong Australian number would lift both currencies and give the Kiwi a push toward the top of its range without anything changing in New Zealand.
Levels and bias
Resistance: 0.5750, where Tuesday's bounce stopped, then 0.5800, the top of the range the pair has been in since September 16. Beyond the range, the 50-day Exponential Moving Average (EMA) near 0.5850 hasn't been tested since the pair went under it in early September.
Support: 0.5700, the bottom of the range, which Tuesday's low went under by a few pips before the pair came back. Below it, the July low just above 0.5600.
Bias: Bearish below 0.5750. The first objective is 0.5700 and the second is the July low just above 0.5600. The daily Stochastic Relative Strength Index (Stoch RSI), a momentum gauge, is down at 6 and has been flat at the bottom since September 16, so the selling is stretched and the range could hold for a few more sessions without changing the call. The bearish case fails on a daily close above 0.5800.
NZD/USD daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















