The Euro drops to its lowest since July as the Dollar keeps climbing
- EUR/USD dips under 1.1450 to its lowest since late July as the Dollar climbs.
- Eurozone consumer confidence at -16.5 in September, under the -16 forecast.
- Eurozone flash composite PMI due Wednesday at 08:00 GMT, forecast 51.5 from 52.

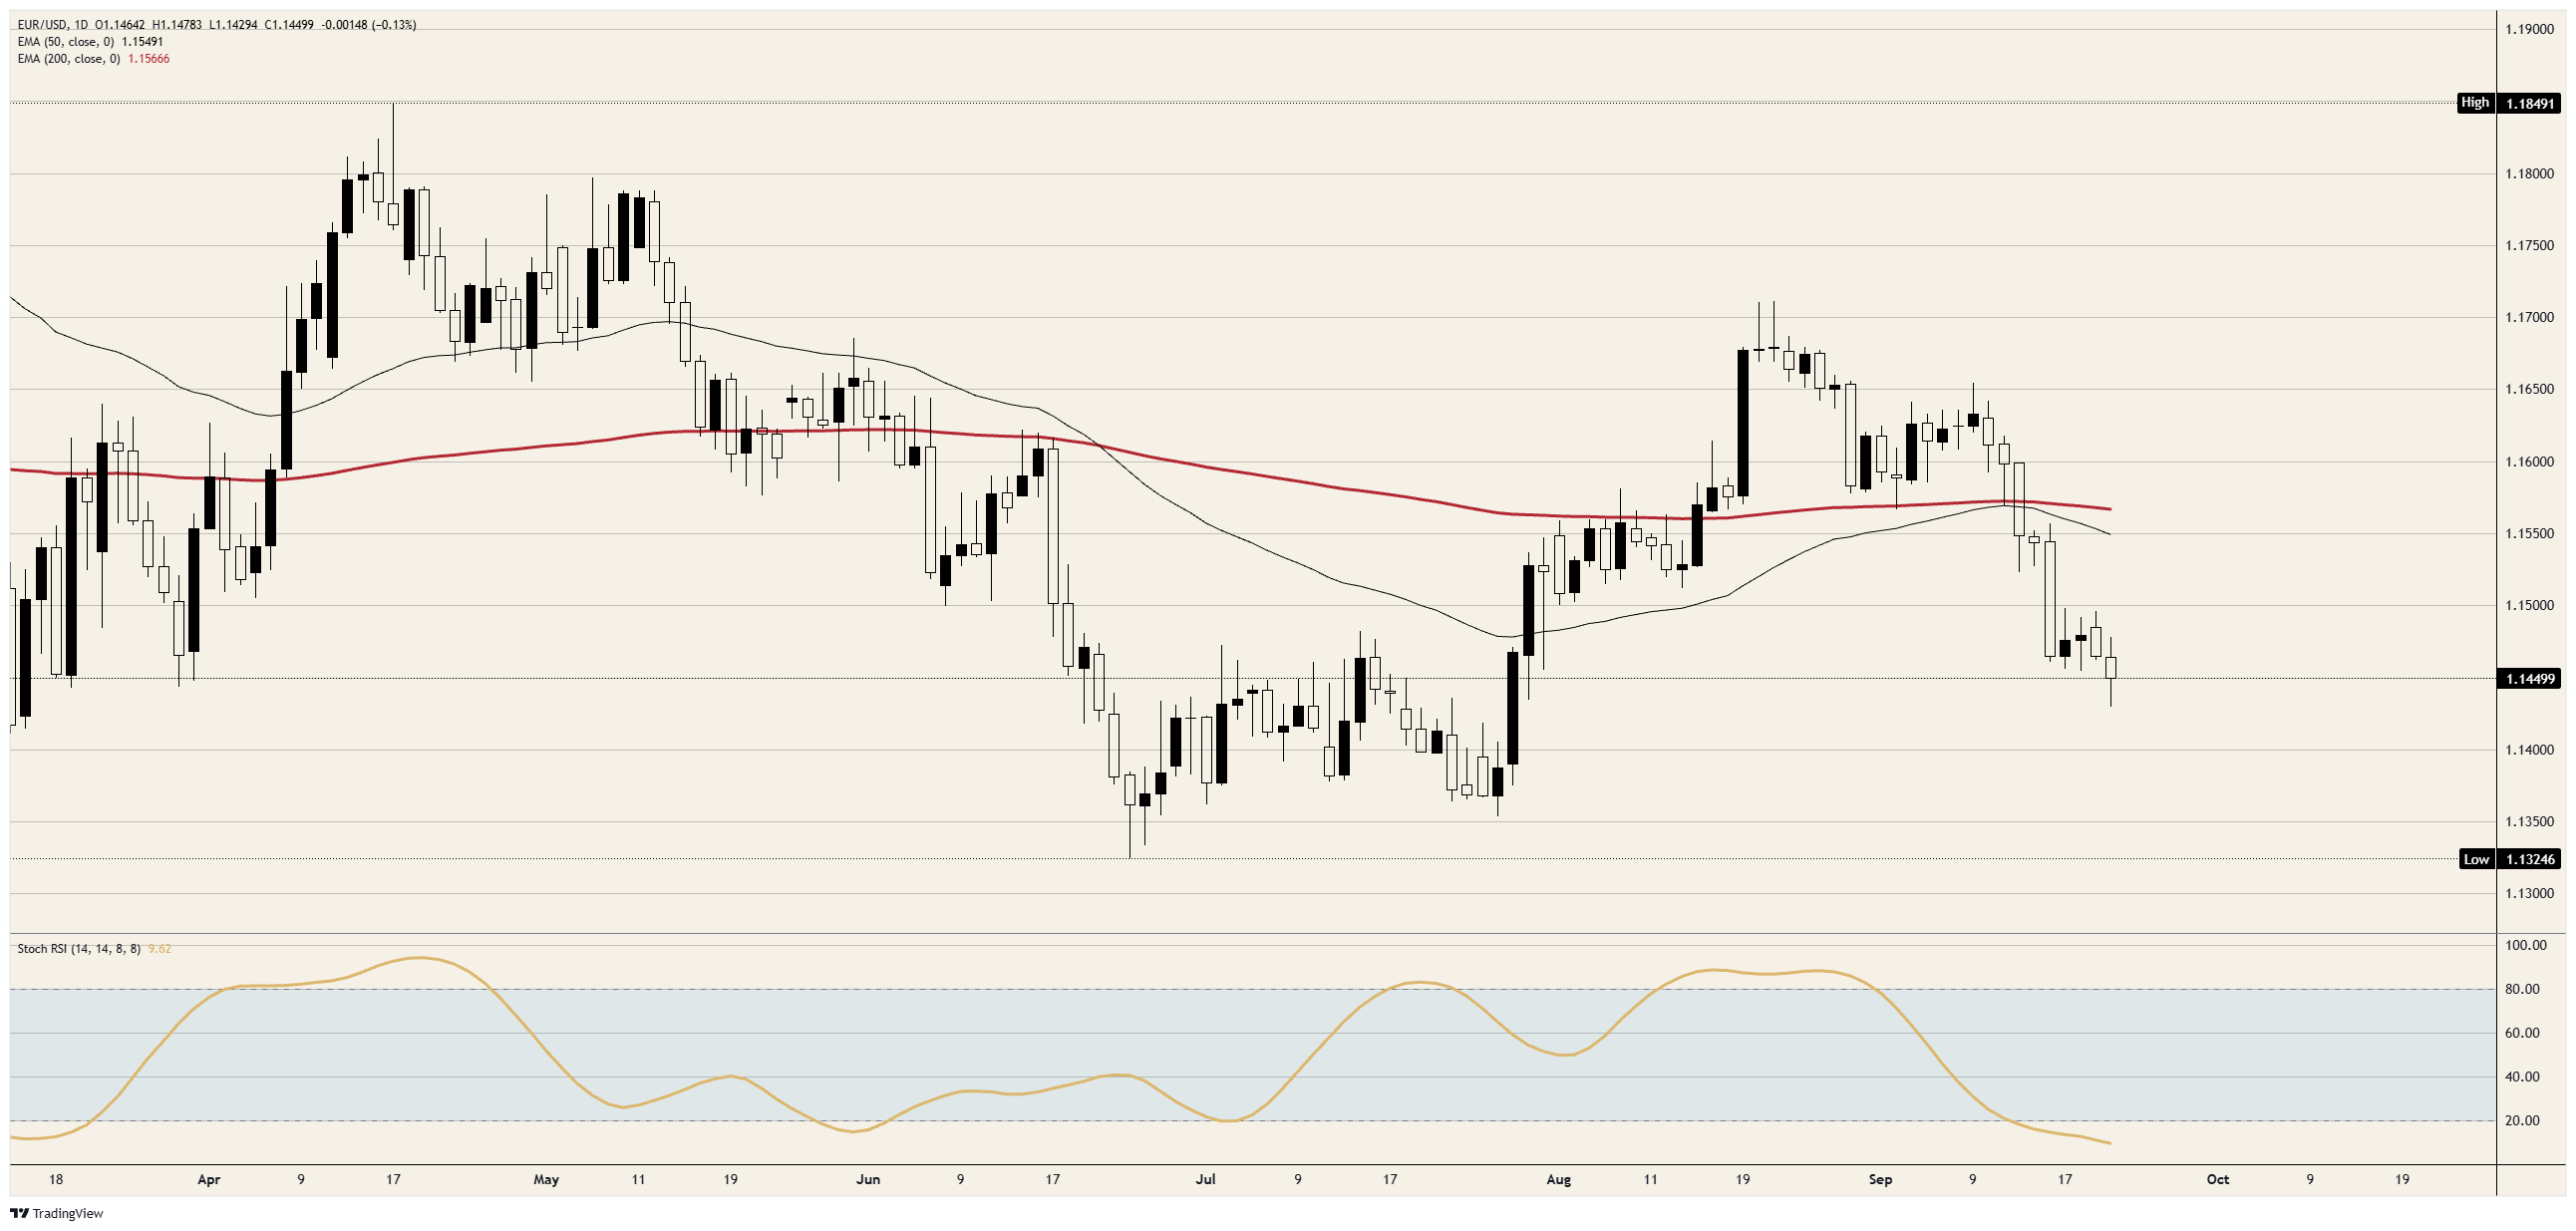
About 80% of the Euro's August rally is gone. EUR/USD climbed from near 1.1350 at the end of July to just above 1.1700 in the second half of August, and on Tuesday it dipped under 1.1450 to its lowest since late July before recovering to trade near that level. The Euro's own news was a weaker consumer survey, but most of the move came from the Dollar, which gained as US rate expectations kept rising.
The Euro's best argument is one the ECB is arguing against
The European Central Bank (ECB) raised its deposit rate, the rate it pays banks on their overnight money, to 2.50% on September 10, its second increase since the war pushed energy prices up. Futures traders now expect three or four more over the next year. That's the case for owning Euros: every ECB increase closes part of the 1.375-point gap to the Fed's 3.875% midpoint, and a smaller gap is less reason to hold Dollars instead. Bundesbank President Nagel, who spoke twice on Tuesday, said on September 11 that rates may need to go high enough to slow the economy, and that view is where the three or four increases in futures come from.
ECB President Lagarde told eurozone finance ministers in Dublin on September 18 that the ECB's rates don't simply follow energy prices higher and that its response is measured. ECB Vice-President Vujčić made the same point hours earlier. The market's three or four increases are the Euro's main support, and the two most senior people at the institution that would deliver them have both said the market expects too much.
European households are gloomier and that's bad news for the rate case
The European Commission's flash consumer confidence reading for September came out on Tuesday at -16.5, against a forecast of -16 and down from -15.5 in August. That's households saying energy bills leave them less to spend. The eurozone buys nearly every barrel and most of its gas from abroad, so Iran's conditional offer on Tuesday to let tankers back through Hormuz would ease those bills, and with them some of the case for more ECB increases. A consumer who spends less gives the ECB less reason to raise rates again, which is the wrong direction for a currency that needs those increases to close its gap with the Dollar.
Wednesday's flash surveys are the next test. The Hamburg Commercial Bank (HCOB) composite Purchasing Managers Index (PMI), a poll of company buyers where 50 separates growth from contraction, is forecast at 51.5 from 52 at 08:00 GMT, with services at 51.7 and manufacturing unchanged at 52.7. A reading of 51.5 is still growth, only slower than in August. Two soft readings in two days would give the ECB a reason to deliver fewer increases than the market expects, which is the outcome ECB President Lagarde has already described.
Five ECB speeches and a US survey before Friday
ECB Vice-President Vujčić speaks again on Wednesday at 07:00 GMT, Executive Board member Cipollone at 16:00 GMT and ECB Chief Economist Lane at 16:30 GMT. Executive Board member Schnabel follows on Thursday at 07:15 GMT and Chief Economist Lane speaks again at 09:00 GMT. Anything closer to ECB President Lagarde's measured line than to the market's three or four increases takes support away from the Euro.
Germany's Ifo business survey for September is due on Thursday, and Germany is the largest economy in the eurozone, so a weak reading there does more damage to the ECB's case for more increases than a weak one anywhere else.
On the Dollar side, S&P Global's US flash surveys are due on Wednesday at 13:45 GMT, with services forecast at 56 from 56.5, and Fed Governor Barr speaks at 14:05 GMT. US services at 56 against eurozone services at 51.7 is the growth gap between the two economies in a single comparison, and it's why the Fed can keep raising rates into an economy that can take them.
Levels and bias
Resistance: 1.1500, which has stopped every rally since the Fed's September 16 decision. Higher up, the 50-day Exponential Moving Average (EMA) near 1.1550 is the level the pair went under on September 14, the start of the fall to its current low.
Support: Tuesday's low just above 1.1400, then the late-July base near 1.1350, where the August rally started.
Bias: Bearish below 1.1500. The first objective is 1.1400 and the second is 1.1350. The daily Stochastic Relative Strength Index (Stoch RSI), a momentum gauge, is under 10, its lowest since mid-March, so the fall is stretched and a bounce as far as 1.1500 would leave the direction unchanged. A daily close above 1.1550 means the bearish case is wrong.
EUR/USD daily chart
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















