The Dollar Index takes its orders from the Treasury
- DXY trades near 99.00, roughly 2.8% under the late-June peak just shy of 102.00.
- Spending down a 950 billion Dollar Treasury account injects bank reserves.
- The bounce off the 98.50 area runs less than half a percent.
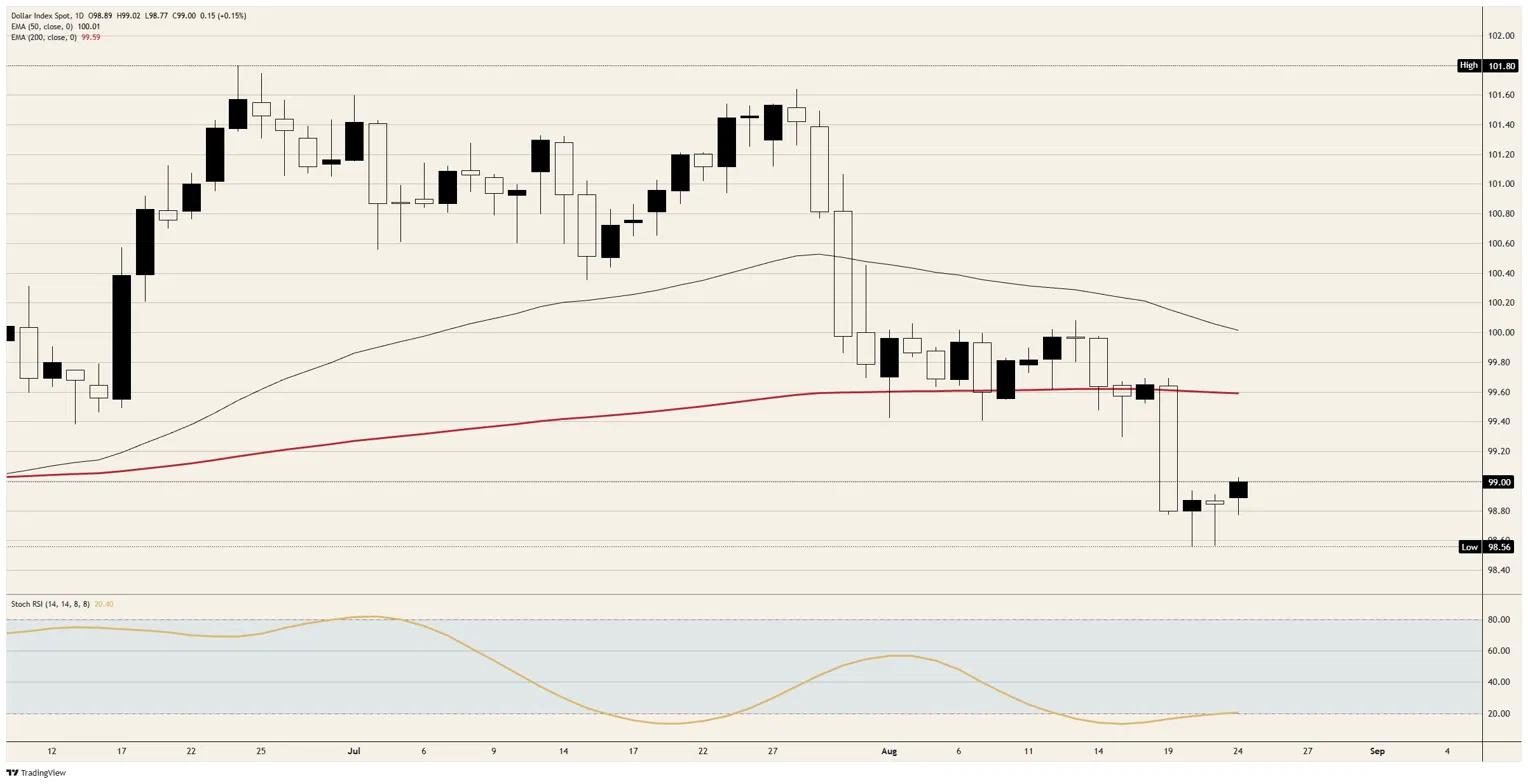
A currency whose central bank has held five times, prices no cut this year and still carries an increase by December should not be sitting at the bottom of its three-month range. The Dollar Index trades near 99.00, up 0.15% and roughly 2.8% beneath its late-June peak, beneath a 200-day Exponential Moving Average (EMA) near 99.50 and a 50-day parked on the 100.00 handle. The rate story stopped paying somewhere in the middle of this month.
Where the Dollars are coming from now
The break that matters is five sessions old and it did not come from the Federal Reserve. The index lost a 200-day EMA it had held through the summer across August 19 and 20, the sessions that carried the Treasury's move to double the ceiling on its long-end bond buybacks, and it has not traded back above the line since. That was read at the time as a bond story.
Today put a size on the programme. The Treasury General Account (TGA), the government's operating balance at the Federal Reserve, is considered available to fund the purchases, and it stands near 950 billion Dollars against the 550 to 600 billion Dollar working level of the previous administration. Every Dollar that leaves that account arrives in the banking system as reserves, and with the overnight reverse repo facility long since drained there is nothing left to absorb the flow.
Easing without a vote
Spend a fraction of that balance and the effect on Dollar liquidity compares with a rate cut, delivered without a meeting, a statement or a dissent. The policy rate would sit exactly where it is at 3.50% to 3.75%, while the quantity of Dollars in the system rises. That is a distinction the currency has begun to price and the front end has not.
The funding side compounds it. Long-dated coupons are bought back and refunded at the front of the curve, so the average maturity of the borrowing shortens and a rising share of the debt reprices with the policy rate. Short bills are the closest thing the Treasury issues to base money, so an issuer converting duration into bills is running an easing operation from the fiscal side of the street.
The tell in today's tape
This session makes the point cleanly. The ten-year yield fell more than three basis points to 4.70% and the thirty-year shed more than four to near 5.23%, and the Dollar Index gained anyway. Falling US yields alongside a firmer Dollar is not what a rate-differential model produces. It is what happens when the yield falls because the issuer is buying, which tells you about the price of the bond rather than the appetite for the currency.
The demand side gets a threat too
At 18:00 GMT the Treasury Secretary unveils what the administration has trailed as the largest financial offensive ever mounted against Iran, with the warning aimed squarely at the countries still lifting Iranian barrels. The largest of those is China. Tehran's national security chief has already said that any state joining the measures commits an act of war.
Secondary sanctions work by making the Dollar payment system dangerous to use, which is a serviceable tactic and a poor advertisement. Foreign holdings of Treasuries fell in June with the United Kingdom, China and Japan each trimming, and the message to those same accounts this week is that they should hold more of the paper and expect to be policed over their energy purchases.
This week's tests
Wednesday at 12:30 GMT carries the July Personal Consumption Expenditures (PCE) price index, the core measure seen at 0.2% MoM from 0.1% with the annual rate holding at 3.3%, alongside preliminary second-quarter Gross Domestic Product (GDP) figures the consensus expects to be revised by nothing at all. Personal spending is seen at 0.2% from 0.3%.
Friday carries the currency's real risk. The Fed Chair speaks at 14:00 GMT from the annual symposium, and the Bureau of Labor Statistics (BLS) publishes the preliminary benchmark revision to the payroll survey in the same minute. A hawkish Chair reading out a labour-market history that has just been cut is the awkward combination, and the 2024 preliminary revision took 818K jobs off the count.
Levels
Resistance: 99.00 is the line this bounce has stalled against, with the 200-day EMA near 99.50 above it and the 50-day sitting on the 100.00 handle. A daily close through the EMA band is the only thing that reopens 100.50.
Support: The session low sits near 98.75 and the 98.50 area carried the low of the move, beneath which this window offers no reference at all. The daily Stochastic Relative Strength Index (Stoch RSI) near 20 is oversold and turning, which explains the bounce and not its stopping point.
Bias: Bearish while the 200-day EMA near 99.50 caps. Objectives the 98.50 area, then a look beneath it. Invalidation on a daily close above 99.50.
DXY daily chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















