The Australian Dollar flatlines while everyone else has a war to trade
- AUD/USD trades dead flat between 0.6900 and 0.6950, printing an indecision candle as the July rebound stalls.
- Hawkish Federal Reserve minutes and a fresh Middle East escalation pull the Aussie in opposite directions and cancel out.
- Thursday's Chinese inflation data at 01:30 GMT decides which way the coil unwinds.

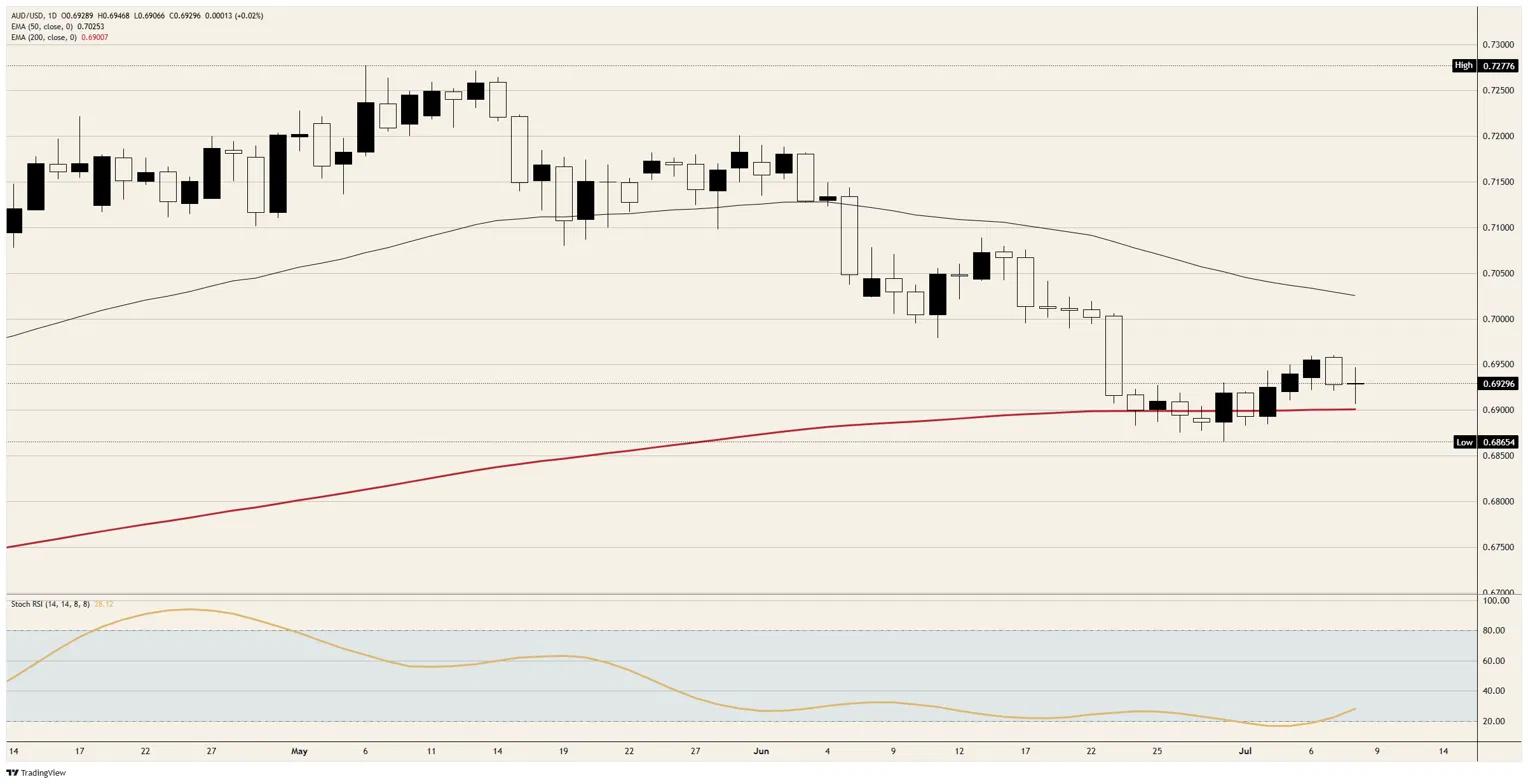
AUD/USD trades pinned between 0.6900 and 0.6950 on Wednesday, essentially unchanged and printing the kind of indecision candle that tells traders the week's rebound has run out of sponsorship. The Aussie has spent five sessions climbing away from the 200-day Exponential Moving Average (EMA) at 0.6900, and the reward is a market that no longer knows what to do with it: No follow-through, no rejection, just a doji parked in the middle of last week's range. For a currency that spent June shedding almost three big figures, standing still this close to the 200-day EMA reads less like stability and more like suspense.
Two hawkish central banks walk into a stand-off
Wednesday's Federal Open Market Committee (FOMC) minutes, released at 18:00 GMT, showed a committee split nearly down the middle on the next move, with the June dot grid printing nine hikes against eight holds and one lonely cut. That quiet split keeps the US Dollar bid on every dip and puts a lid on risk currencies generally, the Aussie included.
The Reserve Bank of Australia (RBA) is running its own hawkish experiment from the other side, holding the cash rate at 4.35% in June after three hikes this year, which is precisely why the pair refuses to break down. Monday's TD-MI Inflation Gauge cooled to 3.9% YoY from 4.4%, lending the hold some vindication without retiring the tightening debate. Two central banks leaning the same direction leave AUD/USD without a rate differential to trade, and a currency without a story consolidates.
The tightening debate is dormant rather than dead: The Governor has framed any inflation print with a three in front of it as unacceptable, and rate markets that flirted with a cash rate near 4.70% by year-end during the worst of the energy shock have only partially walked that back. A hawkish central bank that refuses to act is still a floor under its currency, just not a bid.
A war that helps and hurts in the same breath
Fresh US strikes on Iran and a Crude Oil surge of more than 6% would normally sink a risk proxy like the Aussie, but Australia exports the very energy the war keeps repricing, so the terms-of-trade channel offsets a meaningful slice of the risk-off channel. The chart's verdict is paralysis rather than direction: The pair neither joins the Dollar bid nor collects a commodity premium, and Wednesday's candle is the flattest of the month.
The catch is that the commodity premium runs through Beijing before it reaches Sydney. Iron Ore, not energy, remains the export that sets the Aussie's pulse, and Chinese construction demand has spent the year absorbing an energy shock of its own, which blunts the terms-of-trade windfall. That leaves the currency long a war dividend it cannot fully collect and short a risk appetite it cannot fully escape.
Momentum agrees with the stalemate, with the Stochastic Relative Strength Index flat in the high 20s, going nowhere from nowhere. The slide from the May peak just shy of 0.7300 remains the chart's dominant feature, and a sideways coil forming beneath a falling 50-day EMA above 0.7000 is more often distribution wearing a disguise than a base in construction.
Beijing gets the deciding vote
Thursday's Chinese Consumer Price Index (CPI) lands at 01:30 GMT, expected at 1.1% YoY, easing from 1.2%, with the monthly print seen at -0.2%; the Producer Price Index (PPI) is forecast to accelerate to 4.1% from 3.9% as war-driven input costs pass through factory gates. A consumer deflating while factory costs inflate describes a margin squeeze, not a recovery, and Australia's export machine is priced off exactly this demand. A downside CPI surprise hands the bears the 0.6900 test they have been waiting for; an upside one buys the coil another week.
US Initial Jobless Claims follow at 12:30 GMT with 218K expected, and the heavier set pieces wait at month-end, when the RBA, the Federal Reserve (Fed) and the Bank of England all decide policy within roughly the same 48-hour window. Until Beijing or Washington breaks the tie, the 0.6900-0.6950 box is the market's honest opinion of the Australian Dollar.
AUD/USD technical levels to watch
Resistance: 0.6950 caps this week's candles, ahead of the 0.7000 handle and the falling 50-day EMA just above it; bulls own nothing until that zone breaks.
Support: The 200-day EMA at 0.6900 is the floor that matters, backed by 0.6850 sitting beneath last week's washout low.
Bias: Bearish while capped below 0.6950; a daily close under 0.6900 puts the June downtrend back in charge toward 0.6850, and only a daily close above 0.6950 earns the rebound another leg higher.
AUD/USD daily chart
Australian Dollar FAQs
One of the most significant factors for the Australian Dollar (AUD) is the level of interest rates set by the Reserve Bank of Australia (RBA). Because Australia is a resource-rich country another key driver is the price of its biggest export, Iron Ore. The health of the Chinese economy, its largest trading partner, is a factor, as well as inflation in Australia, its growth rate and Trade Balance. Market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – is also a factor, with risk-on positive for AUD.
The Reserve Bank of Australia (RBA) influences the Australian Dollar (AUD) by setting the level of interest rates that Australian banks can lend to each other. This influences the level of interest rates in the economy as a whole. The main goal of the RBA is to maintain a stable inflation rate of 2-3% by adjusting interest rates up or down. Relatively high interest rates compared to other major central banks support the AUD, and the opposite for relatively low. The RBA can also use quantitative easing and tightening to influence credit conditions, with the former AUD-negative and the latter AUD-positive.
China is Australia’s largest trading partner so the health of the Chinese economy is a major influence on the value of the Australian Dollar (AUD). When the Chinese economy is doing well it purchases more raw materials, goods and services from Australia, lifting demand for the AUD, and pushing up its value. The opposite is the case when the Chinese economy is not growing as fast as expected. Positive or negative surprises in Chinese growth data, therefore, often have a direct impact on the Australian Dollar and its pairs.
Iron Ore is Australia’s largest export, accounting for $118 billion a year according to data from 2021, with China as its primary destination. The price of Iron Ore, therefore, can be a driver of the Australian Dollar. Generally, if the price of Iron Ore rises, AUD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Iron Ore falls. Higher Iron Ore prices also tend to result in a greater likelihood of a positive Trade Balance for Australia, which is also positive of the AUD.
The Trade Balance, which is the difference between what a country earns from its exports versus what it pays for its imports, is another factor that can influence the value of the Australian Dollar. If Australia produces highly sought after exports, then its currency will gain in value purely from the surplus demand created from foreign buyers seeking to purchase its exports versus what it spends to purchase imports. Therefore, a positive net Trade Balance strengthens the AUD, with the opposite effect if the Trade Balance is negative.
Author
Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















